Sabre Insurance: profit on track, but broker cuts premium forecast by 2.3%

Analyst’s view:
I appreciate the company's decision to chose profitability over growth for the sake of growth. Their job is price their policies sensibly and generate ROE, which they've been doing. In August, at the full-year results, Roland was moderately positive on this stock. The market cap is a little lower today as the market digests the disappointment of slightly lower growth. But in the big picture, I expect that little has changed. So I'll leave Roland's moderately positive stance in place.
Down 9.5% at 167.8p (£409m) - Trading Update
Sabre Insurance Group plc (the "Group" or "Sabre"), one of the UK's leading motor insurance underwriters, today provides an update on trading for the period from 1 July 2026 to 30 September 2026.
At first glance, this trading update looked fine to me - "Full-year earnings guidance reiterated, with profit before tax for 2026 expected to be slightly higher than 2025"
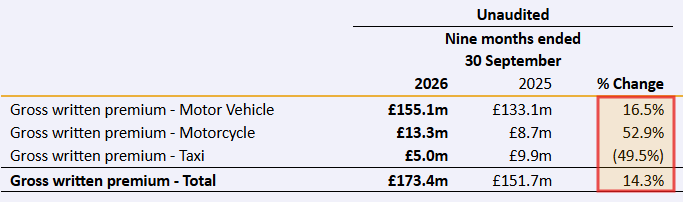
However, checking the note from Panmure Liberum, I see that they have in fact reduced their GWP (gross writen premium) estimate for the current year by 2.3%, from £236m to £231m.
The new estimate represents year-on-year growth of a little less than 14%.
The growth rate so far this year has been better than that, at 14.3%:
FY27 and F28 also see GWP shaved by small amounts (estimates cut by 0.4%).
Thankfully, the company's pre-tax profit estimates for each year have only received the slightest of trims, e.g. the current year's PBT estimate moves from £52m to £51.9m. Slightly better than last year's £51m result.
So I think it is fair to say that profit is tracking in line. The PBT cut is not material.
The more interesting line is the revenue line - why the pullback in growth expectations?
The company does explain why this is happening, without explicitly telling us that revenue might miss expectations:
Full-year earnings guidance reiterated, with profit before tax for 2026 expected to be slightly higher than 2025
Year-on-year premium growth is expected for the full-year, although growth is likely to moderate in the final quarter as Sabre's pricing discipline is maintained
In the market trends section, they tell us that claims inflation is still running at between 6% and 7%, and that "pricing does not appear to have kept up with the level of claims inflation".
As a result, "Material market-wide price increases are likely to be required to cover claims inflation, which we expect to provide additional momentum to our growth, although the timing remains uncertain".
In other words, Sabre thinks that other insurers have not yet raised prices to the level required.
And in the short-term, to maintain "pricing discipline", they are going to sacrifice some growth. Either growth or profitability needs to be sacrificed, and they have chosen growth.
The CEO comment emphasises this philosophy:
"I am very pleased with our performance through the first nine months of 2026. Our continuing focus on "profit as the target and volume as an outcome" underpins our confidence in delivering a strong full-year result, which we expect will be slightly ahead of 2025.
We have maintained pricing discipline, strong premium volumes and a robust solvency position despite continuing weak market conditions.
We will continue to apply this discipline and focus as we move into 2027 rather than pursue volume for its own sake.
Graham's view
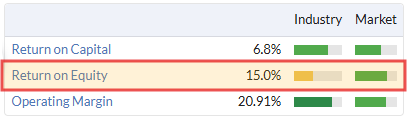
I appreciate this philosophy. An insurer's job is not to pursue growth for the sake of growth. Their job is price their policies sensibly and generate ROE.
Sabre has been doing this:
In August, at the full-year results, Roland was moderately positive on the stock. The market cap is a little lower today as the market digests the disappointment of slightly lower growth. But in the big picture, I expect that little has changed. So I'll leave Roland's moderately positive stance in place.
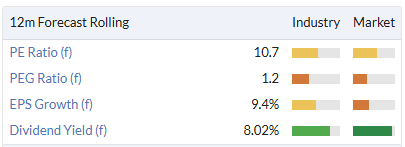
PBT growth might limited for the next couple of years, but I suspect that the main attraction here is actually the yield. The majority of EPS gets paid directly to the company's shareholders:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Sabre Insurance (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?