BP Marsh: NAV per share rises to 996p, but the shares still trade at a 32% discount

Analyst’s view:
The 32% discount to NAV does look rather excessive to me. Even if the major investment Pantheon Specialty turned out to be worthless, and was given a valuation of zero, the stock would still be trading at a discount to NAV (the Pantheon investment is valued at £112m, while the gap between NAV and market cap is £128m). So I think that BPM's share price already punishes it more than enough for having a concentrated portfolio.
Up 1% at 676.4p (£244m) - Half-year Results
B.P. Marsh & Partners Plc (AIM: BPM), the specialist private equity investor in early-stage financial services businesses, announces its unaudited Group Half Year Results for the six months to 31 July 2026...
We already had an H1 update from BPM in September.
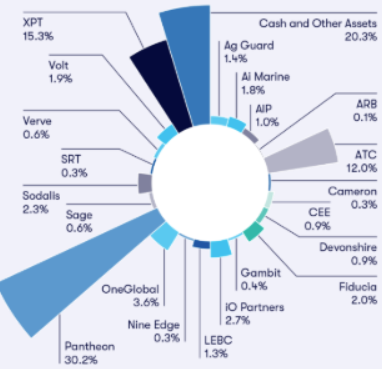
That day, I reduced our stance on the stock as it seemed to me that the growth at the main investee, Pantheon Specialty, was tracking a little below par. This single investment - where BPM owns 41% of it - is worth about 30% of BPM's total assets.
So my main interest in these half-year results is any update relating to Pantheon.
But first, the big picture:
BPM's NAV improves to £372m (Jan 2026: £360m), despiting paying £13m of dividends.
Fully diluted NAV per share increases to 996p (Jan 2026: 959.8p).
So there's been plenty of progress to maintain the upward trajectory of NAV and NAV per share over the six-month period, despite the dividends paid.
And the discount to NAV per share, at the current share price, is 32%.
That level of discount says very clearly that the market is nervous about BPM's portfolio valuations, its skill at managing the portfolio, or both! As a shareholder here, I do think the market is perhaps being too timid.
CEO comment from Dan Topping:
“I am pleased to report another strong period for B.P. Marsh. The first half of the financial year saw us convert value built up across the portfolio into cash, delivering meaningful returns to shareholders while continuing to invest for future growth...
Our approach builds on the partnership-led model established by Brian Marsh OBE, which has delivered compound NAV growth of 10.9% a year since flotation, after distributions. With £37.4m of available cash, no debt and a robust pipeline, the Group remains well placed to continue delivering long-term value for shareholders.”
One thing I do appreciate very much about BPM is how they have managed the problem of cash drag. A victim of their own success, they've had "too much" cash on their books, but have gradually reduced it via new investments (both debt and equity) and dividends. It strikes me that £37m is probably still a little too high.
Pantheon: I don't see anything new in today's section on Pantheon:
...Pantheon has established itself as a high-quality, scalable independent specialty broking platform with a growing reputation for the placement of complex risks. Revenue is budgeted to approach £27.7m in the 2026 financial year, compared with approximately £23.8m in 2025, with strong margins and significant cash generation supporting continued reinvestment and growth. Pantheon remains the largest contributor to the Group's NAV, demonstrating the significant value created since the Group's original investment.
The metrics here are quite remarkable:
Date of initial investment: June 2023
31 July 2026 valuation: £112,360,000
Cost of Equity: £32,800,025
Equity stake: 41.0%
Pantheon's weight in the portfolio now exceeds 30%:
Group Outlook is strong:
"With £37.4m of Group funds at 31 July 2026, no debt, a growing income base and a robust pipeline, the Group remains well positioned to balance selective new investment with continued returns to shareholders, and to support its entrepreneurial management teams as they grow their businesses."
Graham's view
I am happy to continue holding a small position here, as the 32% discount to NAV does look rather excessive to me.
Even if Pantheon Specialty turned out to be worthless, and was given a valuation of zero, the stock would still be trading at a discount to NAV (the Pantheon investment is valued at £112m, while the gap between NAV and market cap is £128m).
So I think that BPM's share price already punishes it more than enough for not having a very concentrated portfolio.
I could be wrong, of course. But the track record here is genuinely outstanding. So this is a bet I'm personally very comfortable with. I'll leave us on AMBER/GREEN for now, as I wait for a fresh update on Pantheon.
At the time of publication, Graham has a long position in BPM.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on B.P. Marsh & Partners (3)
Comments here are also visible in the Daily Stock Market Report
re B.P. Marsh & Partners (LON:BPM) This article on buyouts and M&A might be of interest as background info on the state of play, even if it does not mention their direct holdings
B.P. Marsh & Partners (LON:BPM)
cheers useful summary and it can only be good for BPM if the trend is towards acquisition of the ready made entity type that BPM is helping incubate. How big is to big to buy in though ?
B.P. Marsh & Partners (LON:BPM)
another good 6 month period here - fully diluted NAV per share up from 960p to 996p - plus 36p per share of dividends have been voted in the period.they have calculated total shareholder return of 7% which is excellent for 6 monthn period,
Graham made some excellent comments about Pantheon their biggest investment (by current value) on 22nd September in that growth kinda appear to be not quite at rate previously expected (previosuly something apporaching £30 mill sales had been mentioned) . looking at 12 month uplift in Pantheon value thats only 1.3% higher total value for that company (actual value has gone up more due to extra investment) If we look at expected sales growth thats 16% if we compare 2026 forecasts to 2025. so the valuation increase here looks pretty modest last 12 months. Note i would say based on the 2025 accounts the £275 mill valuation of the company looks pretty "steep" PANTHEON SPECIALTY LIMITED had profit after tax of under £10 million - so i think that business needs to show continued progress towards figure of £15 to £20 mill perhaps? - or at minimum keep churning out double digit growth long term - note the trading entity voted £9 million of dividends up to the parent company so that suggests that suggests there is the potential for some decent dividends to be received while they hold.
overall still trending nicely with decent uplifts in value and some decent divi payouts - with shareprice being pretty much where it was 2 years ago its pretty simple that its looking better value than it did in november 2024 when price first popped above 700p due to increase discount to NTAV. Perhaps though the 700p might have been slighty ahear of itself. Should there be an extra discount given to reflect the fect that Pantheon is worth 46% of the market cap - yes i think that is very fair and reaosnable so i can see the logic as to why the shareprice discount to NTAV may stay high until there is more tangible progress ref Pantheon - i would deffo prefer they were reducing stake rather than increasing - i suspect the main bods there who sold out kinda wanted to bank some real rewards ref their hard work so i aint gonna grumble about the extra investment.