Good news finds a high StockRank - and now we know why

Over the last 18 months, we’ve been researching three words that show up regularly in trading statements: “ahead of expectations”. When a company makes a positive announcement, the shares often jump that morning, and more often than not, keep drifting in the same direction for months. Of course, the real money to be made is in stocks that say it again and again. Computacenter (CCC) is one such example, with now four positive announcements in a row, and the shares up 140% since last September.
I’ve been an advocate of buying high-ranked shares after a positive announcement - and it’s a strategy that works - but the question I get asked more than others, is how do you find these shares before they make their first positive announcement? Can we predict positive surprises?
Yes we can - but in a roundabout way
We have taken every UK trading update and results statement since the start of 2025 where the news could be classified - that’s about 4,860 announcements - and we’ve marked each as positive (the company beat expectations or raised guidance), negative (it missed or cut) or neither. Then we sorted them by the company's StockRank on the day.
A share ranked over 90 delivered good news 32% of the time and bad news 9% of the time. That’s nearly four pieces of good news for every negative. A share ranked under 40 delivered good news 22% of the time and bad news 16%.
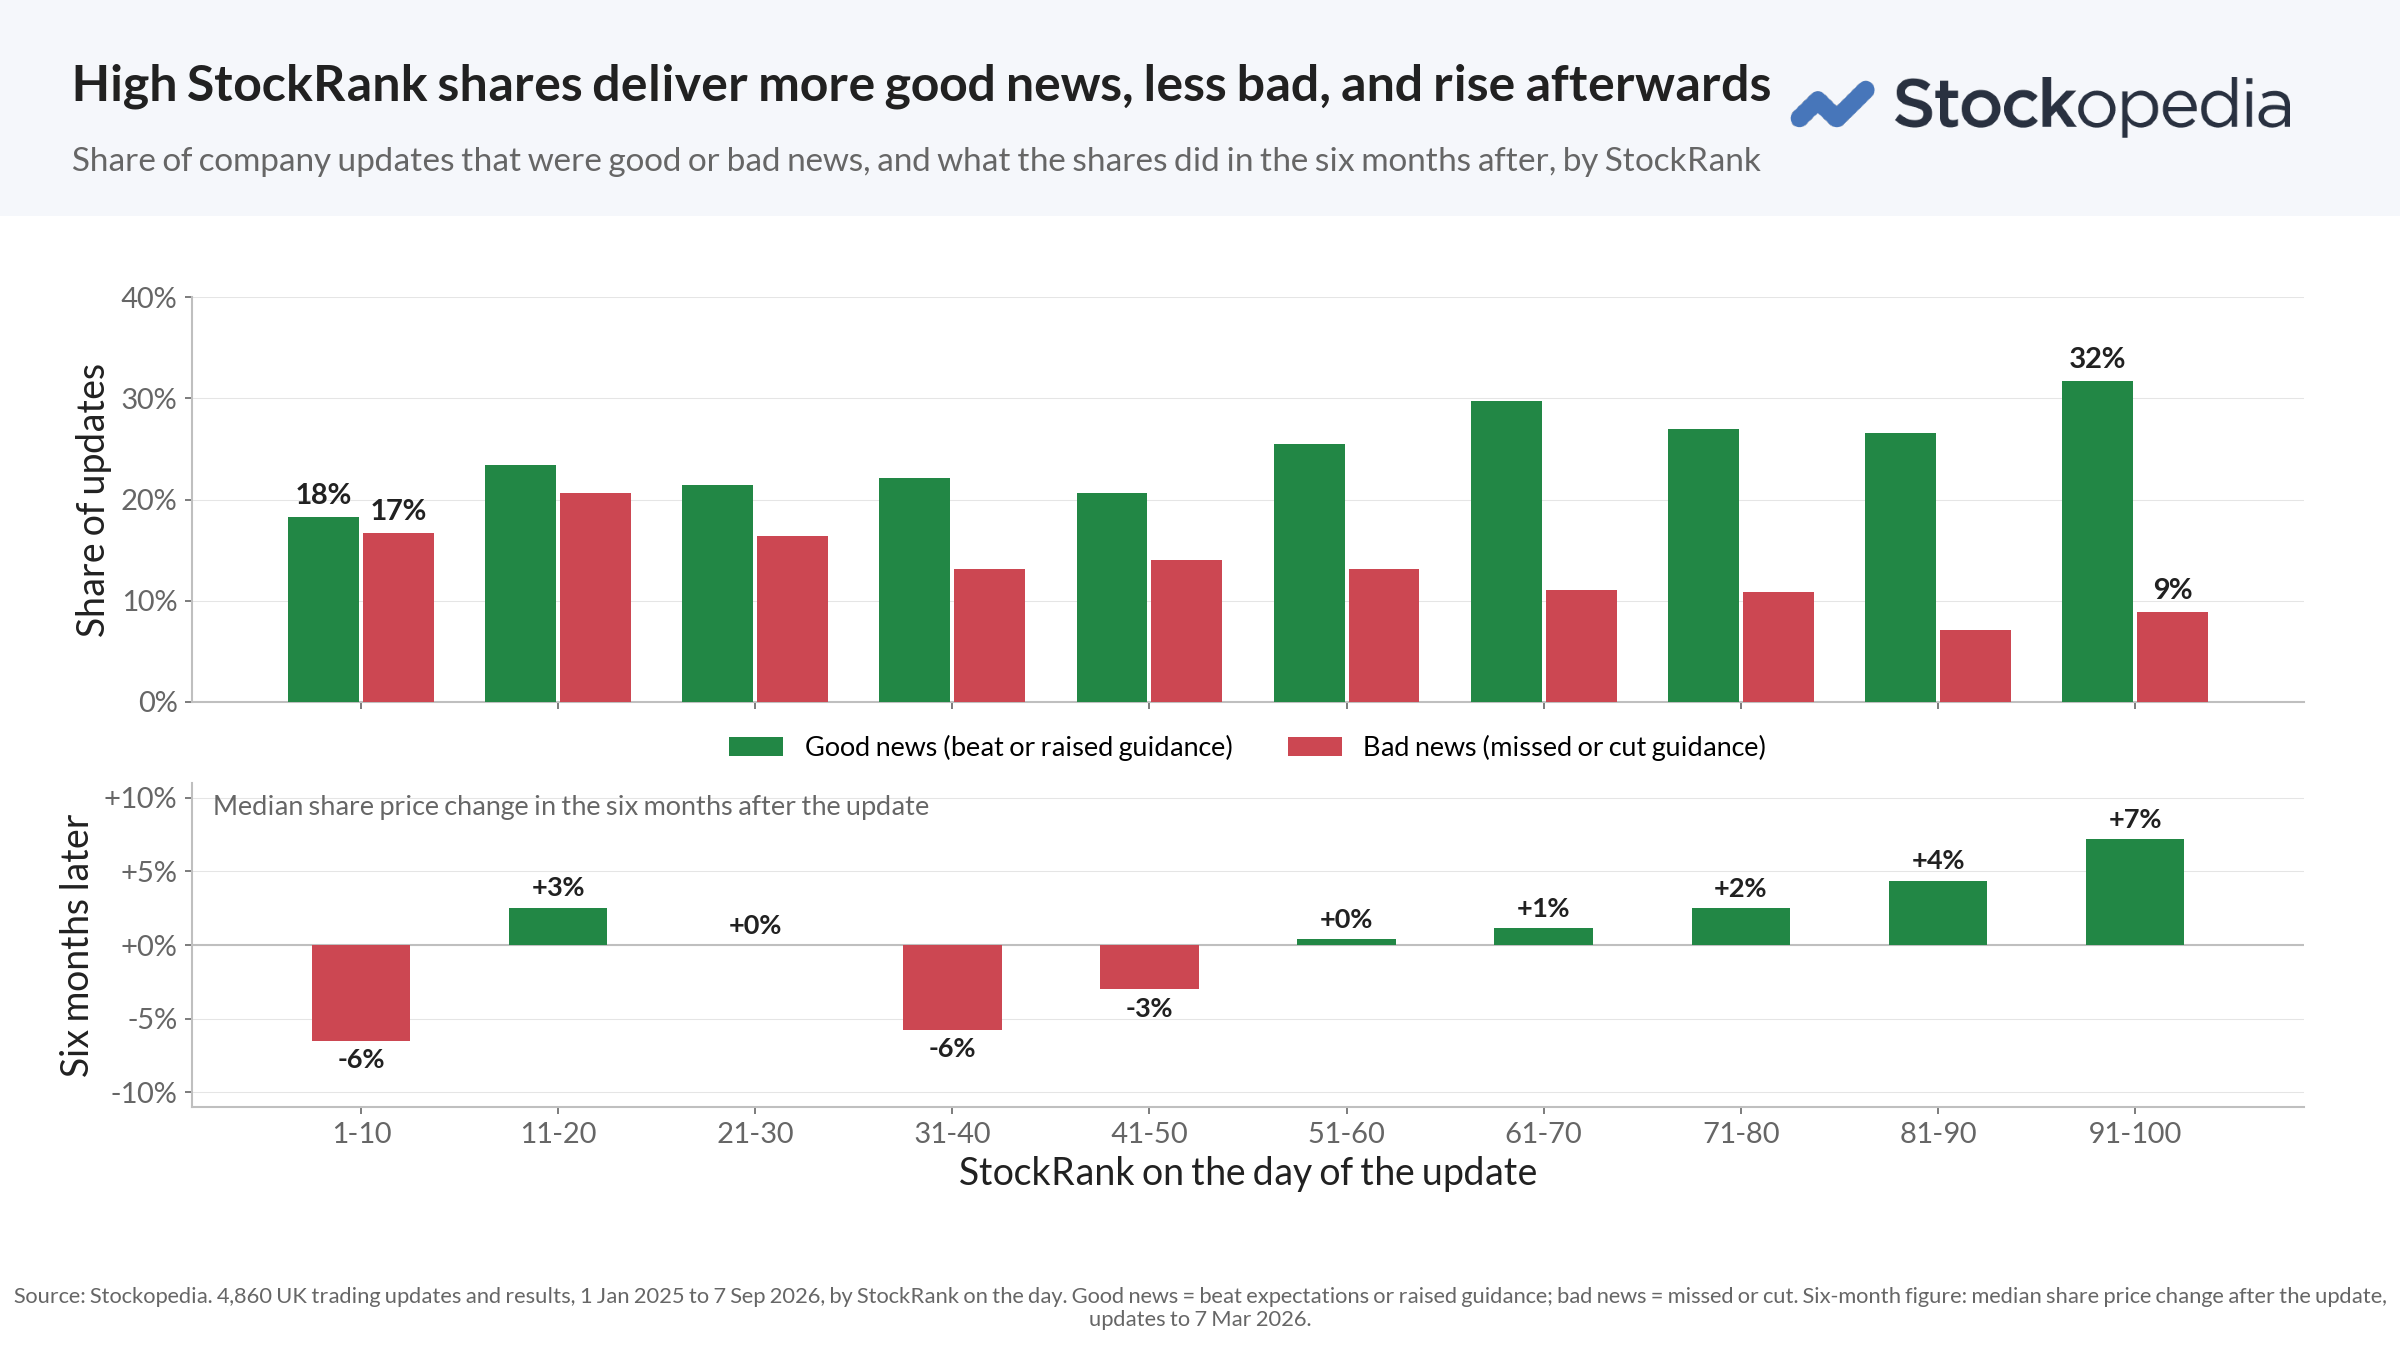
It’s a small edge, but it’s a significant edge. A higher StockRank seems to predict positive surprises. The StockRank knows nothing about the next statement, but it does know three things - the business is likely to be boringly profitable, with shares quite lowly priced, with improving market and analyst sentiment. These are the traits of a stock that’s more likely than not to publish good news.
Computacenter provides a model
For most of 2025 Computacenter's StockRank sat below 75 - not on my radar. But on the 9th September 2025 it published its half-year results - revenue was up 31%, profit down 4%, with a "strong start" to the third quarter. The shares rose 4% on the day - positive, but not wildly eye-catching.
But the next morning the StockRank jumped from 68 to 91. New fundamentals, broker forecasts upgraded, and the momentum rank went from 42 to 84 overnight. Last month we shared research into the StockRanks Jump Effect- and this has turned into a classic example.
From that date on the shares ground higher. Then came a sequence of “beats”. On 22nd January the company said the year was running "ahead of expectations” - the shares moved +10%. On 24th April it said the first half would be "much stronger" than anticipated and raised guidance: another +15%. On the 9th July, it was “ahead of expectations" again, with first-half profit double the year before: up another 7%. And today, another “significantly ahead” announcement.
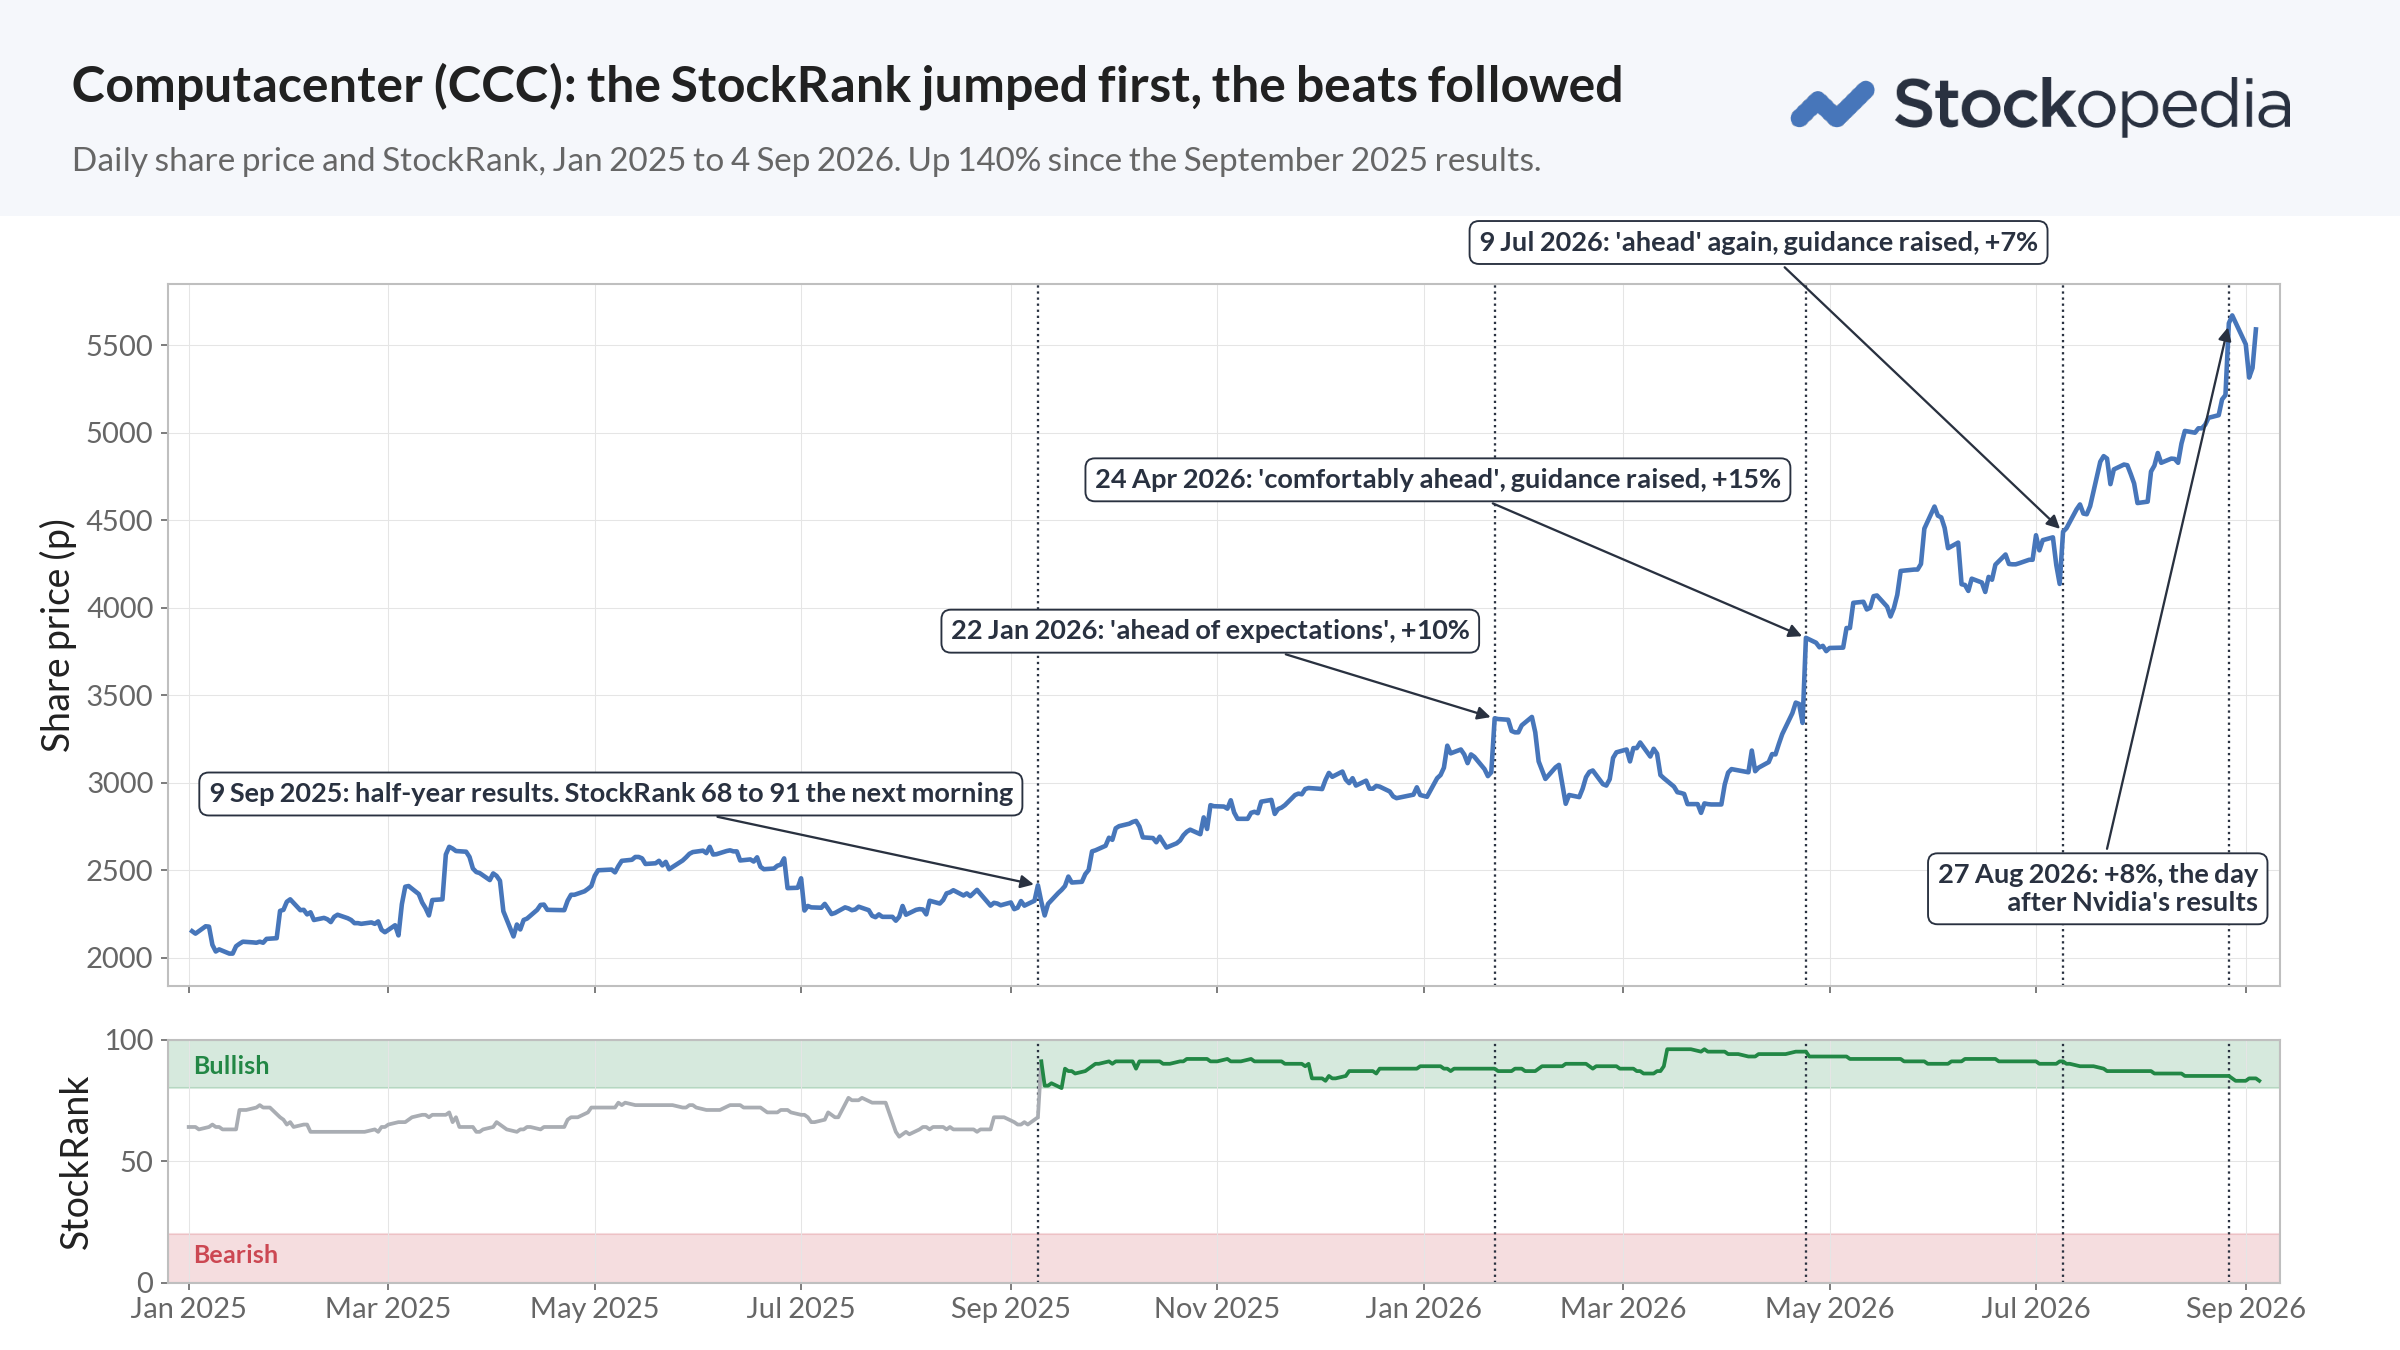
Of course, there has been a narrative behind the moving share price. There always is. But this one had the word of the year in it “hyperscale”. Computacenter supplies and installs equipment that big cloud companies need for their data centres. It’s North American business went from a “record performance" last September to profits that "nearly doubled" by March. When Nvidia reported last month, Computacenter rose 8% the next morning. And today half-year results are “significantly ahead” of expectations - although the shares are going the other way - whether this is temporary glitch or a top remains to be seen.
Market expectations can be systematically too low
For decades the textbook answer for why cheap shares (value stocks) and rising shares (momentum stocks) beat the market has been that they are “riskier”. You should get paid extra for holding something risky. But it’s quite hard to prove they are. Yes among cheap companies there are some that are financially distressed - but those stocks are easily identified and they have dismal returns. So the reason for the outperformance may not be risk.
But last September some Oxford and Harvard academics tested a new angle. They took every analyst's profit forecast for every American stock over forty years, and asked a question: when cheap shares beat the market, is it because they were risky, or because the forecasts for them were simply too low?
The expectations were systematically too low. Almost all the extra return on cheap shares, and on rising momentum ones, turned out to be the market catching up with unexpected profits. The market is just too negative on cheap, improving companies and too excited about glamorous ones. When results and trading statements come in - expectations get beaten. The title of the paper lays this out - “Finance Without Exotic Risk”. There’s no mysterious risk explanation required. The difference in returns comes down to expectation mistakes. And they are predictable.
How expectation mistakes get corrected
For Computacenter - back in July 2025, the shares were priced at £22 with profit forecasts for 2027 at 197p - a forecast P/E of 11x. Today they are priced at £53 per share with profit forecasts of 241p - a forecast P/E of 21x.. The shares were priced too cheap. Computacenter beat expectations again and again. The belief flipped, the P/E ratio doubled. That’s the market correcting its forecasting mistake - rather than repricing a risk.
Anyway, enough of the theory - if we pull the StockRank apart we can see which part does which job on good news.
- Momentum predicts beats: Earnings surprises tend to follow earnings surprises - a momentum rank over 80 identifies beats 39% of the time, while lower momentum ranks only identify 19% of them.
- Value gets you paid: six months after a positive surprise, cheap 80+ value ranked stocks were up 7%, expensive ones only 2%. There’s more return in cheaper stocks.
- Quality helps avoid misses - we found that high Quality stocks halved the miss rate of low quality stocks.
So all three ranks do work together to drive returns before and after announcements.
This year's serial beaters
Since January, 106 UK companies have carried a StockRank over 80 on the day of their first beat of the year. These are the ones that kept going, with two that did not.
| Company | Beats / raises in 2026 | StockRank at first beat | Since first beat |
|---|---|---|---|
| Ramsdens Holdings (LON:RFX) | 5 / 5 | 98 | +60%, then a bid at 684p |
| Dialight (LON:DIA) | 4 / 4 | 81 | +61% |
| Computacenter (LON:CCC) | 3 / 2 | 88 | +66% |
| Luceco (LON:LUCE) | 4 / 4 | 84 | +45% |
| Keller (LON:KLR) | 3 / 1 | 93 | +37% |
| Vertu Motors (LON:VTU) | 3 / 1 | 93 | +34% |
| Halfords (LON:HFD) | 2 / 2 | 96 | +22% |
| CMC Markets (LON:CMCX) | 1 / 1 | 89 | +18%, after +42% on the day |
| Morgan Sindall (LON:MGNS) | 3 / 4 | 86 | −20% |
| Peel Hunt (LON:PEEL) | 2 / 1 | 82 | −22% |
I share the list as a set of case studies. The best thing to do in investing is look at the common traits and behaviours of past winners. Learn from them. And look for shares that rhyme in future.
How to apply the insights
There are a couple of options to raise the odds of finding “ahead of expectations” shares in your portfolio.
- Firstly, the lazy approach is to apply a NAPS style process - twenty shares, the two highest-ranked in each sector, equal weight, hold for a year. You let the trading and results statements roll in. You are not picking companies specifically to beat expectations; you are just picking twenty that the market has most underestimated. I wrote about the NAPS performance in Friday's newsletter - the portfolio is up 26.5% this year, and thirteen of the twenty have beaten at least once. It works.
- The active way is more like “The Setup”: look for "ahead of expectations" announcements, a jump of 10% or more on the day, a StockRank over 75, and six months of patience. I have to review the stats asthe performance of this approach has been more muted year to date - but it’s the principle that counts - if you can find the catalytic moments in individual shares - you can find shares like Ramsdens, CMC, Computacenter and more.
Whatever you choose - here’s the key rule in a takeaway: Buy where market expectations are too low, and let the trading statements confirm it. A StockRank over 80 has delivered nearly four pieces of good news for every bad one, and the shares have typically been higher six months later.
Please do share your own insights on this theme in the comments below !
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
Hi Ed,
Another great article, thanks.
Stockopedia’s research on when to Buy has been hugely insightful and profitable for me personally.
Where I struggle is deciding when to Sell. I have my own rules in place, but they lack a real scientific framework and I always fear that I'll be getting out of a position too soon.
If you ever happen to research sell strategies, the insights would certainly be interesting to read.
Thanks again
My observations on shares beating expectations with high stock rank are that 80-90% of these will pull back to either the low of the day they beat expectations, the gap to the day before close, or will briefly fill the gap, before reclaiming that area and proceed in the majority of cases to make a tradeable move up. Morgan Sindall last year was a classic example of this. However the 10-20% who dont pull back tend to make the largest returns. I`m still learning this but my guess is that the ones that move up are ones which have genuinely surprised the market with their expectations beat- they were quietly consolidating in the days/weeks before the market beating announcement, though CMC Markets was an exception as it was already rising before it jumped 42% in a day. But its earnings beat was exceptional, hence a surprise. So if you`re trading these, I think you need to ask how much of a surprise was the earnings beat, and if you`re not sure is it better to wait for the pull back. Institutions I have heard dont chase shares.
Ed,
There is some new expectation-error research that considers another angle that can be applied to the StockRank components: Do Institutional Investors Exploit Expectation Errors in Value/Glamour Stocks? (2026), spanning multiple decades of US data, with a shorter non-US robustness check.
If we apply this Expectation-Error research to dig further into your individual Ranking bullet points:
The research found that it's cheap P/B stocks (a moderate proxy for high ValueRank) together with a high Piotroski F-Score (a good proxy for high QualityRank) that pay out best. So, in addition to the overall StockRank score, it's probably worth digging into the individual Rank components.
So who are the losers? The authors controversially "conjecture" that less-informed retail investors are being out-traded by the speed and depth of institutional analysis of improving-value and/or overpriced-glamour companies. This dynamic may be one reason smaller, less-covered companies offer more of an edge to Stocko investors able to use Rank scoring.
How about a stock that meets the research criteria? I'm going to suggest James Cropper (LON:CRPR), which I own, which is scheduled to issue its AGM trading update at 7am today.
Back in April James Cropper (LON:CRPR) saw a +25% jump on a 10% ahead-of-expectations trading RNS. The QVM scores at the time were 86, 75 and 60 (SR = 90), versus 88, 64 and 89 (SR = 96) today. Add to this: no new institution — the kind of buying that could erode the edge has publicly entered the stock since the April RNS.
Not long to wait!
So a muted response to the James Cropper (LON:CRPR) “in line” AGM update this week with no sales metrics to guide progress:
The house broker Singer, kept the EPS flat, but upped the sum of the parts target price from 560p → 650p (+16%), which is yet to be reflected in its share price. Looks like we have to wait for another “ahead”!
I trust the rankings and refuse to be spooked by Computacenter dropping 7.8% on today's trading update!
I am a bit confused, though, how IGG continues to rank in the 90s while its shares have plummeted 25% since news of the Underdog takeover.
And I've been keeping a nervous eye on Hill & Smith and the potential reverse jump effect (slump effect?) since its Stock Rank fell from from 79 to 66 over a few days: the share price and underlying fundamentals still look good to me.
(all above stock I hold)
Thanks Ed, another great, thought provoking article. I bought into TT electronics (LON:TTG) this week after SR jump last 30 days of 27 and an "ahead" RNS last week. Looks an interesting recovery story with a new CEO, focussed in the right sectors, with a positive outlook. Chart supportive too, recent "golden cross". We shall see........
Since market tend to be slow to react to earning surprises. I wonder if we can setup a filter to identify under-priced stocks with improving fundamentals and recent earnings surprise supported by earning upgrade and strong 6 month price relative strength and 15% stop-loss to prevent jumping onto one-off earning surprises and limit the downside risk.
Buy rules: StockRank > 80; F-Score > 7; EPS surprise % > 5%; Sales surprise% > 5%; 1M Earning upgrade > 5%; and 6 month price relative strength > 5%. Buy a portfolio of 10 to 20 stocks and review on a monthly basis. I wonder if this would work in the real world?
Thanks for a great article.
Its interesting that all three factors contribute to this effect.
I'm certainly sold on the rule explained repeatedly and patiently to us all. Although I happily embrace the annual Naps starter list, I soon substitute laggard shares for those in the daily reports including the terms helpfully emboldened in bold black letters, "trading ahead of expectations". It has certainly worked well for me so far and I welcome just this sort of reminder article/newsletter to kee us on track.
I hope it's not too often - and that I'm not boring you with the repetition. It's really allied with our own research and development track - so it's in the front of mind most weeks for me.
Beauty Tech (LON:TBTG) has issued three since it's IPO in October 2025:
19/11 - Trading Ahead of Expectations
08/01 - Ahead of Upgraded Expectations
07/07 - Upgrade to FY Expectations
Half year earnings release is on 17 September. StockRank 68, MomentumRank 93.
Everything tells me to buy in before the next news but I just can't get myself to do so... Recent IPO, not enough data, not a great moat... am I overthinking this??
Trust the algorithms, but buy a small position and add as your confidence grows?
Beauty Tech (LON:TBTG)
This one looks kinda odd - all i can guess is that you are twirly here to the party.
its clearly lacking in the value department
To me i think thats perhaps most likely to simply be that we dont have any 2026 actual numbers yet to backup the trending good news.
I think its newly listed too so its perhaps as clear as mud to stocky that this is all good clean positive trending stuff - and without the history of lfl data its presumably sitting on the fence until the dust settles - that may take a while.
it perhaps also doesnt help that the company is using EBITDA as its yardstick - EBITDA can hide so many sins that just leaves us the stocky numbers that do appear to be trenbding upwards too ref net profit.
It certainly all looks positive - but the pudding really is the 6 montghly accounts that show that its all lean and mean at the bottom line profits that matter - for now i kinda get it why stocky would be sitting on the fence.
With the positive updates though it doesnt seem likley that it will be a bad update next - so that perhaps might leave red flags ref the earnings not being lean and mean - in that regard one really needs to see the results.
Not sure if there are any detailed broker notes that woluld give info ref bottom line cashflow etc.
It does seem kinda tempting to have a punt here - the only slight recent negative is that 1 and 3 month momentum has turned negative ? seems sense that shareprice increase makes it natural that there would be a pause for breath at some stage - in teh absence of results now kinda makes sense.
Not sure if there are any red flags here ? often new floats are people running for the door cashing their chips in with everything having been impoed up - i know little about reasons for float though so that may be harsh.
Beauty Tech (LON:TBTG)here is some random tittle tattle from poster on the other place i dont really know how useful or informaed it is.
I would say its logical to preume there is some decent seasonality here
I thought it was a pretty cunning RNS to be honest.
Firstly, H225 revenue was £85.8m, so the prior 2026 forecast for £161.7m was sandbagged at below the H2 run rate.
H125 revenue was £55.2m, so again, the fact they are 'materially ahead' of that figure doesn't mean much. Why not wait a couple of weeks and tell us what the actual H1 revenue number was?
I came to the conclusion that this RNS was most likely designed to support the share price & provide exit liquidity to selling pre IPO holders. This may well be wrong, but it's an opinion that has apparent logic.
The H1 actual that is disclosed next week will confirm either way. If I had to guess I think it'll be £60-70m, 'materially ahead' of H125, but 'materially below' H225.
The way it's been trading certainly suggests this.
asking copilot it comes up with estimates splits growth looks ok to me and it seems to be down to seasonalityy though
ity does seem company could have been more transparent
Assume H1 FY26 = £65m
Period Revenue Growth
H1 2025 £55.2m -
H1 2026 £65.0m 17.8%
H2 2025 £85.8m -
H2 2026 £105.0m 22.4%
FY26 £170.0m 20.6%
I have a modest position in this, although I usually steer clear of recent IPOs. Maybe the company were a little sneaky not putting in a revenue estimate for the half year, but I think you are completely correct in pointing out the seasonality. Expensive beauty tech is most definitely going to sell better over Christmas. I expect the H1 number to be not too far off the estimate, I'd expect a bit nearer £70m though. If people are disappointed by this, it might be an entry opportunity, although I think many will understand the seasonality and pay more attention to any forward looking statements.
I should have hung onto mine longer after the IPO pop !
I bought Beauty Tech (LON:TBTG) after the July "ahead" RNS and have seen the share price go gently backwards. Confident of a good story here though and SP rise of c6% today a good sign - maybe a run up to results on 17/9?
Ed I'm a believer. Stockopedia is curing me steadily from my worst habits, and using Stock rank information as advised has worked for me. We are lucky enough to be waiting for the imminent pay-out on Ramsdens, which for once I hadn't sold to soon, unlike Luceco Vertu and Halfords which I did. Your condensing of it into Momentum Value and Quality is something even I can remember to check as my finger hovers over the Buy or Sell key. Thank you.
Computacentre , seems harsh today with a solid set of results and up grading again and a good back order over 9 billion .
I'm thinking the same thing
profit taking ?