Gratfon Group maintains full year guidance; another year of solid progress on track

Analyst’s view:
This currently enjoys Super Stock status. When Roland studied it in May, at a share price of around 800p, he suggested that it was fairly valued at a PE of about 10-12x. After all, it's a retailer with average quality metrics. I don't disagree - this may indeed be a fair valuation - but I think we can afford to increase our stance on this by one notch, to AMBER/GREEN, to reflect its potential attractions as a long-term investment idea. It has an excellent track record of profitability over many years, market-leading positions, and stable leadership in the form of CEO Eric Born.
Down 1.5% at £10.16 (£1.9bn) - Trading Update
Today's update from Grafton leaves full year profit guidance unchanged.
Grafton is "the European multinational distributor of construction-related products and solutions", famous for brands such as Selco and Leyland (in England) and Chadwicks and Woodie's (in Ireland).
Today's trading update covers the four months from July to October:
Like-for-like revenue growth of 2% (vs. 0.6%) in H1
"Strong momentum maintained in Iberia, continued growth in the Island of Ireland and positive trading in Northern Europe helped offset weak market conditions in GB"
Full‑year guidance of adjusted operating profit of £190m - £200m maintained. The consensus adjusted operating profit figure is £194.1m.
The total year-on-year revenue increase is 7.4%, a figure which makes no adjustments for acquisitions, currency effects, or changes in the number of trading days each year.
Thinking about the geographic split of revenues, Ireland is the biggest contributor at 43% of the total (using H1 figures). Great Britain is 27.5%, while Iberia is the smallest contributor at 11%.
So it's slightly unfortunate that Iberia is the fastest grower. Here's the change in like-for-like revenue year-to-date:
Ireland +4.7%
Great Britain minus 5.2%
Northern Europe +1.1%
Iberia +6.9%
The total result year-to-date is therefore 1.2%. As Grafton already highlighted, growth has improved in more recent months as compared with H1 (so the "second derivative" is positive!).
The performance in Ireland was "underpinned by leading market positions and unrivalled scale in our home market" - Chadwick's and Woodie's are undeniably market leaders here, giving the company some additional pricing power.
In Great Britain, "the weak market conditions seen in the first half continued as anticipated".
Buyback: a £25m buyback completed in September at a share price of £9.58. It's good to see that the company is not already underwater on these trades, but the buyback has only reduced the share count by around 1%.
CEO comment:
“The Group has traded well through the important Autumn season, with the resilience of our diversified geographic footprint showing the benefits of our business model. We are pleased to report growth and improving momentum in three of our four geographic markets. As we approach year end, Grafton is well placed to benefit from its exposure to growth and recovery markets, leveraging its strong operating performance and balance sheet to pursue value-enhancing acquisitions in 2027 and beyond..."
Graham's view
Like most Irish people, I'm familiar with the Woodie's brand and would tend to trust it for any home improvement and DIY needs.
That said, there are also objective reasons for us to be more optimistic on this stock than we've been before.
It currently enjoys Super Stock status:
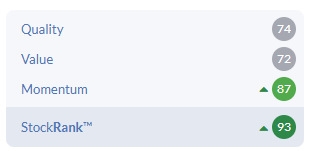
When Roland studied it in May, at a share price of around 800p, he suggested that it was fairly valued at a PE of about 10-12x. After all, it's a retailer with average quality metrics:
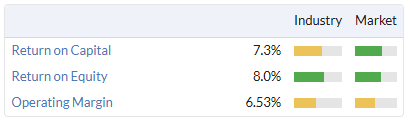
I don't disagree - this may indeed be a fair valuation - but I think we can afford to increase our stance on this by one notch, to AMBER/GREEN, to reflect its potential attractions as a long-term investment idea. It has an excellent track record of profitability over many years, market-leading positions, and stable leadership in the form of CEO Eric Born. So I think we can be slightly more optimistic than a purely neutral stance would suggest.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Grafton (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?