GSK: Q3 beat overshadowed by 2% drop in vaccine sales, we hold our view

Analyst’s view:
GSK's third-quarter vaccine sales appear to have fallen below City estimates, despite overall Q3 results coming in slightly higher than expected. While a forward P/E of 10 leaves GSK trading at a tempting discount to rival AstraZeneca, CEO Luke Miels still needs to prove that his drug pipeline can return the business to sustainable growth. I'm going to mirror the StockRanks and remain neutral today.
Down 6% at 1,810p (£72.5bn) - Q3 2026 Results
Full-year guidance was left unchanged in this morning's Q3 results from GSK, but the market appears to have been unimpressed all the same. Shares in the FTSE 100 pharmaceutical group are down by 7% as I type.
Let's try to understand why.
Q3 results: key points
The headline figures for the third quarter appear mixed, depending on which version of profit you prefer (% at constant exchange rates):
Revenue up 5% to £8,887m
Operating profit down 16% to £2,127m
Core operating profit up 5% to £3,076m
Core EPS up 1% to 54.6p
Cash generated from operations up 24% to £3,122m
So far, so unremarkable.
Drilling into GSK's divisional sales suggests that a fall in vaccine sales may be one reason for today's sell-off, despite a strong performance for the group's Specialty Medicines division:
Specialty Medicines up 15% to £3,877m
Vaccines down 2% to £2,583m
We don't have access to broker coverage for GSK, but newswire commentary this morning suggests that while overall Q3 results were ahead of expectations, vaccine sales were below analysts' estimates.
Sales of the company's new asthma drug, Exdensur, are also said to have been lower than expected.
Pipeline worries: CEO Luke Miels is keen to emphasise the potential of GSK's drug pipeline - a longstanding concern for investors:
Over recent months we have received 3 new specialty medicine approvals in the US: Hibsago, which has the potential to transform the treatment of chronic hepatitis B; Jideytro in non-small cell lung cancer; and Jemperli in rectal cancer. More broadly, in the late-stage portfolio, we are on track to start 22 phase III trials this year.
However, the market reaction to today's third-quarter update suggests to me that investors are unwilling to credit Miels with rejuvenating GSK's portfolio until more tangible evidence is available.
Perhaps wisely, Miels isn't relying solely on new products to boost profits. He's also in the middle of a cost-cutting programme that's expected to deliver £1.9bn of annual cost savings. This exercise is due to complete by 2029, but the bulk of the £2.4bn cost of delivery will be booked in 2026 and 2027. I would guess this could dampen profit and cash generation in those years.
Outlook
Despite the market's apparent concerns over today's results, GSK has left its 2026 guidance unchanged today:
Revenue to increase by 3% to 5%, "at the upper half of the range"
Core operating profit to increase by 7% to 9%, "at the upper half of the range"
Core EPS to increase by 7% to 9%, "at the lower half of the range"
2026 forecasts have been stable in recent months, but 2027 estimates have edged lower. I'm not sure if today's results will change either of these figures:
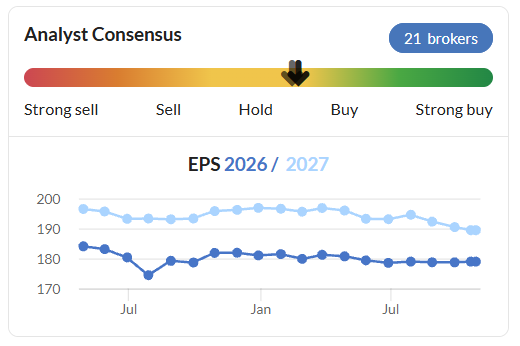
Assuming no significant change to estimates, today's share price drop leaves GSK trading on around 10x 2026 forecast earnings, with a potential 3.9% dividend yield.
Roland's view
Looming patent expiries and the unproven strength of GSK's new drug pipeline are both longstanding concerns for investors.
In his previous role as chief operating officer, Luke Miels was credited with making good progress at rebuilding the company's portfolio and taking steps to address these concerns. I guess it's only natural that his efforts will remain under the spotlight now he's in charge of the group.
I'm reluctant to read too much into three month's results, especially as this business is too large and complex for me to analyse in detail.
When owning and analysing companies like this, I tend to focus on the big picture numbers such as revenue growth, margins and free cash flow.
While I'd be concerned to see vaccine sales decline over the full year, the company's guidance for sales to be"broadly stable to an increase at low single-digit percentage" is unchanged today.
Guidance for Specialty Medicines is also unchanged, with GSK guiding for a "low double-digit increase" in sales this year.
If GSK can deliver on its turnaround plans and develop enough new blockbuster drugs to offset patent deliveries, then I think the shares could offer value at current levels. After all, on a P/E of 10, GSK remains at a sizeable discount to its London-listed rival AstraZeneca, on a P/E of 15.
However, turning around a supertanker-sized business is never easy. GSK has also disappointed investors before.
On balance, I'm going to mirror the StockRanks and leave our neutral view unchanged today, ahead of next year's full-year results.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on GSK (1)
Comments here are also visible in the Daily Stock Market Report
GSK (LON:GSK) Q3 results today - headline "...strong Q3 performance and continued momentum" with full year guidance reaffirmed. However as I write sp down 5.6%. Any thoughts on the reaction?