Haleon - Struggling with revenue growth and on an uninspiring valuation
Analyst’s view:
It's unclear whether today's update is a profit warning, and I can't see any updated broker coverage to confirm. However, the reduced revenue guidance would certainly require significant management action to maintain profit forecasts on lower revenue.
As such, it makes sense for the market to be more cautious on the company today. Fundamentally, I struggle to see the attraction of this business at the current rating, even if profit forecasts are maintained for the full year. The brands the company owns are certainly valuable, but in many categories they are already significantly more expensive than identical generics and rely on an uninformed consumer preferring a branded option. As such, this would seem to limit their ability to grow by pushing through above-inflation price rises. Volume growth may also be tricky in more mature product categories.
Their commitment to an increased share buyback amid challenging market conditions may be seen as a sign of strength. However, combined with the current valuation, it instead raises questions for me about the quality of their capital allocation decision-making.
The algorithms currently rate this a high flyer, but this is a designation that is unlikely to survive the impact of today's update being processed. With an uninspiring and likely declining Stock Rank, I am broadly negative here. AMBER/RED
Down 15% to 318p (£32.9bn) - Q3 Trading Statement
It looks like we haven't reviewed this consumer healthcare group on the DSMR before. Haleon came out of GSK’s consumer healthcare arm. In 2015, GSK combined that business with Novartis’s consumer unit, then bought Novartis out in 2018. In 2019, it merged the business with Pfizer’s consumer healthcare unit, with GSK holding 68% and Pfizer 32%. GSK then spun it off as an independent company, and Haleon listed in July 2022.
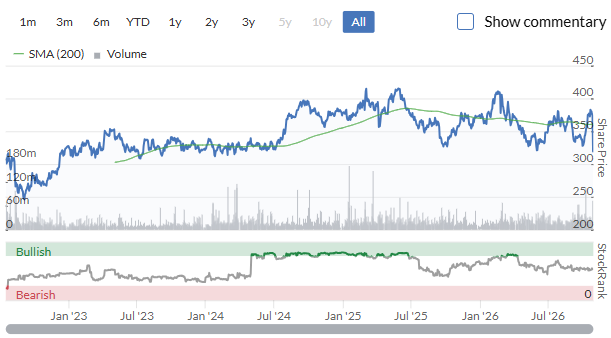
With just a 2% or so dividend yield over that time and a largely flat share price, this has been a disappointing hold for those who received the spin-off shares. They have an ongoing buyback, but it has only reduced the share count by 5% in four years and seems to have negligible impact on the share price.
Part of the problem appears to be that the company trades at a premium to the market and sector, but hasn't delivered the growth expected:
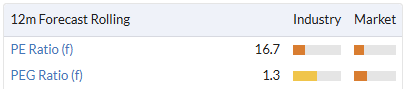
The market's valuation of consumer healthcare brands makes it sense for their parent to spin this off, as it trades at a significant premium to GSK's own equity.
However, despite a decent operating margin, I have to say I'm a little disappointed at the largely single-digit percentage return metrics here:
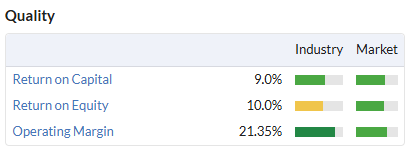
I seriously question whether a company with these quality metrics, at the current valuation and with the forecast growth, should be buying back shares at all.
Today's update:
The company makes us do the annoying thing of clicking through to a PDF to see the announcement. Presumably, this is so they can remind us all of their major brands:

While many of these are well-known names, it is only relaly oral health that is doing well.
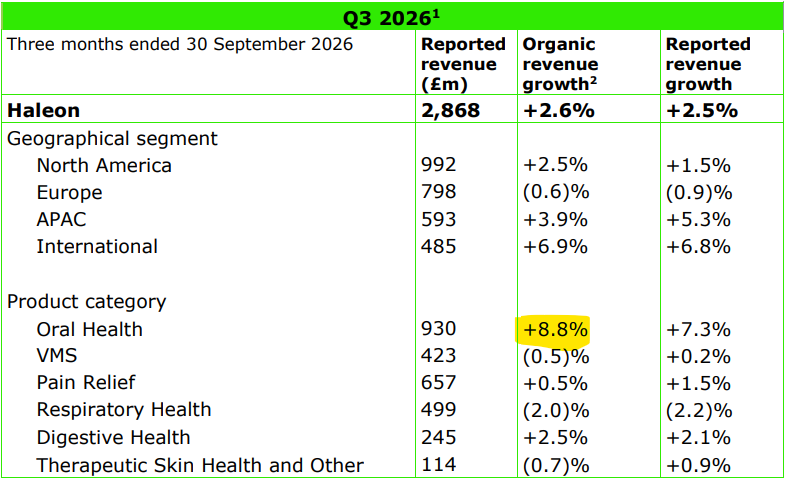
It quickly becomes clear that the overall performance is disappointing:
Our third quarter organic revenue growth of 2.6% was below our expectations as we navigated softness across some of our categories including weaker cough, cold and flu consumption. We delivered strong performances in Oral Health and our turnaround plan in North America continues to make progress. We are clear on where we need to improve and we are taking action to deliver stronger performance despite challenging markets.
The new guidance is:
As a result, the Group now expects for FY 2026:
• Organic revenue growth to be around 2.5%
• High-single digit adjusted operating profit growth at constant currency
• Net interest c.£255m; Adjusted effective tax rate c.24.5%
Previously, they had said that organic revenue growth was expected to be in the range of 3-5%. However, they maintain their adjusted operating profit growth figure. It is not entirely clear how they'll achieve this, and the market clearly doubts it, as the share price is down around 15% today. I can't find any broker coverage on Research Tree to see whether brokers are keeping EPS estimates the same.
Valuation:
Despite today's share price fall, and assuming brokers don't trim EPS, the forward P/E is 15, which, while not necessarily expensive, doesn't compare particularly favourably with single-digit profit growth. More worryingly, the company seems intent on buying back more shares at a punchy valuation, with a further £500m allocated to share buybacks today, to be completed by FY results in February. While this may provide some share price support, it may also raise questions about management's capital allocation credentials.
Brands:
Many of the brands are well-known and can provide real competitive advantage. However, I am a little concerned that Pain Relief remains their second biggest category. Most of their medications will be off patent, and generics will be significantly cheaper and use the same formulation. Advil Dual Action (ibuprofen plus paracetamol in one tablet) is probably its most valuable pain patent. A US patent covering the tablet runs until July 2041. However, they largely rely on uninformed consumers not understanding what is in their medications, or preferring one tablet to two. These seem like weak moats to me, and they require continued advertising spend to maintain at all.
Stock Rank:
The algos rate this as a high flyer, but looking at the individual ranks, I think this designation will be borderline
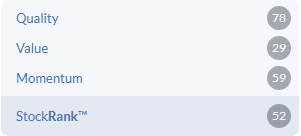
It is also unlikely to survive today's 15% decline in share price, making the overall Stock Rank uninspiring.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on HALEON (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?