Hostelworld: the cheapest social network on the stock market

In this week’s Stock Pitch, I take a look at what looks like a small online travel agent - but in reality may be a very cheap social network contained within a successful online business.
Disclosure: at the time of publication, Graham has a long position in HSW.
Share price at the time of publication: 100.3p
Market cap: £125m
The Pitch
Hostelworld (LON:HSW) has a number of unique assets in the travel universe:
A focus on budget accommodation. This small niche, combined with its distinctive brand name, is the basis of its competitive moat.
A burgeoning social network uniquely suited to solo travellers, with over 3 million registered members.
A global event diary launching later this year.
The company was founded in 1999 in Ireland. It is credited with revolutionising the hostel industry by taking it online for the first time.
By 2009, it had been snapped up by a major private equity firm for c. €230m (£200m) - an impressive figure, especially when set against the company’s current market cap.
In 2015, it listed on the LSE. But its life as a listed company has been difficult, especially during the barren years of the Covid era.
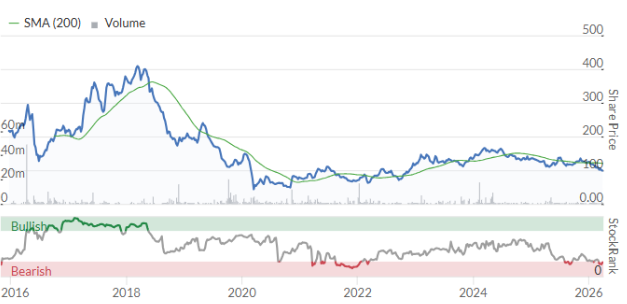
It found itself over-leveraged, and the share price has been in the doldrums ever since:
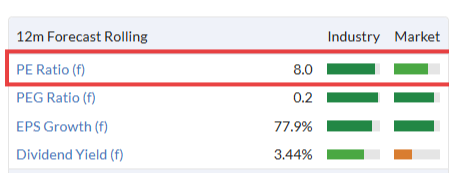
This lack of share price progress has seen the P/E multiple collapse to single digits:
How tough is the competition really?
Now you might argue: why take a chance on Hostelworld when shares in the highly reputable Booking Holdings (NSQ:BKNG) are available at 15x earnings? That sort of valuation is hardly prohibitive.
Indeed, Booking.com is an enormous competitor, and it too offers a very wide selection of hostels.
I randomly selected one night in Bangkok, in order to compare the offerings at each site. Booking.com actually offered more properties in the “Hostels” category than were available on Hostelworld.
However, the gap wasn’t huge (340 for Booking.com against 260 for Hostelworld), and an argument could be had around how many of Booking.com’s choices would truly qualify as hostels.
Whatever the truth of that may be, let’s take it as read that Booking.com is an extremely tough competitor. But who else is there competing with Hostelworld?
hostels.com? Not a problem - it was bought out by Hostelworld.
hostelbookers.com? Also no problem, as it was bought out by Hostelworld.
Expedia? They do offer hostels, but they are more interested in finding higher-spending travellers who will bundle hotel and flight purchases together for convenience. Backpackers don’t exactly fit that profile.
My conclusion? When it comes to the very specific niche of hostels and budget accommodation, Hostelworld has only one truly determined direct competitor.
The Bear Case: Risks to Consider
Booking.com: if the major competitor decided to invest heavily in the hostel sector, it could make life much more difficult for Hostelworld.
AI risk: online platform businesses are generally thought to be at risk of disruption from AI, although I do not yet see any immediate threat of disintermediation.
Execution risk: the development of Hostelworld’s social network could prove to be a surprisingly risky venture. There is no social network in history that has succeeded without controversy - and I don’t see how Hostelworld would be able to reliably police any bad behaviour from its members.
The Bottom Line
Hostelworld offers an interesting opportunity for investors at the current valuation.
In my experience, it’s rare to find a profitable online business, with reasonable growth prospects and a successful niche, trading at a single-digit earnings multiple.
Revenues grew 2% in 2025 and are forecast to grow by more than 10% in 2026.
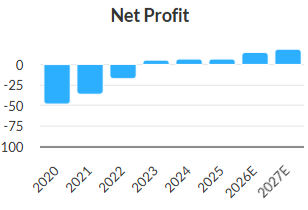
Consensus forecasts suggest that this revenue growth will drop down rapidly into net income. Adjusted profit after tax is forecast to more than double to c. €19m (for context, the market cap is equivalent to €144m).
And there are currently no balance sheet worries: the company reported an immaterial net debt position of <€2m as of December 2025.
So I think now might be the right time to take Hostelworld seriously. It might not be long before the perception around it changes - from an ordinary online travel agent to a scalable growth opportunity.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
What's the basis for the better revenue growth in 2026 when 2025 growth was below inflation? And when a few travel companies are reporting mixed or lower booking data right now.
I would be more worried about AI disruption for a platform like this - it's just a booking website and okay a social networking site which might improve customer loyalty. But I would have thought travel agents offering package holidays, able to provide cut price deals, like On Beach group (LON:OTB) would be a safer bet and some, like OTB, also look good value.
Having worked in the travel industry (and still do) for some time, here are my thoughts on Hostelworld. I do have it on my watchlist but never held.
Is Trump International Travel Services a competitor for that backpacking market with accommodation and flight packages to beautiful places ( Venezuela) and culturally iconic destinations (Iran) with potentially Taiwan in the medium term. Or irony apart, is this not a big bear threat to the global nature of the business / network?
Graham you're supposed to be asleep at 5am!!
I scheduled it last night ;)
Ah, cunning. I can stop worrying about you now....
Current oil prices and really high flight prices won't be helping them either. If this carries on for 6 months it will have quite effect on young people's travel.
AirBnB is also a competitor in some markets. Double rooms are often cheaper than 2 dorm beds.
It would depend on the kind of experience the traveler might be looking for. Having travelled recently for over a month to Thailand, I saw several hostels over there, and they looked more like a gathering place for meeting new friends than just a place to sleep. AirBnB wouldn’t be a competitor for backpackers looking for this kind of environment
I have just been to Vietnam and Thailand. I know what you mean. But people now are using AirBnB more now, also when they have done hostels for a while, they don't want experience that anymore. Guesthouses you can still meet people but have a private room.
I find Thailand hostels expensive. Vietnam are far cheaper.
A momentum rank and stock rank of 22 are not exactly encouraging signals.