How contrarians beat the market by investing where others fear to tread

When share prices fell sharply after the EU referendum, it was a reminder of how fear and panic can spread like wildfire through the stock market. In hindsight, that sudden price rout already looks like an trivial blip. Yet for many, it was a gut-wrenching moment of confusion when the outlook turned deeply uncertain. For others, though, it was a chance to pounce. It was a green light to contrarians who were fully signed up to Baron Rothschild’s advice that “the time to buy is when there's blood in the streets”. So what is it that separates contrarians from the stampeding masses?
On paper, contrarianism - or, going against the herd - is a simple and effective tactic in investing. But in practice it’s a discipline completely at odds with how most of us are wired up.
Following Warren Buffett’s advice of being greedy when others are fearful could have netted super gains in the weeks after the Brexit vote. Even more so if you’d been minded to buy shares when markets hit rock-bottom in the years after the dotcom crash (2003) and the financial crisis (2009). Back then stocks were deeply unpopular, leaving shattered investors nursing losses on the sidelines just as prices kicked off multi-year bull runs. But even in bullish conditions, some stocks and sectors fall well out of favour with the market - becoming no-go zones to all but the steeliest value hunters (banking shares since 2009 have been a good example).
Contrarian psychology
There are some very good reasons why investors find contrarianism such a tough ask. Evidence shows that when faced with what could be bad news for our investments, it’s much more instinctive to crawl under a rock.
One research study called The ostrich effect: Selective attention to information, looked at how often individuals logged into their investment accounts during times of good and bad news in the market. In periods when there was bad news around, people were less likely to view their accounts. But in periods of good news, they were much keener to login, presumably to bask in the glow of rising prices in their portfolios. It was evidence that the average investor naturally looks away in difficult conditions - quite the opposite from what a contrarian investor would do.
Against the herd
It’s easy to pick holes in instincts that are the culmination of several billion years of evolution, but it’s worth mentioning that herd behaviour exists for good reasons. Like animals, birds and fish, the pack-like tendencies in humans have, at times in the past, made the difference between eating and being eaten. So on some occasions, contrarianism can be foolhardy. Michael Mauboussin, a respected equity strategist and behavioural finance specialist, puts it like this: “If you’re in a movie theatre that catches on fire, you’d be best served to run out of the theatre in contrast to the contrarian tack to run into the theatre.”
Unfortunately, academics generally agree that herding instinct doesn’t transfer easily to investing. In fact, it’s actually been blamed as a reason why price bubbles and crashes emerge in the stock market. The antidote, as Mauboussin explains in his latest research note, is to recognise that “great investors don’t get sucked into the vortex of influence. This requires the trait of not caring what others think of you, which is not natural for humans.”
The agony of being a contrarian
So bearing in mind that contrarianism is not without risk, what should a contrarian investor focus on? For Mauboussin, the answer lies simply in distinguishing between the fundamentals of the situation (like the fundamentals of a stock) and the expectations reflected in the asset price (ie. its share price). He sees failing to make that distinction as being one of the biggest errors in the investment business.
Mauboussin is not alone. Take David Dreman, an American investor famous for his value-focused contrarian strategies. In his book, Contrarian Investment Strategies: The Psychological Edge, Dreman notes that “favored stocks underperform the market, while out-of-favor companies outperform the market, but the reappraisal often happens slowly, even glacially.”
Yet despite the challenges faced by contrarians, Dreman insists it’s worth the wait. He says that the re-evaluation process, which is heavily influenced by investor behaviour, is the key to large and consistent profits in the marketplace. “As long as investors believe they can pinpoint the future of favored and out-of-favor stocks, you should be able to make good returns on contrarian strategies.”
Contrarian strategies
The underlying message here is that buying cheap, out of favour assets is a strategy that can have periods of slow performance, but it can be very successful. That’s broadly what we’ve seen in the four Dreman-inspired investment strategies that we track at Stockopedia (which you can find here), as well as others like the Sir John Templeton Bargain screen here.
This chart shows the four and half year performance of the Dreman Price-to-Cash Flow strategy. It did very well through 2012 and 2013 but it drifted in early 2014 and had a poor year in 2015 - which was fairly typical for many value strategies. It has managed a 20.8% gain over the past two years, although the number of companies passing the rules can dry up in bullish conditions. It has come back reasonably well after the EU referendum and the portfolio will be refreshed at the end of September.
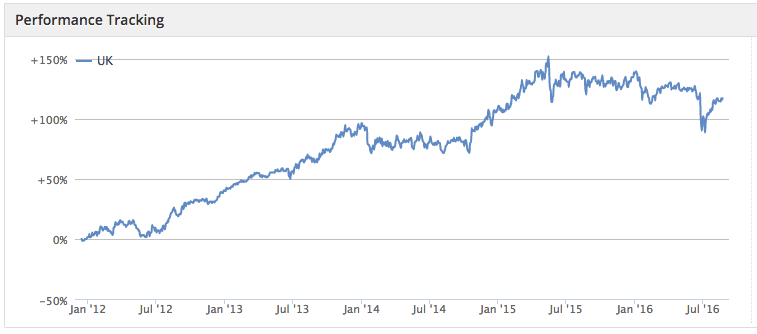
Another way of developing a rules-based contrarian strategy is to look for stocks with the best combination of strong quality and attractive value using the StockRanks. We wrote about this strategy late last year, and once again its performance has seen periods of very strong gains punctuated by periods of drift.
If you want to explore this further, you can see the QV rankings in the StockRanks portal here. We’ve also got a pre-built Contrarians screen here, which again focuses on high quality, attractive value and poor momentum - as it seeks to go against the herd.
Whether it’s in fleeting market chaos, the dying days of a bear market, or one or two embattled stocks or sectors, being a contrarian means having the mental strength to ignore the crowd. In essence, value investing is about recognising when the fundamentals of a stock have been priced wrongly by the market. Take that a step further, and being a contrarian is about having the psychological strength to do something about it. As Michael Mauboussin puts it: “The crowd is often right, but when it is wrong you need the psychological fortitude to go against the grain.”
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Hindsight is so wonderful that it makes experts of us all. The brexit plunge was so short as to be meaningless in the overall market progression and who says it's over? So you buy on the falls, that's Ok but you then have to suffer the bigger falls and providing you have the temperament no problem. If one looks at the progress of many of the pre brexit darlings they will find many who's recovery has been far from great. A man got into a lift and was asked how his portfolio was doing, making a fortune he said , how was it before you got into the lift said the enquirer.
Agreed mb
Human nature places weight on what happened (the 'outcome bias') and neglects what didn't happen... regardless of the probabilities involved.
Investing is as much a study of psychology as economics
Obviously, the end of June turned out to be a great time to buy, but buying on market dips does not always pay-off.
In March 2001, the FTSE dipped and then recovered briefly, but then dropped a further 35% over the next two years. It did not hit March 2001 levels again until November 2005. There was almost an action replay starting in March 2008 and falling by a similar amount then consolidating back above March 2008 levels two and a half years later. A contrarian strategy can pay off, but sometimes you’re just catching the falling knife.
The market reaction in the immediate aftermath of Brexit was rational given the level of uncertainty at the time. The strong recovery since can be largely credited to circumstances which saw political stability reestablished more quickly than anyone could have predicted. If things had gone to script David Cameron would still be prime minister with May and Leadsom still battling it out to succeed him. Under this scenario, the current market outlook could be looking very different indeed.
I am now a contrarian.
Over the years I have tried most systems, including WD Gann.
Unless you have nothing else to do active stock dealing is a relentless task.
Stop losses are great in principal but there is always the doubt that the time is not quite right.
I now buy on reverses in conjunction with Updata point and figure charts, Stockopedia and Investors Chronicle general information supported by a good and hopefully reliable dividend.
I only sell on a long loss situation that I give up on. Regardless of cost.
I did have a spell spread betting, but the ups and downs were going to drive me to an early grave.
I am now happy. I beat the indexes most years but I will never make a fortune.
I leave that to younger dreamers.
A contrarian approach is much easier said than done as is true with people who go on about `value`
.I am not sure either is compatible with a stop loss approach.
I run 2 portfolios:1 a momentum one which I look at every week and has built in stop losses and a mixture of dividend paying out of favour stocks with sometimes out of favour themes which I look at once a year
Barring Black Swan events the momentum has overperformed most of the time however momentum stocks are far more vulnerable in volatile times.
I think that "a rules-based contrarian approach" isn't really contrarian.
Absolutely, a focus on the reality and the ability to stay calm while all around are losing their minds can be helped by following some rules, but my contrarian streak isn't going to be happy following rules, or at least not continually challenging them. True contrarianism requires a psychological element of the outsider or even predator.
There's another aspect to this that matters and that is being well prepared for the opportunity.
By that, I mean having thoroughly researched a small number of stocks and having them
on a wait-list, together with target buying prices. These would be stocks that would be
likely to benefit from the supposedly shock event that would perhaps happen. In the case
of the 23/6 referendum, I had listed ITV (LON:ITV), the housebuilders, Ibstock (LON:IBST), Paysafe (LON:PAYS) and one or two others which would do well either way, whatever the outcome of the referendum. The sharp downturn from 24/6 onwards was a great opportunity to pick up some bargains. Another aspect is, of course, to have cash to buy. I was almost 50% in cash on 23/6. Had the event gone the other way, then no problem, there will always be other opportunities, cash is cash, patience always pays.