How to sleuth for a data-driven edge in gaming companies

I like simple rules. But I especially like a quantifiable edge. The StockRanks give me that, and I’ve happily invested with them for a decade. When you know your odds, it makes decision making easy. If I buy ten 90+ ranked shares, six have on average been winners, and the winners gain more than the losers lose. It varies year to year, but the impact compounds wonderfully through time.
But I know private investors, and I know myself. 10% per year isn’t enough. We want more. We want 20%. We want 50%. We want multibaggers. But herein lies a problem. In reaching for returns, we step into more speculative territory. We get drawn into late-stage narratives. We start to lose our edge.
Now I’ve learnt through a lot of pain, that narrative-based investing isn’t good for me. But statistics, I know I can back. And occasionally, you can find a statistical edge in unlikely data sources. If you can match an edge with a story - that’s where the really good returns lie.
This year, I’ve found overlooked anomalies in a pair of UK gaming stocks - Trufin and Frontier Developments. While the early, easy gains may already be made, I want to share the process I’ve used to gain a small edge, as readers may be able to learn from it.
A conversation with Mark Simpson reminded me of his excellent piece, Sleuthing Your Way to an Informational Edge. He makes the case for using Google Trends as a research tool. This has now become one of my favourite sources of “weird data alpha” - particularly in small caps. What follows is how these sources have helped build conviction in two discretionary positions this year.
Case 1: Balatro drives Trufin gains
Flying back from Australia at Christmas, I noticed my eldest son, now 21, wasn’t watching movies. He was glued to a game on his iPhone. He introduced me to Balatro. While killing time in Dubai airport, I downloaded it… and promptly played for eight straight hours until my eyes nearly bled. It’s hard to describe - a mashup of poker, deck-building games and trippy psychedelia. Try it, and you’ll be hooked.
A few weeks later, I was analysing how “significantly ahead of expectations” trading statements drive future returns. Among January’s positive announcements, one name stood out: “Trufin”. I’d never heard of it. Then I read the RNS. I couldn’t believe my eyes. They were the company that owned Balatro.
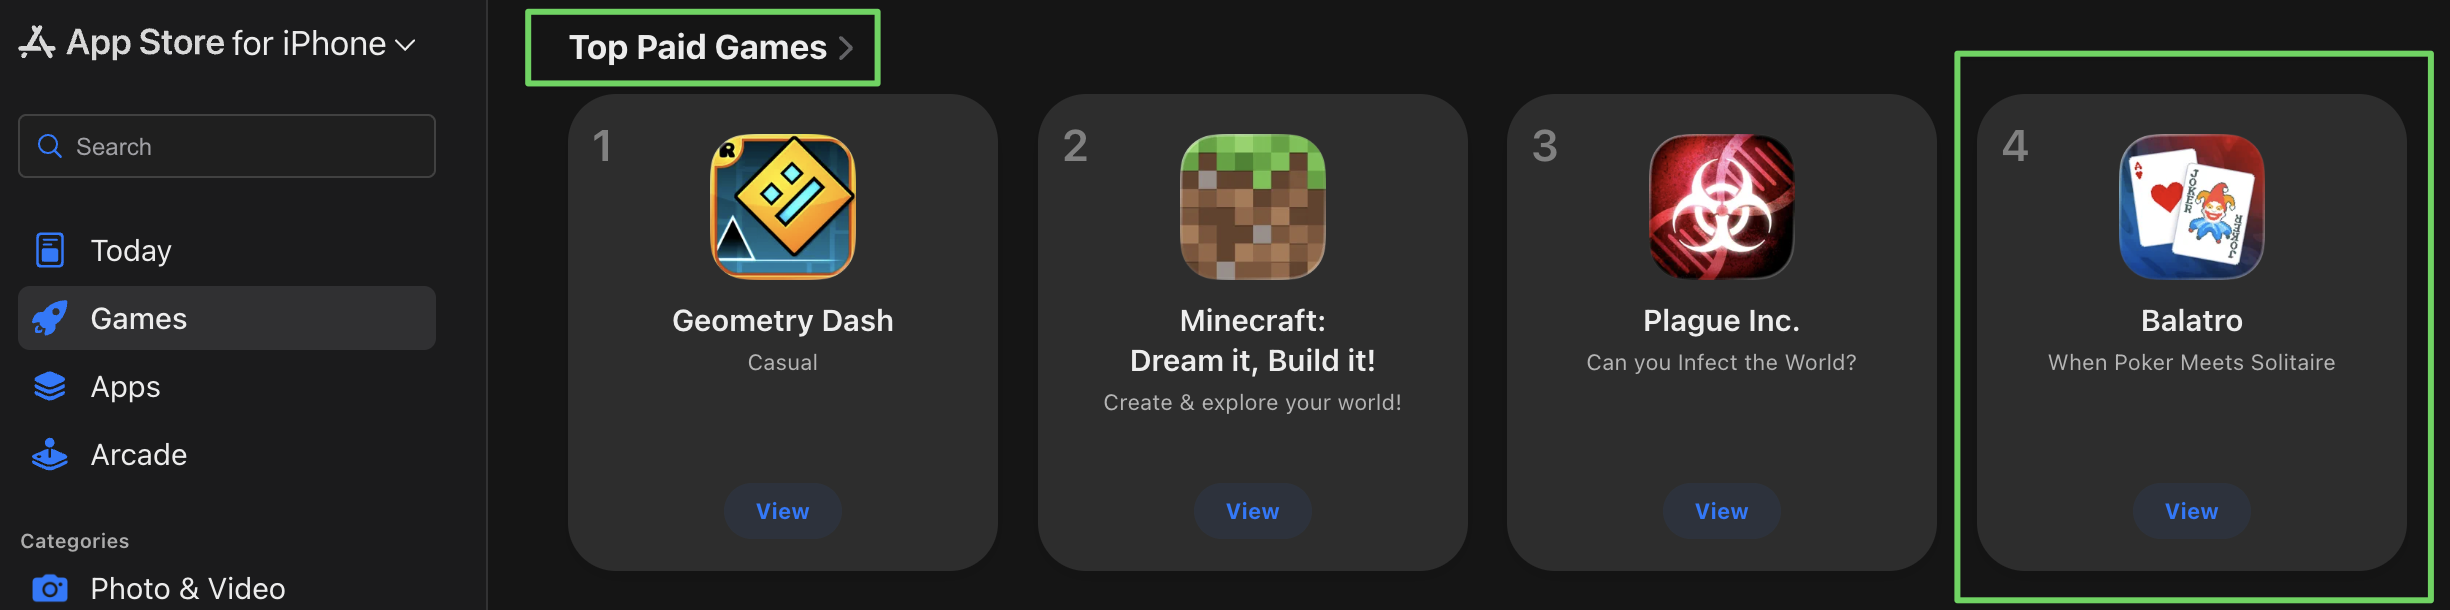
A quick look at the App Store showed Balatro at #1. It had just scooped multiple Apple end-of-year awards. Trufin explicitly said the game was powering their profits. Sure, it was “just one game,” but what a game.
The investor community tends to read RNSs. They rarely buy the product. Many gave up gaming in their 20s. But here was a game I’d been personally addicted to - selling like hotcakes - and driving outsized profits at a tiny UK small cap.
I checked the broker notes. They assumed Balatro’s impact would fall precipitously. But a glance at Google Search Trends showed the exact opposite.
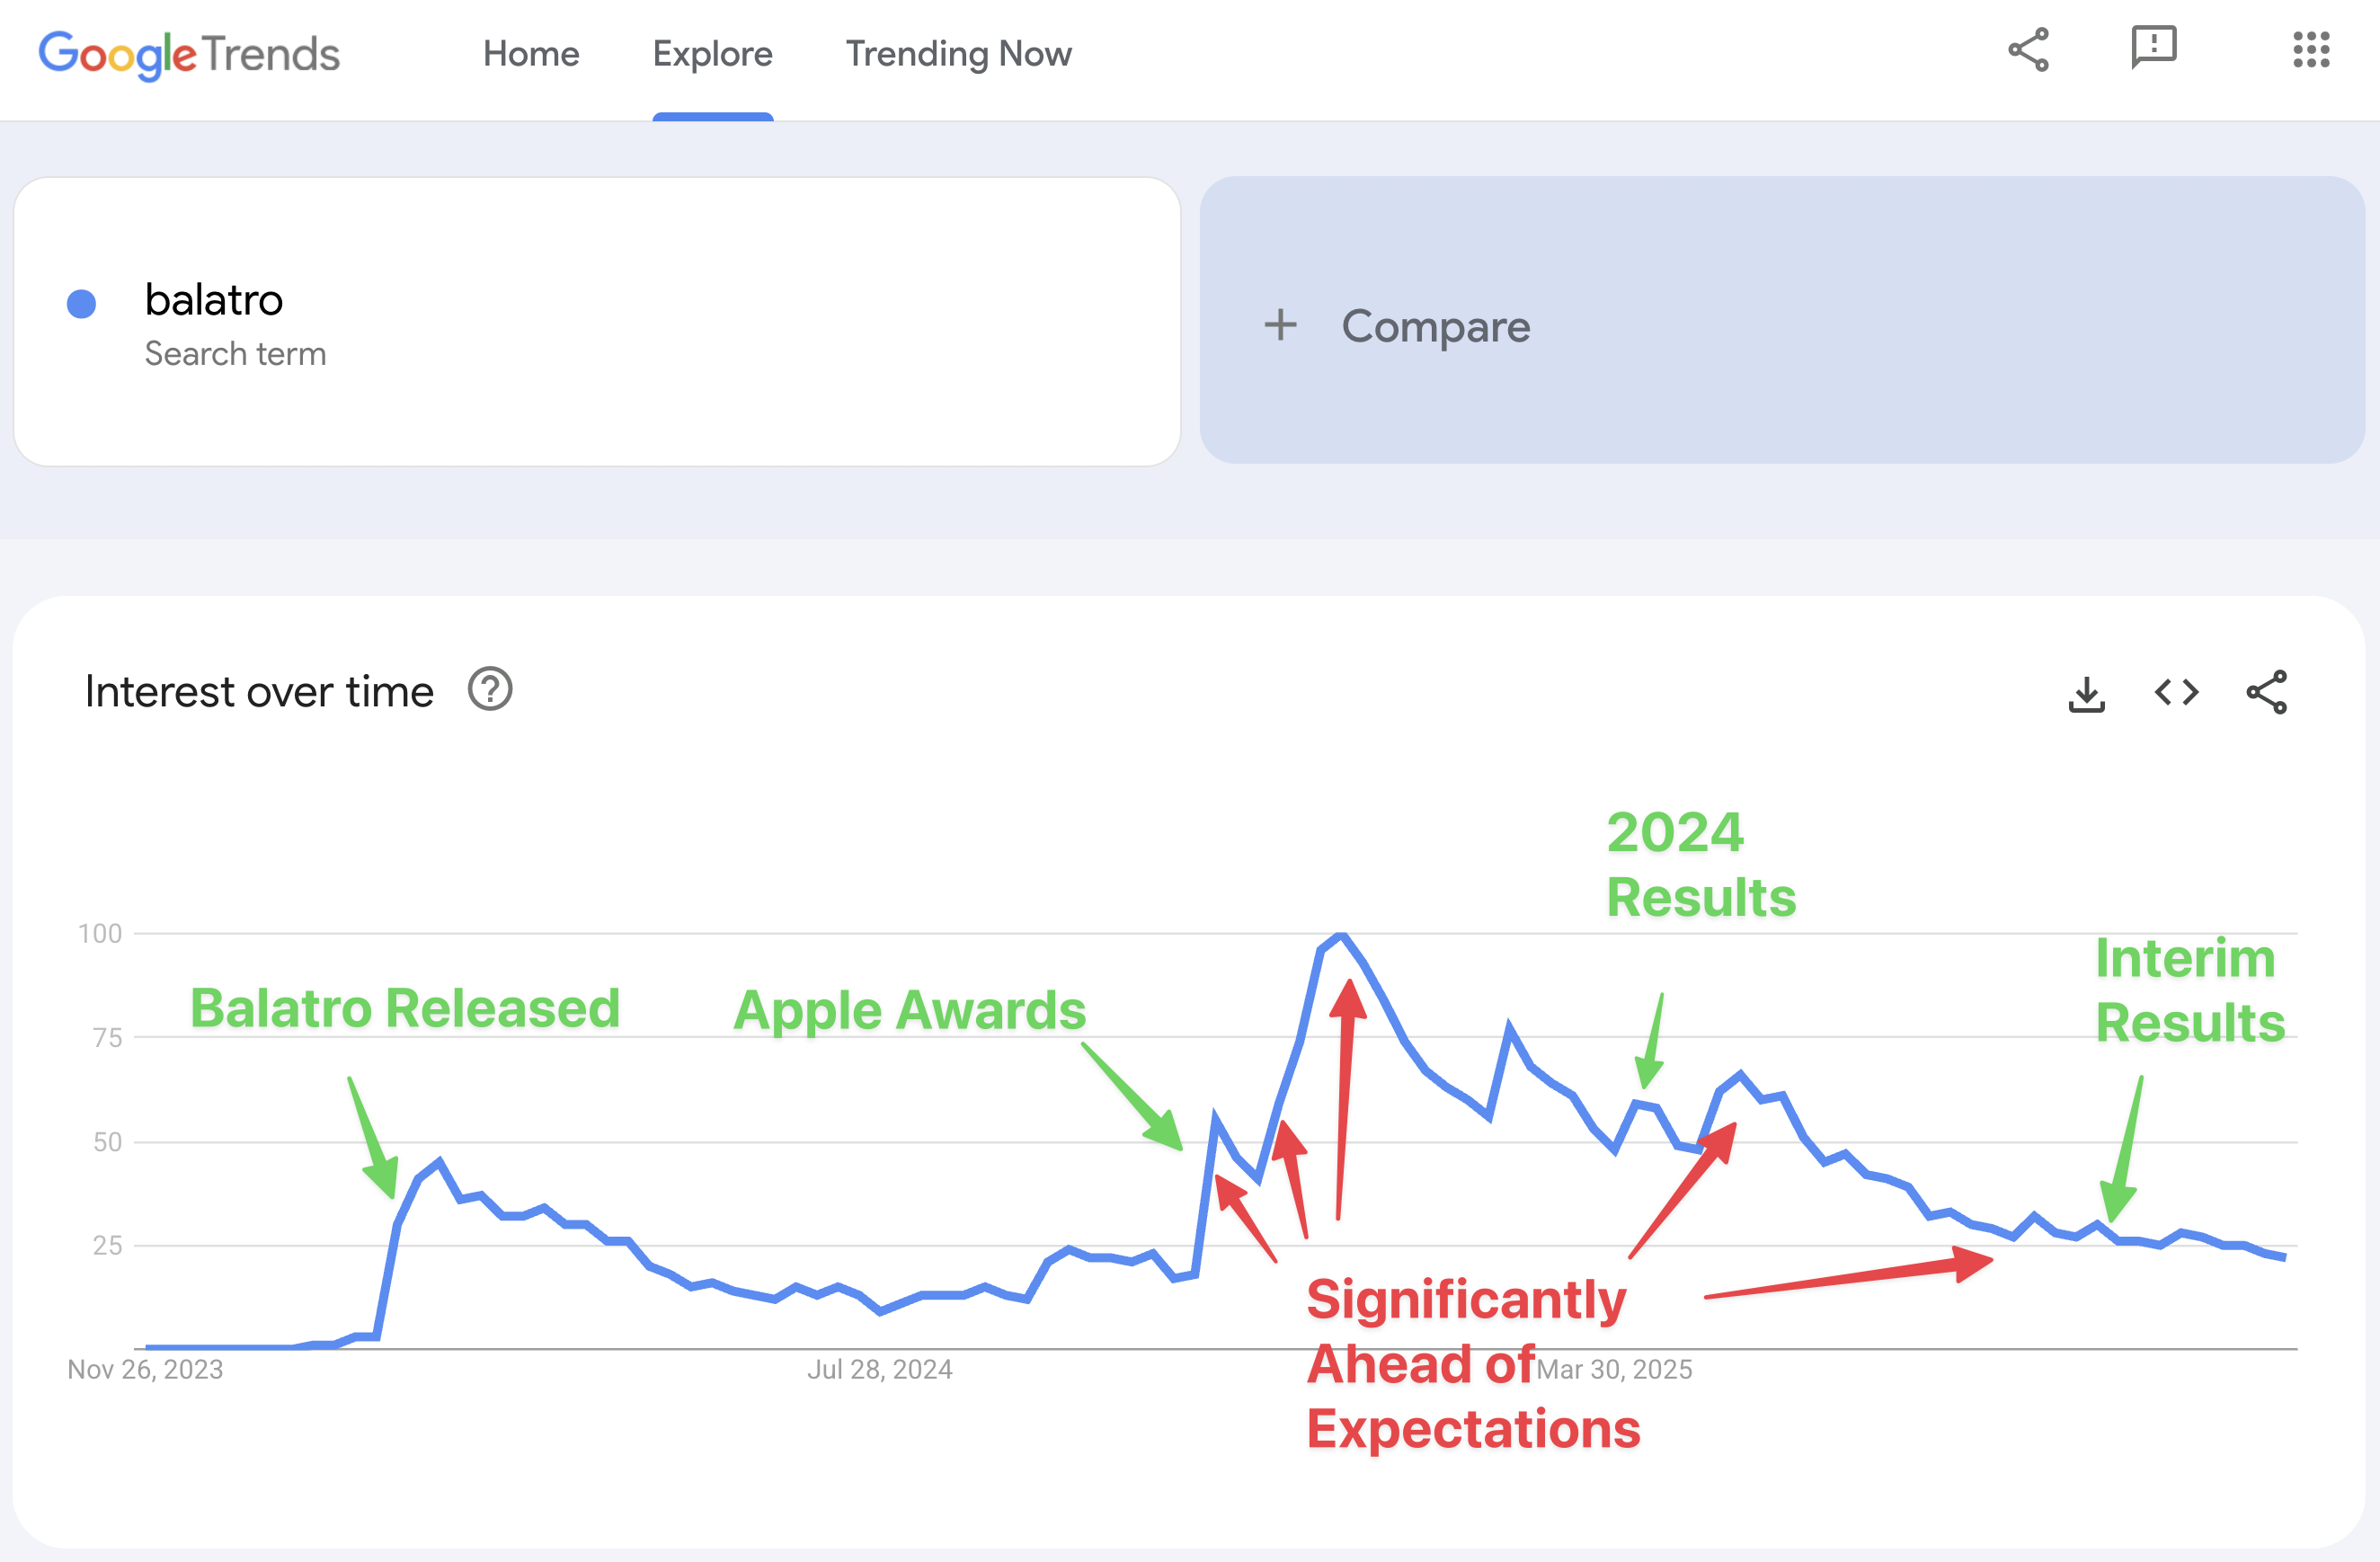
The number of searches for Balatro had rocketed. Sales weren’t declining. Trufin had already announced “significantly ahead” no less than three times in a row - November 18th, December 5th, and January 6th. It’s March results were impressive, but the brokerage community was still discounting a rapid decline in sales.
But March and April search numbers were high, and Balatro remained #1 in the App Store. You can download the data from Google Trends and make revenue assumptions - it was clear in March, that the revenues would continue into FY 2025 at the same run rate. Trufin was likely to announce “significantly ahead” again.
The stock is up 40% since after another two “materially ahead” announcements. Yes the Balatro search numbers are declining and it’s now dipped to #4 in the App Store charts - but the numbers are still far higher than the average all through 2024 - and there’s a non-zero chance this indie hit is becoming a long-term gaming fixture, like Minecraft which sits at #2.
Case 2: Frontier Developments goes all Jurassic
I’m largely a Value/Momentum investor, and nothing delights me more than seeing a “bowl”. A multi-year long chart decline followed by a sharp share price upturn, rising profits, and breakout news. Even better if the StockRank is 95+. Frontier Developments checked every box. They were a huge NAPS winner in 2020, and they created Elite - a game I loved as a kid.
After a rough patch with F1 Manager, the share price tanked, but Frontier restructured to focus on CMS (creative management simulation) games. Essentially, gamers can addictively build Jurassic Parks, Zoos, or Theme parks across their core titles.
But so much was riding on one big launch this year. Jurassic World Evolution 3 (JWE3). JWE1 was a breakout hit in 2018. JWE2 performed well. But could they do it again?
The game launched on October 21st. Reviews were positive. It shot straight to the top of Steam. That de-risked investment - but could it meaningfully move the needle for the business?
Well that’s where some triangulation could help.
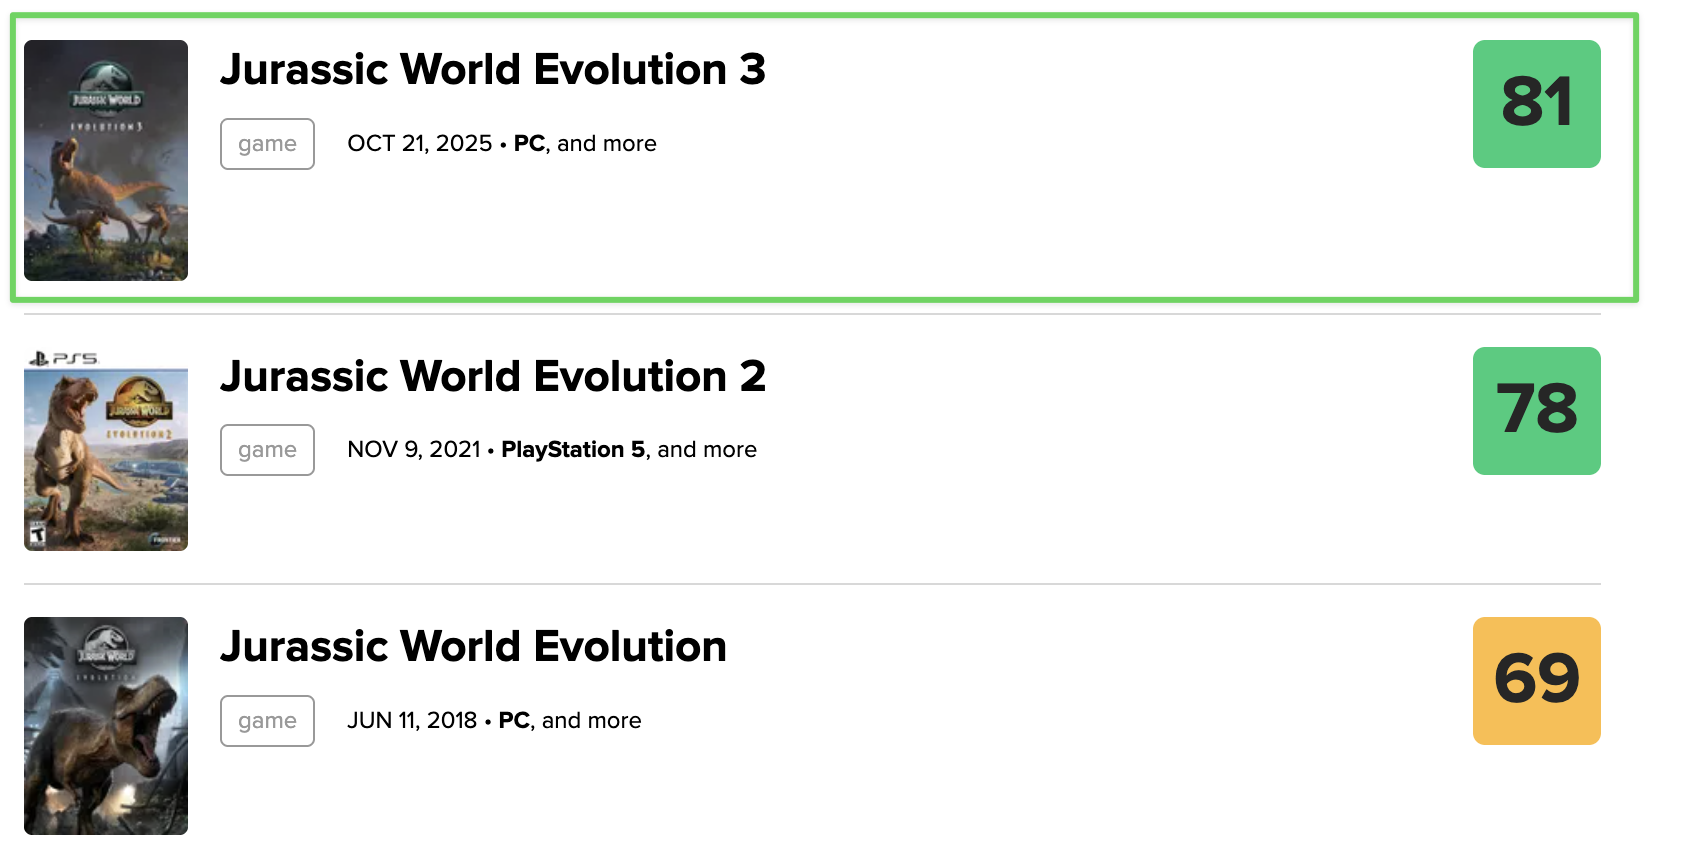
Firstly - Metacritic Reviews. Metacritic is a review aggregation website - and JWE3 is rated higher at 81 than both JWE2 and JWE1 by critics, and has a “Universal Acclaim” rating of 9.0 for its User Score - far higher than either.
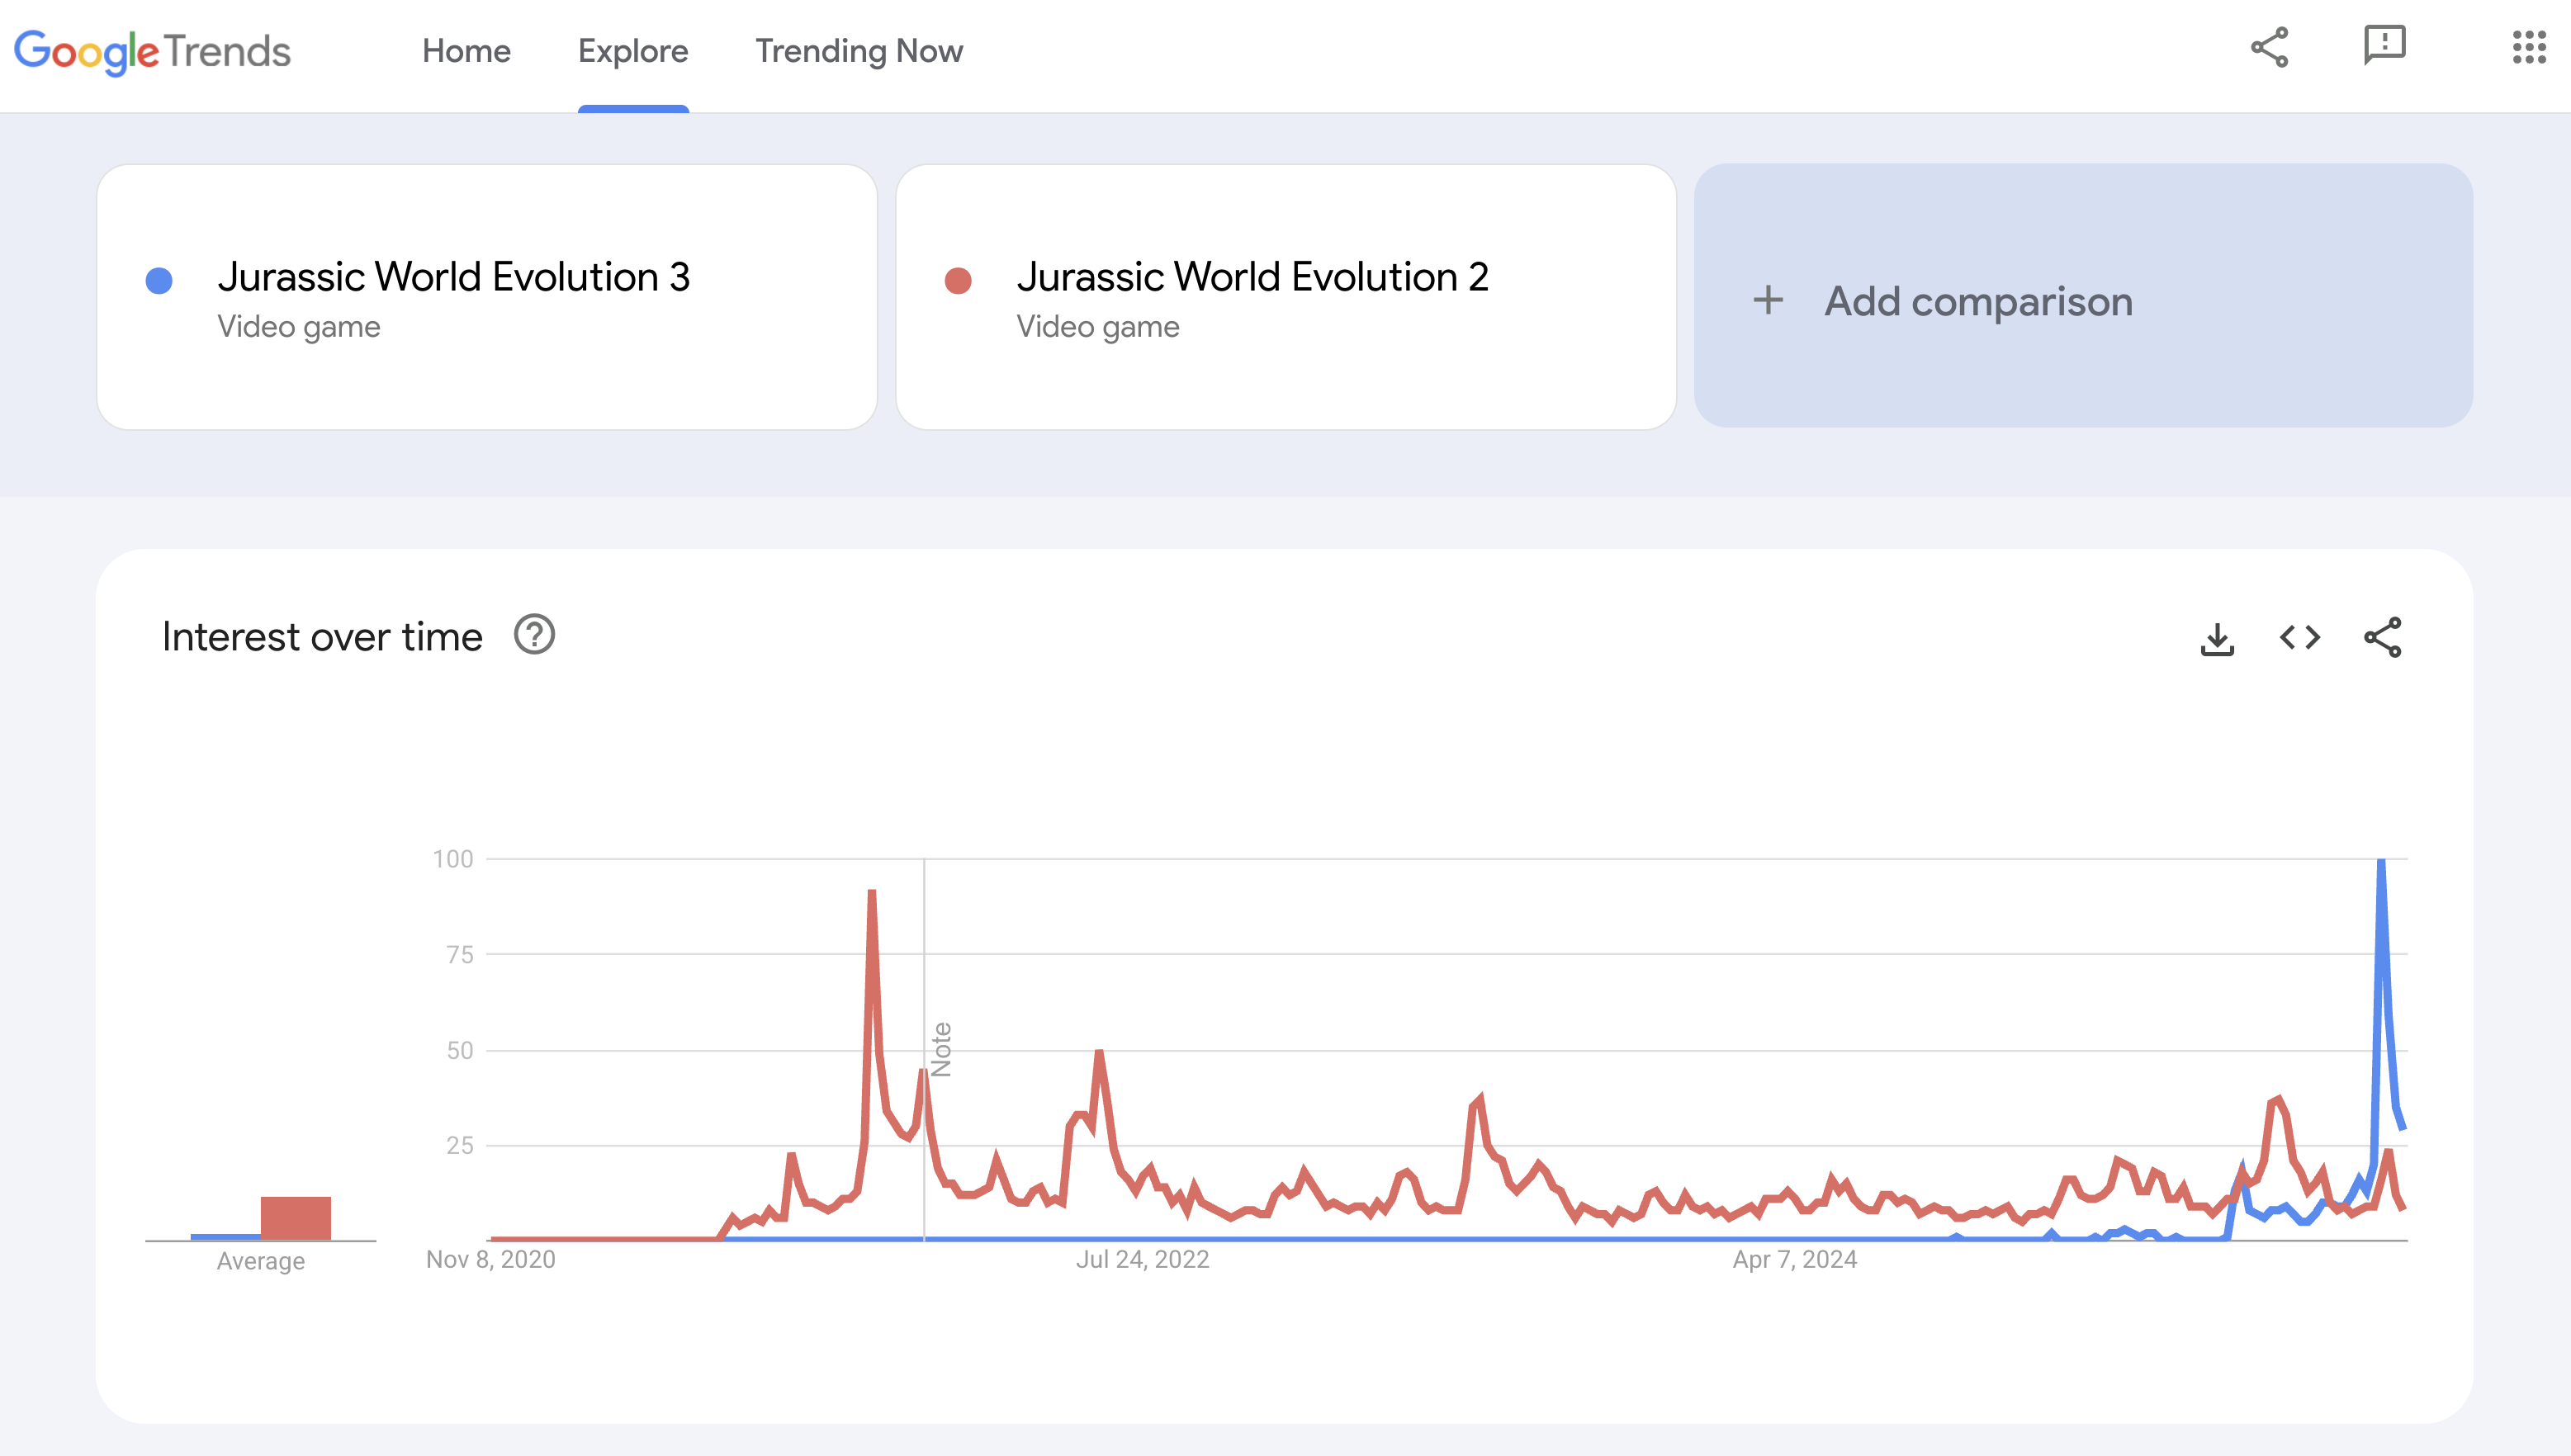
Secondly - Google Search Trends. JWE3 is tracking 10% above in search volume than JWE2 in the UK and matching JWE2 globally. You can download the data and compare the launch dates in a Google Sheet.
Thirdly - SteamDBInfo. This seems a bit obscure, but it’s gold. This is an actual database tracking real user game usage on the Steam platform. JWE3 is tracking at least 10% higher in terms of real user usage when the charts are aligned to release dates.
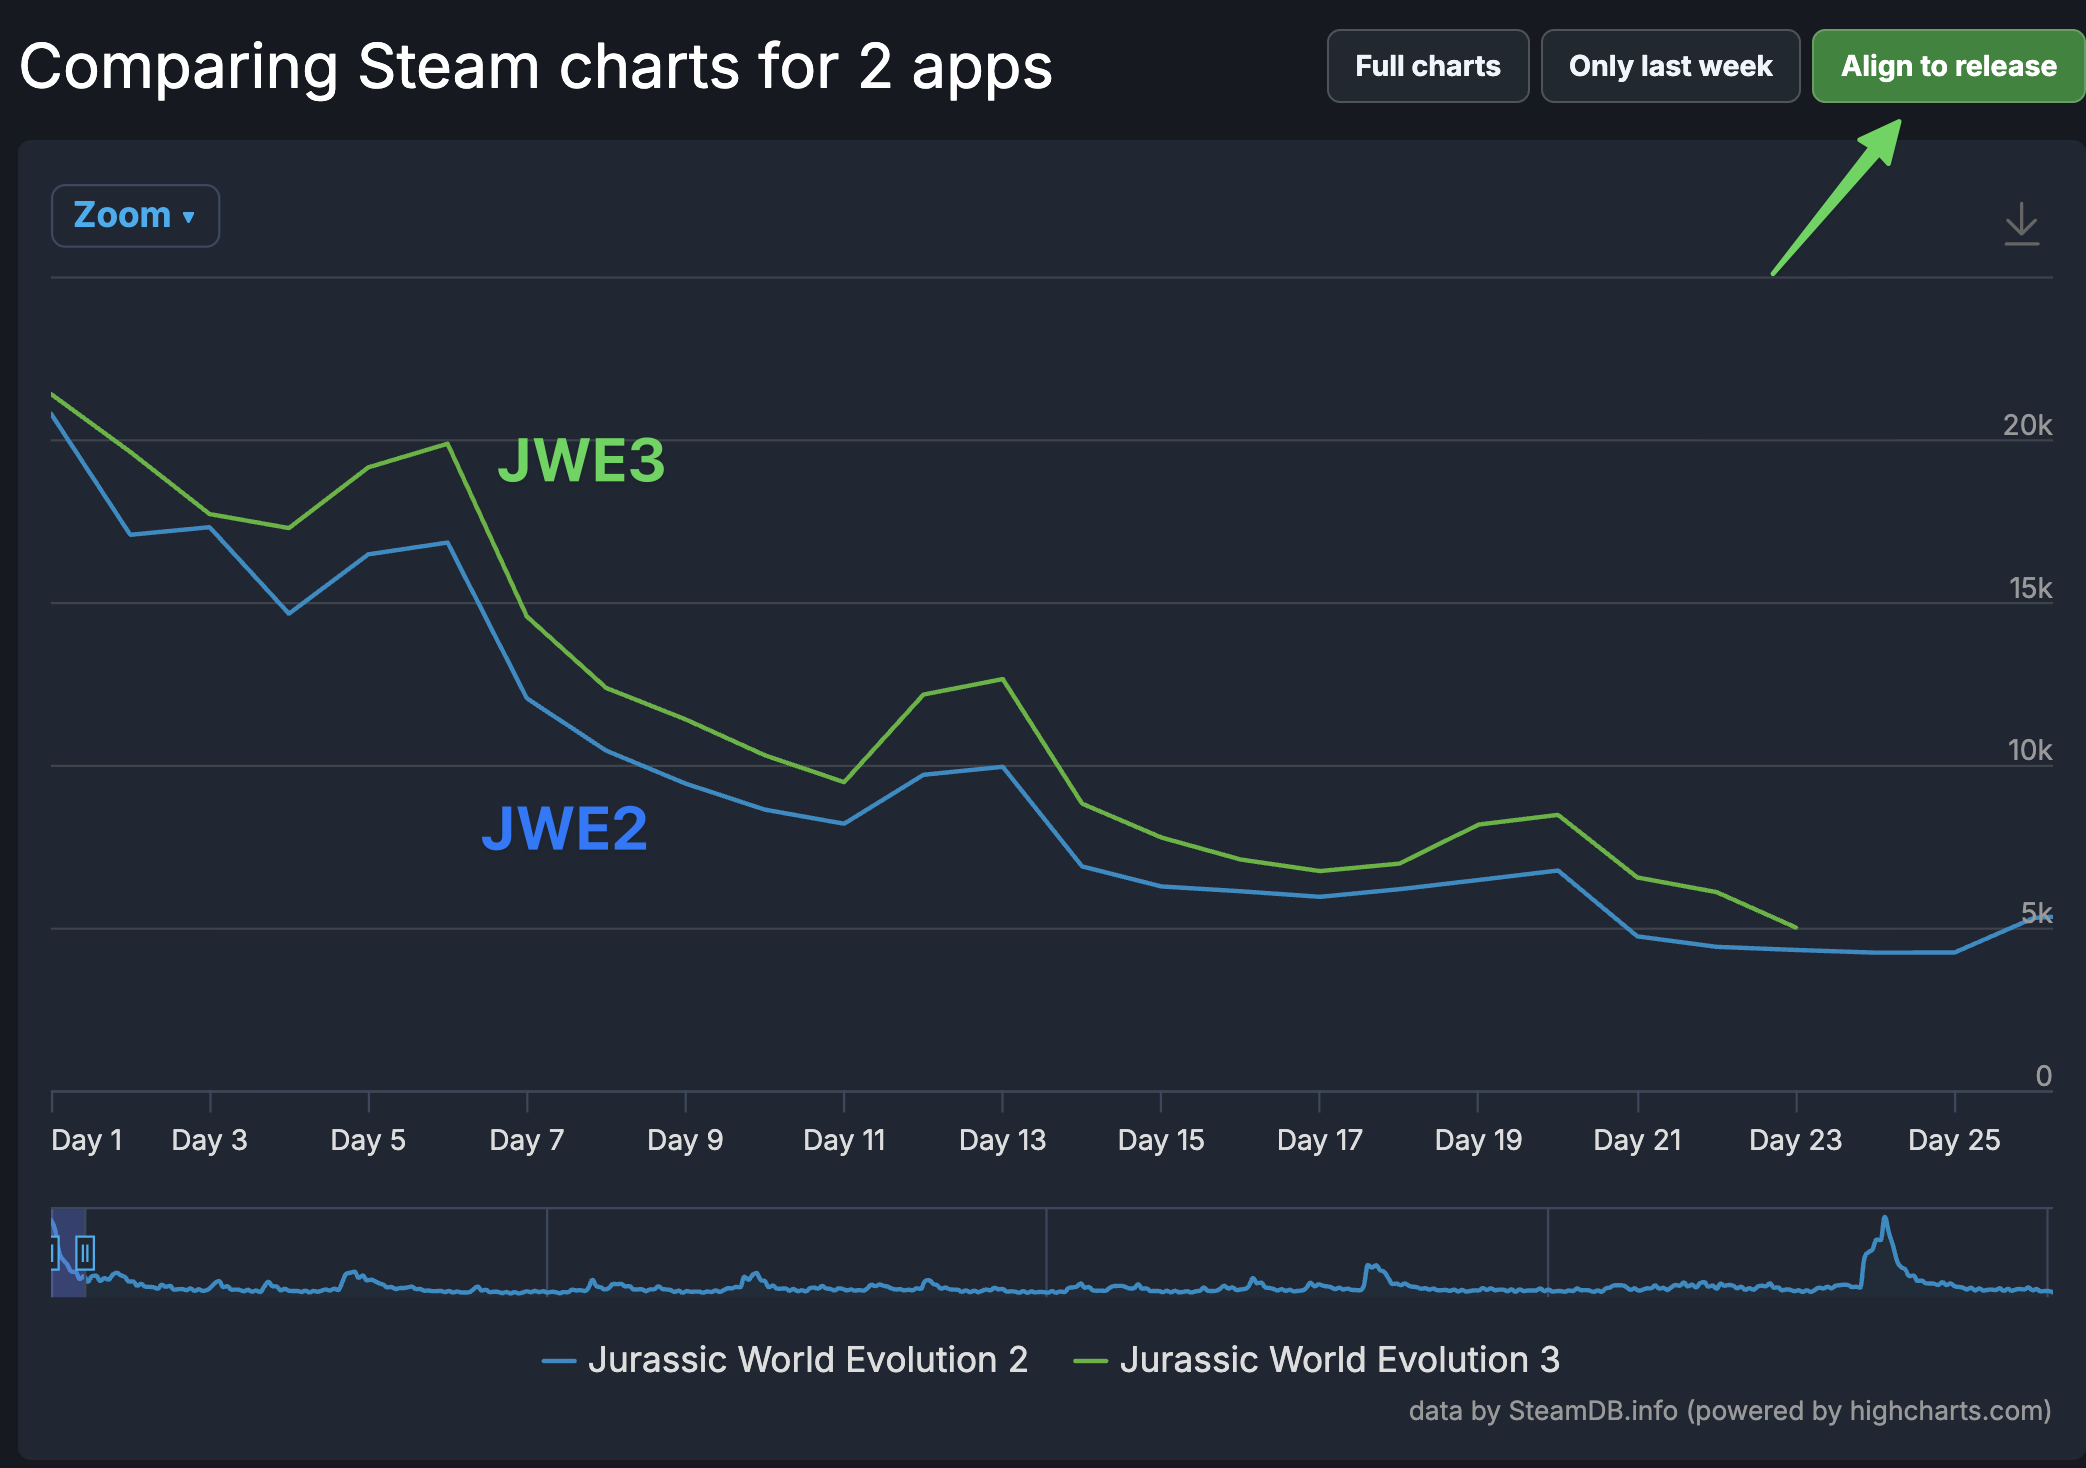
It was clear, even after a week that the game was performing as well or even better than its previous release, which was a big revenue driver for the business.
But the brokers have been overly cautious. This note from Zeus from the month before the release is telling about how low expectations have been.
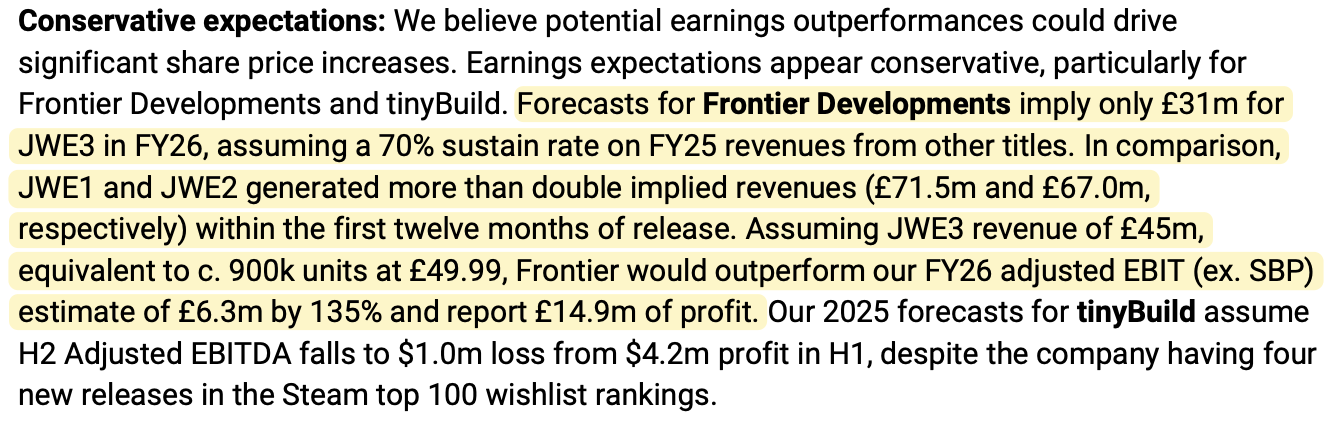
It came as little surprise that Frontier Developments rushed out a bullish anouncement - and an earnings upgrade cycle appears likely (even if a lot still depends on a good holiday trading period).
At just over two weeks after release, base game sales have now exceeded 500,000 units, with higher revenue than was achieved by Jurassic World Evolution 2 (Nov'21) in an equivalent period.
Conclusion
Fundamentally, I believe in rules-based investing to counter all kinds of personal biases. But this year, thanks to our research into “ahead of expectations” announcements, I’ve been willing to take selective, higher conviction investments on the discretionary side.
There's extra alpha in small caps if you look beyond the usual data sources. High StockRanks set the base. Positive trading statements can add momentum. But an additional edge can come from sleuthing for signals the market hasn’t priced in.
The gaming sector is perfect for this as there are several sources of alternative data. Google Trends. App Store charts. SteamDB usage. Metacritic comparisons. Niche data sources that reveal what’s actually happening before brokers update their numbers. There are quite a number of small-cap gaming companies listed on both the UK and international markets to which this can be applied.
To be clear, this is about a research process, it is not a set of share recommendations. These kinds of small caps have a heavy dependence on individual titles. You have to watch the data like a hawk. When the numbers turn… it’s far better to sell before a profit warning than after. Caveat emptor!
(The author currently holds position in Trufin and Frontier Developments).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
Update on Frontier Developments (LON:FDEV) - I've been watching the SteamDBInfo for insight into how the post release JWE3 activity is holding up vs JWE2.
As you can see after about 30 days of release, the game has started tracking below JWE2. 2 days ago the first DLC (downloadable content) pack was released for JWE3 (wetlands), and I would have expected a spike upwards in activity. This doesn't seem to have happened.
This is not terminal, but it does moderate the bull case.
So it looks like JWE3 got off to a cracking start... 18% more Steam player usage in the first 30 days than JWE2, but in the second 30 days it's tracking at 73%.
In total, it's 2% higher... but the dropoff after the first month is significant.
How that relates to sales is anyone's guess, but you'd imagine that sales are currently tracking weaker than JWE2 since Day 30. The standard edition I believe was priced the same for both.
Relative performance may depend on the sale period up to end of year and the DLC (downloadable content) releases.
Interesting that the CEO stood down yesterday, and the announcement said their portfolio of games (including JWE3) was "performing well" - though not nearly as bullish as the previous announcement which came 2 weeks after release.
Trufin (LON:TRU) "materially ahead of previously guided market expectations" again today (RNS). Panmure Liberum upgraded their price target from 138p to 173p. It's been a bit of a one game story (Balatro) for some time, but good to see a new release doing well. Not that much market reaction - 2% or so up at the moment.
As you may know, I'm not a big believer in absolute values of broker forecasts/targets etc, but am a believer in "upgrades" as they often reinforce and build trends.
My Frontier Developments (LON:FDEV) AI sleuthing involved feeding Grok with available JWE3 sales data, + my notes and asking it for a 2026 year end share share price projection? Grok suggests a useful upside, awaiting their January interim update....
Grok: Valuation and Price Effect: At a forward P/E of ~17–18x (based on current 530p price and 30p EPS), a 10–20% EPS upgrade could justify a share price of 600–700p by May 2026, aligning with or exceeding high-end targets like Peel Hunt's 620p. Historically, earnings surprises have driven 10–12% price jumps (e.g., post-FY25 results and November update), with momentum adding steady gains. If FY26 results (reported ~June 2026) confirm the beat, this could compound into 15–30% total returns from now.
In essence, this sales trajectory reinforces FDEV's recovery profile, likely boosting the end-FY26 share price toward 600p+ through further analyst upgrades and market catch-up. Monitor the January 2026 interim results for confirmation, as they could catalyze the next leg up.
ChatGPT Deep Research mode is getting good for investment research. Costs a bit, but an enormous time saver.
Here's the top 10 global gaming small caps to research according to ChatGPT - NB some low StockRanks among these - but given my post above, there may be something in here:
1) Frontier Developments (LON:FDEV) – management‑sim specialist; heavy reliance on one PC/console launch each year
Why it fits: concentration on internal sims and licensed Jurassic titles.
Near‑term catalyst: Jurassic World Evolution 3 announced and dated Oct 21, 2025. F1 Manager 2025 was cancelled and the F1 license exited—important for expectation setting.
2) Paradox Interactive AB (publ) (STO:PDX) – grand strategy & Cities; earnings swing with marquee DLC/major franchise beats
Why it fits: big moves around big expansions/flagships despite a portfolio.
Near‑term catalysts: Cities: Skylines II – Bridges & Ports expansion Oct 29, 2025; console version still “not before summer” (ongoing comms), and management flagged work on Europa Universalis V and Vampire: Bloodlines 2 this year.
3) CD Projekt SA (WAR:CDR) – ultra‑concentrated on The Witcher/Cyberpunk
Why it fits: share price is highly sensitive to milestone headlines.
Timeline reality: Witcher 4 (Polaris) won’t arrive before 2027 per company guidance (after 2026), so this is a medium‑term, milestone‑driven trade rather than 2025 launch risk. See H1’25 IR materials for current positioning.
4) Remedy Entertainment Oyj (HEL:REMEDY) – concentrated AAA pipeline
Why it fits: multiple high‑impact, few‑title slate; each title is a needle‑mover.
Upcoming: Max Payne 1&2 Remake and Control 2 are in full production (dates TBD). Management also addressed pipeline and recent performance in Oct’25. Expect 2026+ for major drops.
5) 11 Bit Studios SA (WAR:11B) – small set of prestige AA launches
Why it fits: earnings cluster around launch windows.
2025 beats: The Alters launched Jun 13, 2025; Frostpunk 2 console arrives Sept 18, 2025—console adoption + DLC cadence are the swing factors.
6) Starbreeze AB (STO:STAR B) – single live‑service dependency (PAYDAY)
Why it fits: essentially a one‑franchise company; update cadence shows up in KPIs/revenue.
2025 focus: regained PAYDAY 3 publishing rights and re‑stated the update roadmap—content cadence and quality can drive sharp moves even without a boxed launch.
7) Creepy Jar SA (WAR:CRJ) – “premium indie” with one new IP
Why it fits: Green Hell back catalog + one new IP are the core.
Next beat: StarRupture (renamed from Chimera) Early Access Jan 6, 2026—playtest/wishlist conversion will be key tells into FY26.
8) CI Games SE (WAR:CIG) – sequel‑driven, high concentration
Why it fits: results hinge on one major premium launch at a time.
Next beat: Lords of the Fallen 2 revealed (Gamescom 2025) and slated for 2026; Project Survive 2025 window uncertain.
9) Digital Bros SpA (BIT:DIB) – Kunos’ Assetto Corsa is the engine
Why it fits: the franchise dominates the P&L.
Near‑term catalyst: Assetto Corsa Rally Early Access Nov 13, 2025 (PC). Company H1’25 deck underscores AC’s importance.
10) Dont Nod Entertainment SA (EPA:ALDNE) – few launches, each matters
Why it fits: a couple narrative AAs a year can swing results.
2025 beats: Lost Records: Bloom & Rage released in two parts (Feb 18 & Apr 15); The Lonesome Guild targeted for Oct 23, 2025.
Many thanks for some steadying thoughts on Frontier Developments new game prospects to cheer us in the political quagmire dragging back some remarkable gains lately in my naps based portfolio. To be honest, with the government promising increased housing expenditure and upgrading existing stock, my nerve has shaken slightly and half of the investment I placed in Frontier Developments as a knee jerk to their recent price rise has now been redirected to Northern Bear.