Hunting for an edge: 3 interesting stocks with no broker coverage

We’ve all grown used to using brokers’ consensus earnings estimates to help us quickly assess shares. These forecasts can be useful for a ballpark valuation or as a guide to the near-term outlook – are profits rising or falling?
The problem is that relying on these estimates does not give us an edge. Quite the opposite. All of this information is widely known and is usually already priced into the shares.
To make matters worse, fund managers and other City insiders are likely to have access to more detailed forecasts and analysis than most private investors.
This got me wondering. What if I took the opposite approach and hunted out stocks with no broker coverage?
A lack of coverage is not necessarily a cause for concern. There are legitimate reasons why a company might not have analyst coverage. Common examples are family ownership, small size, or just cost-conscious management.
As a private investor willing to do the research, could I find an edge by focusing on companies of little interest to the City?
A quick screen suggested to me that there are more than 25 UK companies in Stockopedia’s database with a market cap of at least £25m, no broker coverage and a StockRank of at least 50.
I’ve excluded financials (mainly investment trusts) and small-cap miners, as these aren’t likely to have the characteristics I’m looking for.
Here’s a link to the screen I used: Stocks with no coverage

Even more than usual, these screen results are not a list of stocks to buy. Each will require in-depth individual research. But scrolling down the list suggests some interesting possible choices to me.
In the remainder of this article I’ll take a look at three stocks that have caught my eye.
But first, an important health (wealth!) warning.
What could go wrong?
For investors used to trading FTSE 350 shares, there are several potential pitfalls to be wary of in this part of the market.
Liquidity and spreads: many of these shares are lightly traded and very difficult to buy and sell in any quantity. They may also have huge bid-offer spreads – 5% upwards is not uncommon. If you’re not familiar with spreads, there’s a good explanation here.
Information on liquidity and spreads is available at the bottom of each StockReport. Here’s an example. I’ve circled some of the main metrics:

In short, big spreads and poor liquidity mean that these shares aren’t suitable for short-term trading. Even if the shares rise, you may still lose money when you sell. In my view, these are generally shares you should plan to hold for years, if not indefinitely.
Lack of control: many of these firms are AIM-listed and have majority shareholders with the voting power to delist the stock arbitrarily, should they wish to. iEnergizer was a recent and extreme example of this. But it’s always a possibility.
To try and gauge the likely risk of delisting, I would look at factors such as:
Age of listing
Ownership profile - has it changed?
Recent newsflow/share price action
Special situations: some of the companies in my screen results are regular businesses, operating normally. But some companies that fall into this category may also be special situations, where the outlook is harder to predict and potentially binary – all or nothing.
Exchange listing: some of these stocks trade on the Aquis Exchange, which was previously known as NEX Exchange. Not all brokers offer these shares and some may only be available with telephone dealing. Liquidity is likely to be extremely poor.
#1: Volvere (LON:VLE)
This small-cap turnaround specialist is an investment group, typically buying food businesses, improving their performance, and selling them on.
The long-term record of value creation for shareholders has been excellent:

There have also been sizeable share buybacks and tender offers that have seen the share count almost halve over the last decade. With the stock often trading at a discount to book value, these cash returns should have been accretive to shareholders.

Graham has covered this business regularly in the SCVR, most recently here, when the death of co-founder and CEO Jonathan Lander was reported.
#2: Camellia (LON:CAM)
This quirky family-controlled business is mainly focused on agricultural operations in various overseas markets. Examples of produce include tea, macadamia nuts, and avocados. Alongside this, Camellia also has various non-core assets, such as an interest in an insurance business and surplus property.
The shares have traded at a permanent discount to book value in recent years, but have proved to be a value trap for investors seeking to profit from this discount.

Given all of this, why might I consider Camellia today?
With a reported NAV of over £130 per share, the discount has now grown to more than 60%. Most of this is backed by tangible assets and there’s a sizeable net cash position;
Management are making moves to sell non-core assets, including the insurance business and some property;
The dividend yield has now risen to nearly 3% and the payout has not been cut for over 30 years;
Ultimately, I assume that the controlling family interests will want to preserve and perhaps release value from their assets.
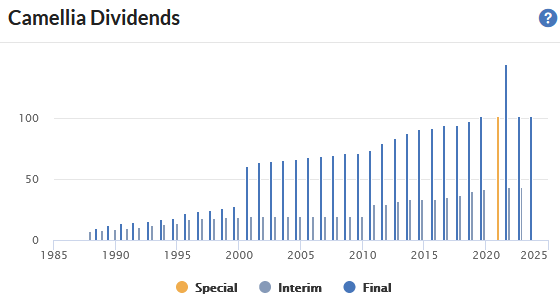
Further disappointment is possible. But Camellia shares are now trading at levels not seen since 2009. For investors willing to dig into the accounts and understand the component parts of this business, I think Camellia might be worth further research.
#3: Andrews Sykes (LON:ASY)
This £260m AIM-listed business is an equipment hire company that specialises in supplying heaters, air conditioners and water pumps. As such, it tends to benefit from extreme weather conditions and other types of climate-related disruption.
The firm has a reputation for excellent service and is controlled by the Murray family, who own about 90% of the shares. The free float is miniscule, at under 10%, but Sykes has been listed on the London market since 1986 and has been in business for 160 years.
Source: Andrews Sykes
Profits have risen steadily over the last decade and the group is expanding in Europe as well as the UK.

These shares may not seem obviously cheap on 15x forecast earnings. However, the company maintains a generous net cash balance and the shares offer a 4%+ dividend yield, with a track record of additional special payouts.
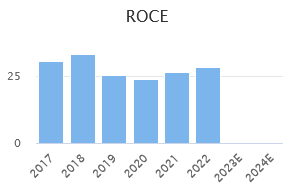
Profitability is excellent, with operating margins and ROCE consistently in excess of 25%.
Interestingly, the Murray family also controls London Security (LON:LSC), which also appears in the results of this screen. However, LSC has a sub-1% (!) free float and almost no liquidity, so I’ve ruled it out – but it has also been a good performer over time.
Final thoughts: I think the shares I've highlighted – and some of the others in my screen results – could be worth further research.
However, I would caution that potential investors will need to check everything themselves and be prepared to dig into the accounts (and subsidiary accounts) in order to understand the investment cases of these businesses.
With no broker coverage and generally no press coverage, there’s even less of a safety net than usual. Bad news can appear out of the blue, with no prior warning. So it’s essential to have a good understanding of the business and a strong conviction in the position.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
Thanks Roland. That was very interesting. Another thing for people to consider is that, for the shares that you are NOT considering in today's piece, broker forecasts are always wrong and cannot be relied upon. If we are lucky the error between the forecast & the actual outcome might be quite small, in which case the forecast turned out to be quite useful. On the other hand, the error might be quite large, in which case we may well have done better to ignore the forecast. So perhaps, if we can't rely on the forecasts, then maybe it makes sense to look at companies with no forecasts? However, I do still like to see the forecast because it helps me to avoid that feeling that I might be about to take a leap in the dark!
Hi WarrantStar,
You make a good point - broker forecasts are not always reliable and are quite often revised. So relying too heavily on these, rather than one's own measures of valuation/quality/momentum, can be unwise.
Despite this, consensus forecasts do generally provide a useful ballpark guide to expected results, though, in my experience.
Roland
Thanks, Roland. Your articles are always stimulating. This is an interesting variation on Slaters’ Zulu Principle.