Hunting for bargains: 7 UK shares at 52-week lows

After a quick dip in March, the main UK share indices have bounced back nicely and are currently hovering around breakeven on a year-to-date view. The only exception is the FTSE 100, which has eased ahead slightly thanks to some heavyweight risers.
However, this broadly neutral performance masks the fact that there have been some big fallers so far this year. This is especially the case in the FTSE 250 and small-cap indices.

Academic research into investor behaviour research suggests that we may be able to use this situation to our advantage. Put simply, investors have a tendency to overreact to bad news.
For small caps especially, this negative momentum may then be compounded by a wave of shareholders selling purely because of a stock’s falling price, which may have triggered stop losses.
For investors who can tolerate uncertainty and perhaps look a little further ahead, these big fallers can sometimes offer opportunities. I know that some of my biggest successes over the years have come from buying shares that have been temporarily out of favour. This is because they’ve offered me the opportunity to benefit from a re-rating as well as ongoing growth.
You don’t necessarily have to hunt among the weeds to find potential bargains, either.
One year ago, fashion group Burberry (LON:BRBY) (disclosure: I hold) was trading at 52-week lows of around 1,600p. The shares have risen by 60% since then and are now nudging 2,600p.
Bear in mind that Burberry is a high-quality FTSE 100 company that was never really in any danger of even reporting a loss, let alone suffering financial distress. All that was really needed was the confidence to look beyond the pandemic and trust that this 167-year-old brand would be able to pick up where it left off.
Oddly enough, Burberry now qualifies for Stockopedia’s 52-week high momentum screen. This is perhaps a useful reminder of what a powerful force momentum can be over the short and medium term.

In the remainder of this piece, I’m doing to demonstrate a simple screen I use to look for shares trading at 52-week lows. I’ll then highlight some shares I think might be worth a closer look.
My 52-week low screen
Share price information provided by stock exchanges routinely includes details of a share’s 12-month trading range. Said differently, it contains the stock’s 52-week high and 52-week low.
Stockopedia includes this information at the bottom of each StockReport:
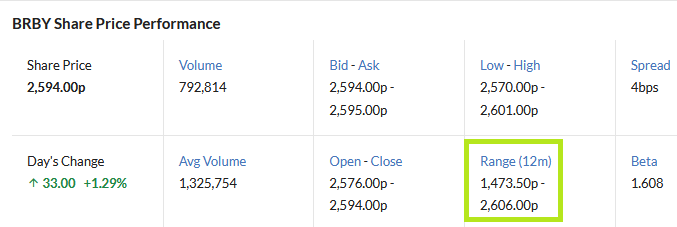
The 52-week low was one of the key metrics used by famed value investor Walter Schloss. He learned his trade with Benjamin Graham, before starting his own fund and delivering a 15.7% average annualised return for 45 years, from 1956 to 2000.
Schloss also used other metrics including price/book value and debt when hunting for potential bargains. Stockopedia has a Walter Schloss screen that you can see here. However, I tend to find that the use of book value is more restrictive today than perhaps it was in the past.
For this reason, I’ve opted to use the StockRanks alongside the 52-week low in this screen. My hope is that I can use this combination to identify good, improving businesses that are temporarily being mispriced by the market.
This screen is much simpler than my usual efforts. I’m simply screening the main indices for shares that are within 10% of their 52-week low, with a StockRank above 50. I’ve also added a rule with a minimum market cap of £20m to avoid nano-cap situations.
Here’s how that looks – you can see (and fork) the screen for yourself here:
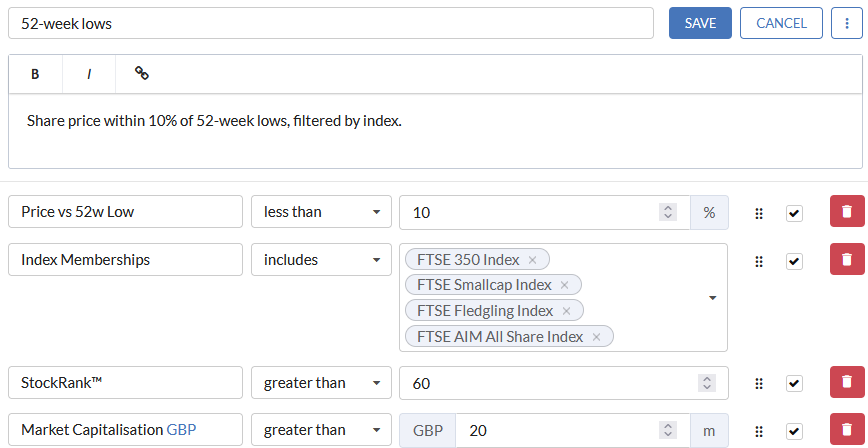
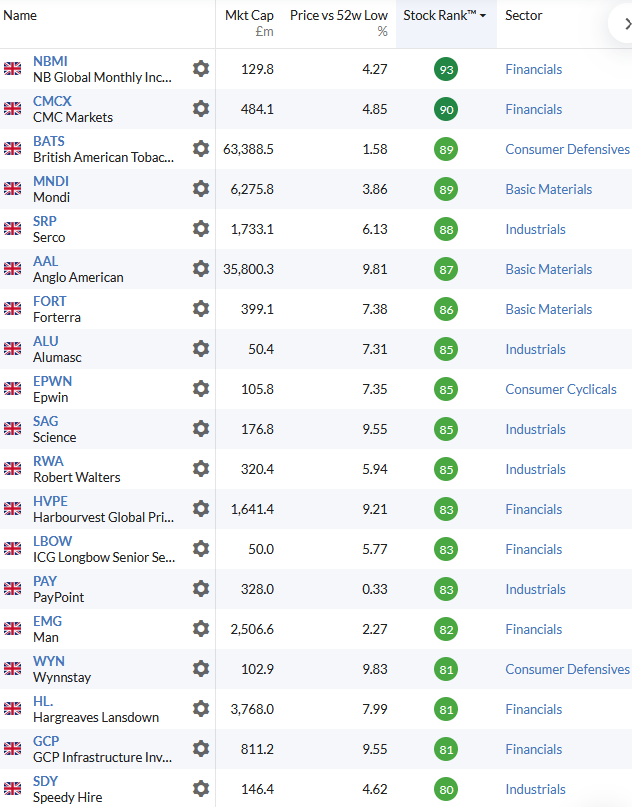
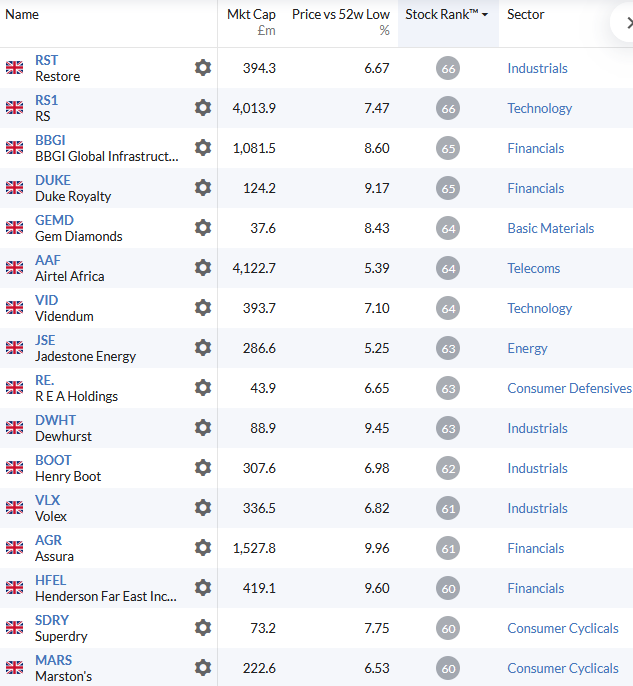
This screen produces 46 results, at the time of writing. I’ve ranked these by StockRank and divided them into three groups.
StockRank 80-100:
StockRank 70-80:
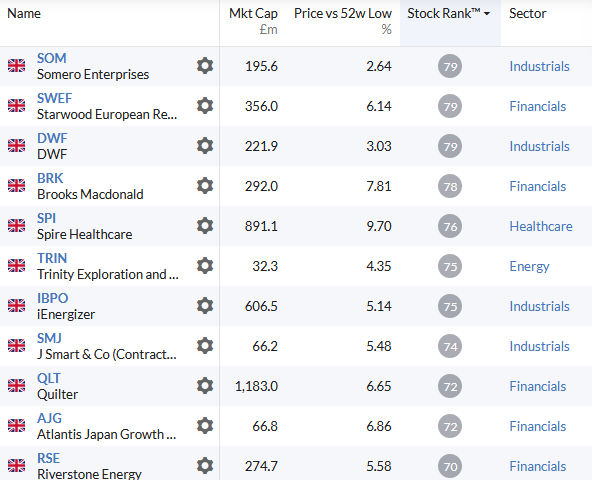
StockRank 60-70:
Results review
Although I certainly wouldn’t buy all of these shares, there are a fair number that are of potential interest to me. Here’s a short summary of companies that I’d be tempted to look at more closely.
CMC Markets (LON:CMCX) - this financial trading platform is still suffering a post-pandemic hangover, but it’s starting to look very cheap to me. Assuming profits halved last year, in line with guidance, I still estimate an EV/EBIT multiple of less than 10.
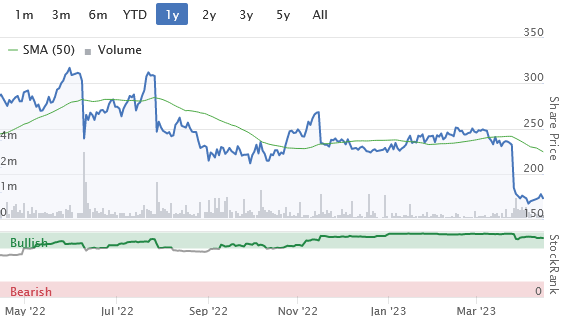
I suppose the risk is that the business model has run out of steam in an increasingly competitive market. But CMC remains highly profitable and benefits from owner-management. Buyers are getting a lot of business for their money, in my view.
British American Tobacco (LON:BATS) - a controversial pick for ethical reasons, with a question market over its long-term outlook and a lot of debt. But this remains a very large and profitable business, with prodigious cash generation.
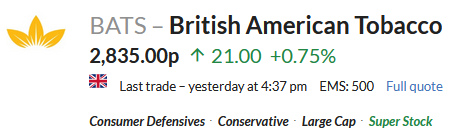
In my view, even tobacco stocks have their price. At under £30 and with a dividend yield over 8%, BATS looks decent value to me.
Mondi (LON:MNDI) - this FTSE 100 packaging group was originally spun out of miner Anglo American (LON:AAL). Mondi has always had a disciplined balance sheet and return on capital employed has averaged 16% since 2017.
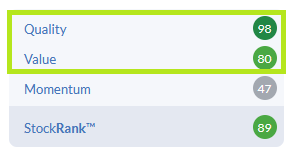
The business is still smarting from the effective loss of its Russian operations, which previously generated around 20% of group EBITDA. However, growth efforts have continued elsewhere and I think the company will be able to move on successfully. Good value on a cyclical view, in my opinion.
Robert Walters (LON:RWA) - I wrote about this recruiter in the SCVR recently, so I won’t repeat myself here. But I think this a well-run business that looks attractively valued at current levels. The only caveat might be that founder-CEO Robert Walters is just about to retire, after more than 30 years in charge.
Forterra (LON:FORT) - this brickmaker is expecting “a 20% fall in underlying demand” this year, which sounds scary. But the shares have already de-rated somewhat and management points out that imports (which are more expensive) should be cut before UK suppliers suffer too much.
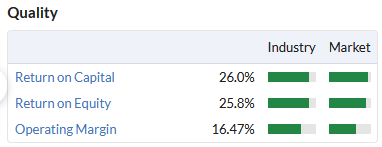
I’m a little wary about the near-term outlook, but the fundamentals of this business and the wider brick market look positive to me. With the shares trading on a single-digit P/E, Forterra’s strong quality metrics suggest this could be worth exploring as a potential value play.
Hargreaves Lansdown (LON:HL.) - Stockopedia’s algorithms still categorise this market-leading investment platform as a high flyer, but the shares are starting to look very affordable to me. The stock is down by 65% from its pandemic peak and is trading at 10-year lows.
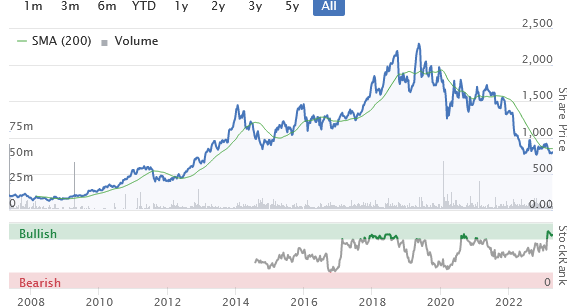
I think this business may be forced to cut its prices somewhat to become more competitive. But that looks affordable to me, given Hargreaves’ near-50% margins.
In my view, this business should continue to benefit from macro trends towards self-managed investment, and remains in an enviable position to deliver attractive long-term returns. With a 5%+ dividend yield, I’m tempted at current levels.
Somero Enterprises (LON:SOM) (disclosure: I hold) - this US-based concrete-levelling equipment specialist reported record revenue for 2022 and paid out $29m in dividends last year (also a record).
I think it makes sense to price in a more cautious outlook for 2023, but management says that the non-residential construction sector remains “healthy and active” in its core US market.
Current guidance is for flat revenues and a modest decline in EBITDA this year. Broker forecasts are translating that into a 6% decline in earnings per share this year, with a 40% reduction in last year’s bumper dividend.
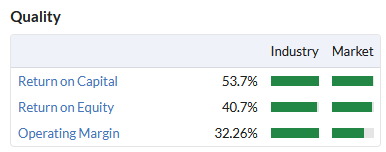
These estimates price Somero on eight times earnings with a 7% dividend yield. I think there’s certainly some downside risk from here. But the group’s cash-rich balance sheet and exceptional quality metrics should provide a good margin of safety for shareholders.
I hold the shares and am considering whether to buy more.
Conclusions
In my experience, hunting for shares to buy among big fallers can be a profitable exercise. But it’s not without risk. As I’ve learned to my cost over the years, cyclical declines can be much longer-lasting and deeper than expected.
With this in mind, the ideas I’ve discussed above are only intended to be food for thought and are not investment recommendations. As always, further research would be needed before making any decisions.
I’d be interested to hear your thoughts on the companies above – and on any others from the screen that I haven’t mentioned. There are certainly some others I might consider at current levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
I use a criteria in my own 52 week lows screen that the QV Rank should be greater than 80 (although using 70 can wider the selection). My logic is that if we are looking for stocks that are out of favour momentum wise, then the other factors (Quality & Value) should remain high to make it a bargain purchase at these lows.
P.S. I also have an exclusion criteria for Industry Groups comprising; Investment Banking & Investment Services, Real Estate Operations, Residential & Commercial REITs and finally Collective Investments. I exclude these as they are not sectors I understand and frequently this screen pulls up results from these sectors, which I think may be skewed by their specific industry dynamics.
iEnergizer (LON:IBPO) announced a possible de-listing from AIM today. Perhaps AIM shares without a large institutional shareholding ought to be excluded from your calculations?
I hold British American Tobacco (LON:BATS) , Somero Enterprises (LON:SOM).
Was tempted by Mondi (LON:MNDI) and CMC Markets (LON:CMCX) but I already hold DS Smith (LON:SMDS) and IG group (LON:IGG) .
...and Hargreaves Lansdown (LON:HL.) was both a platform I have used for ~10y and a recent-ish purchase and so it is fresh in my mind.
My rationale was
+good
I really hope HL can keep cost growth below that level.
If i am right, profits will rise by inflation x a multiplier > 1
-ungood
~Background scenery
costs have risen by 14% that reflect some one-off items.
"Labour costs increased 21% to £81.5 million (H1 2022: £67.6m) reflecting the annualisation of the FY22 increase in headcount and salary inflation of c5% overall which has been weighted towards our more junior colleagues. Acknowledging the financial impact that the current environment is continuing to have on colleagues, we have also announced a one-off Support Payment for colleagues who continue to feel the impact of cost inflation of £1.1 million."
I give that a B-
Excellent write up Roland, I am sure we can all do with more of these articles.
I like Forterra but prefer Holcim good five year track record and decent dividend for my share ISA
Forterra looks an interesting situation. In mind of MBH's recent upbeat TU I wonder if FORT will be surprising to the upside?
I've slowly been adding to Volex (LON:VLX) hey I was proven right, long hold 3-5 yrs I'm really hopeful on this share.
Thanks Roland. I have been with Hargreaves Lansdown (LON:HL.) since 2004, they floated in 2006, and they are very reliable and after all this time I am so used to their systems.
They tick a lot of boxes and Customer Service for such a big beast is pretty decent. I remember buying 22,000 shares soon after they floated at from memory 160p and had I kept them they would have been a 10 bagger. Always bugged me that I sold way too early.
I am very tempted at the current SP.
Also shows Biopharma Credit (LON:BPCR) with Stockrank of 92.
Thanks Roland,
I often idly do this and agree about Somero Enterprises (LON:SOM) and Robert Walters (LON:RWA) , I hold both although I also think PayPoint (LON:PAY) deserves a mention given the steady and arguably undeserved decline and the near 30% stakebuilding by the Spaniards
Meanwhile carry on provoking those thoughts
Just FYI
https://t.co/GmVUsBmOcy
article about buying the dip
Thanks for that Nick - very worthwhile short article to re-inforce buying the dip.
As a quality and growth investor, Stocko screens threads are rarely of direct relevance and I only scan for completeness. Remarkably however, I find no less than three of my recent purchases on this thread, Somero, RWA and Forterra. I’m pretty confident in all three at these levels. They could always go much lower but, long term, I like the entry here.
Thanks for this Roland. I think I finally need to have a proper look at Hargreaves Lansdowne - dismissed it for many years because it was too expensive, and more recently due to the various issues it has faced. However things seem to have stabilised, and looks pretty good value on 12 PE ratio and 5%+yield. As a mature business, probably won't see a huge amount of growth, but revenues are incredibly sticky (have you tried changing broker?) and they are also benefiting from higher interest rates.
Agree with your thoughts Bouden - especially on how unlikely people are to transfer out - HL make it especially difficult for clients holding Funds as they, HL often trade a different class of fund that cannot be transferred but needs to be sold . However, my main thought is that new investors are not so likely to choose HL but one of the many newer and cheaper platforms out there.
I think you're right, there's a lot of competition now for new investors, hence why HL unlikely to see strong growth. However, it's a good platform and well established brand so should be able to bring in at least a bit of new business - if you add underlying market growth then they should be able to steadily increase AUM and profits over time.
Thanks, Roland. Do you have a way to screen for sectors that are cyclical and turning up?
Hi FREng,
I don't think I have anything like this at the moment, but I think it could be an interesting topic for a future screen.
I'll put some thought into it and see what I can come up with.
Regards,
Roland
Gold and er gold and if want diversification er gold and er like some fun Silver and if green then lithium or uranium and if into finance then bitcoin - screen away, screen away.
Yup Gold / silver
Good upside potential and good downside insurance.
Win win
Terrible yield though.