Hunting for bargains: REITs trading at big discounts

It’s impossible to look at the property market today without considering the impact of higher interest rates. All else being equal, higher rates put pressure on property prices.
Housebuilders are one obvious area of interest, but I’ve also been looking at REITs. These property investment vehicles allow investors to generate income from a much wider range of property classes.
Looking at the UK Residential & Commercial REIT sub-sector right now, almost all of the 50 REITs listed are trading at a discount to book value. In many cases, the discount is over 25%. My research suggests the FTSE 350 REIT sector is trading at a level not seen since 2012.
This cautious market view contrasts with the confident-sounding trading updates issued by many REITs in recent months. Median stats for the sector also look fairly benign:
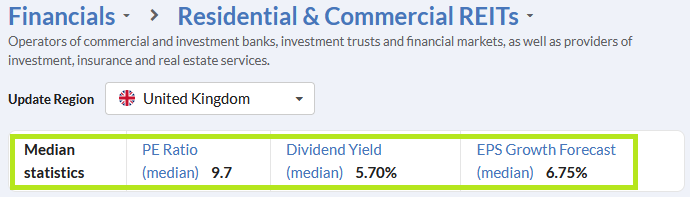
Are today’s discounted valuations a sign that bigger problems lie ahead, or has the market sell-off gone too far and created opportunities for savvy investors? I think the answer is probably a bit of both, as I’ll explain.
In the remainder of this piece, I’ll highlight some potential concerns and explain what I look for when analysing REIT accounts.
I’ll also highlight some examples of REITs that I think offer good value and a reasonable safety in today’s market.
What’s a REIT?
Before I go any further, I think it’s worth taking a brief look at what distinguishes a REIT from a regular company.
A REIT – or Real Estate Investment Trust – uses shareholder equity and debt to invest in property.
As with a regular investment trust, shares in a REIT are bought and sold without affecting the underlying assets, which belong to the REIT itself. Shares can trade at a discount or premium to their book value.
REITs are exempt from corporation tax on profits from their rental business and certain property disposal gains. In return, they’re required to distribute at least 90% of their profit from property rental to shareholders.
Cash is normally returned to shareholders as dividends. Payouts funded by tax-exempt profits are classified as Property Income Distribution (PID), while payouts from REITs taxed profits are classified as regular dividends.
PIDs and normal dividends are treated slightly differently for UK tax purposes. This may be worth investigating if you expect to receive substantial income from REITs.
FTSE 100 members British Land (LON:BLND) and Land Securities (LON:LAND) were among the first to adopt the structure when it was introduced to the UK in 2007. But the number of listed REITs has mushroomed since the REIT regime was relaxed somewhat in 2012.
This coincided with the start of an unprecedented period of low interest rates. As a result, many of today’s REITs are untested in a normalised interest rate environment.

Source: Bank of England
What could go wrong?
REITs aim to generate a profit from the spread between their funding costs (dividends and interest payments) and rental yields on the property they own.
I think REITs can be a great way for individual investors to generate an income from different types of property. But I think it’s inevitable that some of them will run into problems in this changing financial environment.
Funding challenges: Borrowing costs, rental yields and property prices are all interlinked.
Higher borrowing costs mean that the rental yield required from a property also rises. This means either that rental income must rise, or that property prices must fall. As with fixed-rate home mortgages, there’s some lag on this feeding into the system. But it has to happen.
If the gap between rental income and borrowing costs is permanently compressed, then REITs’ dividend-paying capacity will be reduced, unless they can reduce leverage.
However, raising capital in this environment isn’t easy. In general, raising equity when shares are trading below book value is very difficult.
The only other way to raise funds and reduce gearing is often to sell property. We’re already seeing some of that, albeit often under the guise of ‘capital recycling’ or ‘portfolio optimisation’.
Environmental ratings: sustainability requirements are another concern. Starting in April 2023, commercial property for let in the UK requires an EPC rating of E. In 2027, this requirement will rise to an EPS rating of C, and in 2030 it will be B.
To meet these standards, much of the UK’s commercial property will need significant refurbishment. In some cases, it won’t be cost effective or even possible. Assessing the likely cost and feasibility of these improvements isn’t easy.
Understandably, tenants aren’t keen to sign leases that could see them occupying non-compliant property in a few years’ time.
What seems to be happening is that tighter environmental standards are combining with lower post-pandemic office occupancy to create a two-tier market.
High quality, modern office space in London and other primary locations is doing just fine. Occupancy is high and rents are rising – Landsec’s London office properties are 99% let.
Older and less well-located office property is not doing so well at all. Small cap Regional REIT (LON:RGL) – which describes itself as a regional office specialist – saw its net asset value fall by 25% in 2022. More than 15% of its property, by rental value, is vacant.
I’ve focused on offices here. But other dynamics again may apply in sectors such as healthcare, logistics, and residential property.
The challenge is that many of these factors will interact and vary in ways that we can’t yet predict.
For this reason, my approach at the moment is to take a fairly conservative view when analysing REITs.
Near-term risks may not yet be fully evident – I think it makes sense to look for a generous margin of safety.
What I look for in REIT accounts
Property accounting includes a number of metrics that you won’t find in other sectors. I think it’s worth getting to grips with a few of these. They make it easier to understand the financial risks and compare different REITs.
Loan-to-value (LTV): net debt as a percentage of the value of the property portfolio. As a rule of thumb, I’d say under 30% is low and over 50% is very high. Loans often include a LTV covenant, often at around 50%. Remember that the LTV ratio can rise if property values fall, even if debt remains unchanged.
Weighted Average Unexpired Lease Term (WAULT): the average lease term remaining across the portfolio, weighted by rental income. A higher WAULT should provide security of income – unless tenants can’t pay.
Average debt cost: this needs to be funded from net rental income, preferably leaving enough over to fund dividends as well.
Weighted average debt maturity: the average remaining time until the REIT needs to refinance its debt. Typically, this metric masks a much wider range of individual maturities, so it can provide a false sense of reassurance. But it’s a useful metric.
Fixed rate or floating rate: if interest rates have been fixed or hedged, then the REIT will enjoy stable debt payments for the remaining period of the fix. Payments may then rise. Floating rates mean interest payments have probably already risen - check the next set of accounts.
EPRA vs IFRS: EPRA is the European Public Real Estate Association. It provides a methodology for calculating underlying earnings and net asset value that provides a more realistic view of the underlying rental performance of a REIT than standard IFRS earnings.
Other measures frequently seen include Estimated Rental Value or ERV, which is the expected rent if a property was let today.
ERV often appears close to measures of reversion, which is the theoretical gain (or loss) in rental yield that would result if the portfolio was fully re-let at the ERV. Reversionary gains often sound attractive, but can take many years to achieve.
3 REITs I’d consider today
What kind of REITs would I consider buying today? I’m sure there are opportunities in beaten-up small-cap REITs right now, but I don’t think I have the sector knowledge needed to reliably identify them.
For me, this is the time to focus on quality. Some of the metrics I’d look for today are:
A sub-30% LTV
A sizeable discount to book value
Average debt maturity that is comparable to WAULT
Ideally, four or more years of predictable rental income from existing tenants
Good quality, modern property portfolio
The good news is that REITs satisfying these criteria aren’t hard to find at the moment. Here are three I’d consider today:
Landsec: this FTSE 100 REIT has a LTV of 32%, a WAULT of 6.5 years and average debt maturity of over 10 years. Occupancy of the group’s modern London offices is 99.5%, retail is around 95%.

This investment-grade package is currently available at a 35% discount to NAV, with a 6.4% dividend yield. Risks remain, but I think this looks a fairly safe choice.
SEGRO (LON:SGRO): I bought these shares at 250p in 2013 and (sadly) sold much too soon. But the market heavyweight in the warehouse sector has seen its share price halve since 2021 and is now trading more than 20% below book value - the biggest discount since 2012.

Long leases, stable financing and high occupancy suggest lowish risk. My main concern is Segro’s substantial pipeline of new developments. If occupier demand softens, this could become a drag on profitability and cause borrowing to rise.
Derwent London (LON:DLN) - not as big as Landsec, but with a quality portfolio of well-invested office property in London’s West End. Q1 lettings were 6.6% above ERV and the portfolio’s vacancy rate is under 5%.
The LTV of 23% looks reassuring to me. Portfolio WAULT and average debt maturity are both c.6 years. Derwent London shares currently trade at a 40% discount to December 2022 NAV and offer a yield of nearly 4%. These metrics were last seen in 2008.
I think there’s value here, unless I’m missing something.

Final thoughts
I think investors can find good value in UK REITs at the moment, but it’s important to be selective. Some of the very high yields on offer look risky to me.
Landlords are going through a period of adjustment to higher rates that could last for several years. In my view, the main risk is that this process could be longer and deeper than anyone is yet expecting. The outlook for sub-standard commercial property in secondary locations seems particularly unclear.
While I favour a systematic approach to investing, I think this is a situation where investors need to dig into the accounts to find the best opportunities.
However, with high-quality REITs trading at discounts not seen since the financial crisis, I think it’s possible to take a conservative approach and still find attractive valuations.
If I’m right, I think patient investors could enjoy attractive medium-term returns, without needing to take on too much speculative risk.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

15 comments
Dear Roland,
Very interesting article. Do you have similar analyses on European (ex-UK) REITS or similar Real Investments companies? For example, in Belgium and in other countries, a proxy tax incentive exists and several companies (under the generic name of SRI or SICAFI, in French) have taken such a status.
Than you in advance for your answer.
This is merely anecdotal, but the culture that a founder/CEO imbues in a company can persist through the ranks for a long time.
In a prior life as a humble, fairly junior, analyst, my phone would ring and it would be John Burns on the line (former CEO of Derwent), offering to discuss the most recent results one to one.
Yes, we were a significant shareholder, but that was true for many other property companies and no other CEO did that regularly. It showed an attention to shareholders and a personal touch that left an impression to this day.
All useful tools, comments, sources of info and articles,
add the last time the topic came up:
https://www.stockopedia.com/co...
Today I have sold some into the enthusiastic response to the inflation statistics.
We are dealing with two cycles : the real estate move from sellers' to buyers' markets, measured in decades and the stock market perceptions of the future.
It is unlikely the bottom of the commercial property cycle is here.
The stock market cycle is influenced by other factors and will fluctuate more than warranted by supply and demand for bricks and mortar.
A lot of Commercial Property Trusts are great value at present and paying big dividends. I’ve held several in the UK Commercial Property and Europe Commercial Property sectors since the 2020 covid crash. The big capital gains have gone for now as most have fallen towards the lows then, which is likely a very good buy opportunity again now. The big discounts to NAV and very big dividends where covered are big attractions. (They were even better buys in 2020 when Aew UK Reit (LON:AEWU) which I still hold and was just 63p to buy and paying 8p (13%) dividend which they have maintained since. AEWU is at a smaller discount than most of the others so is no,longer the most attractive as a new buy).
This site is excellent for all Investment Trusts including Commercial Property and better than Stockopedia as the latter include figures often not relevant for Investment Trusts and omits vital information like NAV and discounts to NAV. Just click on the red headings for each Trust to bring up a wealth of information:-
https://www.theaic.co.uk/aic/f...
abrdn Property Income Trust (LON:API) 48p 40% discount and 8.3% dividend, Alternative Income REIT (LON:AIRE) 61p 28% discount and 9.4% dividend and Schroder Real Estate Investment Trust (LON:SREI) 42p 35% discount (despite heavy buybacks to try to reduce it) and 7.8% dividend look well worth checking out. I hold all 3.
Most tempting of all is arguably Tritax EuroBox (LON:EBOX) 53p and 40% discount and 8.3% dividend in the Commercial Property Europe sector. I hold that one too:-
https://www.theaic.co.uk/aic/f...
While interest rates are high and possibly going higher still (we might know better after latest UK inflation figure tomorrow) Commercial Property Trusts might stay out of favour with investors as higher interest rates make the big dividend yields for these Trusts less attractive when alternatives including cash are paying a lot more than they were. But the moment there’s even a hint of interest rate cuts, the sector could fly as discounts return to normal. Indeed in the past some of these Property Trusts, includingTritax EuroBox (LON:EBOX) traded at big premiums to NAV and the big share price falls are enhanced because the share has gone from premium to discount.
The British Land divi is 5.7%, roughly the same as a zero risk bank deposit.
The British Land divi is 5.7%, roughly the same as a zero risk bank deposit.
Although I know what you mean, it's only zero risk in the sense of guaranteeing that you'll lose money in real terms, with inflation running ahead of that and no possibility of capital appreciation. A better comparator might be 10 year gilts with a yield of about 4.4% and a reasonable chance of doubling your money over a decade, assuming interest rates drop back over the next few years.
To make the REITs worth the risk you have to believe that you'll see capital appreciation or a rising dividend that will beat that. Most have been pretty woeful at both, although there are exceptions, particularly in the logistics sector, even after the recent blow out.
Overall REITs with reasonable WAULTS, manageable debt and big discounts to NAV are probably worth the risk now. Many of the better ones dropped in sympathy with bond yields rising last year, so the reverse ought to apply (although markets tend to be logic free zones at the best of times), offering capital gains to go with the dividends and hopefully allowing them to refinance in a few years time at more favourable rates. Some of the discounts look overdone, even allowing for the lag in mark to market values.
Personally I treat the sector as a single diversifier, buying a mini-portfolio of the things across market cap size and in various sectors, rather than buying larger amounts of one or two. Probably some of the most unloved areas will do the best over the next few years, but I'm happy to tread the middle ground.
As noted below, the requirement to pay out 90% of profit is a reason to be careful around REITs, but there are enough around that are sensibly managed and well enough financed to be worthy of investment. But it's an area to do a bit of DYOR before investing, that's for sure.
Good article Roland. As ever :-)
timarr
You are right that equities should follow inflation in the long run. But only inflation linked gilts follow inflation.
I hold LXi which has tanked like the rest this year. I still like the diversified portfolio, though, and long WAULT. Bit concerned the debt has jumped following the Secure Income merger but loan book interest doesn't look too bad. Any views on this one Roland?
Schroder Real Estate Investment Trust (LON:SREI) this looks the best REIT pick in my view (I hold) - they very smartly refinanced their debt a couple of years at the very cheap rates that were available - most of their debt is now fixed below 3% for around 13 years which gives them a nice competitive advantage. They also have a good property portfolio, skewed towards multi let industrial, with a lot of reversionary potential (basically the level of rents they expect to acheive once all new leases agreed). I believe it's on a discount of around 35% last time I checked and the dividend yield is around 7.7% (could be above 9% once the reversionary yield comes through).
There has been a lot of consolidation in the space with a few of their peers being the subject of bids - has to be a decent chance of SREI get bid for too. They've done a recent presentation on Investor Meet Company which is worth checking out.
The REIT structure does have a dangerous flaw, in its tax advantage - the requirement to distribute 90% of profits can leave a very weak balance sheet in property downturns, as I found out to my cost in 2008. They're not for me now.
Depends on the REIT - if they maintain a conservative LTV and fix their debt for a reasonable period then should be fine. A lot depends on the sector as well - regional offices and high street retail could struggle, but other areas are still doing well.
One that is hugely overlooked is Alternative Income REIT.
"The weighted average unexpired lease term at 31 March 2023 was 16.7 years to the earlier of break and expiry (31 December 2022: 17.0 years) and 18.6 years to expiry (31 December 2022: 18.8 years)."
The portfolio is fully let.
But most importantly: "In aggregate, 96% (31 December 2022: 96%) of the portfolio's income stream is reviewed periodically on an upward only basis, in line with inflation (44.9% annually); with 70.0% and 26.1% of the portfolio inflation-linked (subject to floors and caps) to RPI and CPI, respectively. The remaining 3.9% of the portfolio's income stream is subject to fixed uplifts or expiries." This is capped at about 4%, but still a very attractive proposition.
The most recent NAV was 83.5p, current share price is 60.5p. Discount is 27.5%. Not quite 30%, but then your chosen 3 don't have the dedicated income uplift that AIRE does.
They are on course to pay 5.7p for the year just ended, June 2023. Yield is about 9.4%. Back of the envelope sums, suggest 5.8 is quite likely.
Rental income, and thus EPRA earnings, unless something goes really wrong with the expense line, suggests a dividend of about 4% higher is easily in range for the current year . Say, just over 6p., near 10% yield. This growth could continue for a couple of years.
The only fly in the ointment is that their debt is 3.1% fixed until Oct 2025. If that were to jump to say 5%, the EPRA earnings would fall. But
Again back of the envelope, 2026, could still give 5.8p dividend, then growing at about 3% to 4%. Think of it as a yield of 9.5%, with a couple of special over the next 3 years, and growing again from 2026. And growing like that for 17 years!
There seems to be no broker who covers this. The numbers for the yield on Stockopedia are hideously wrong. I have pointed this out and been ignored.
Have a few in your ISA, it will pay for a holiday!
And one addendum.
Again back of fag packet and assuming a 4% rise in expenses, the EPRA earnings should be just over £5m.
Mkt cap is £49m, so p/e of sub 10x on 17 year, index linked(subject to cap) rent.
If that profile were on a consumer goods company, would the p/e be twice that?
I own this REIT and just wanted to say thanks for the overview, it’s a good whsitle stop tour of the investment case. My concern would be regarding that debt refinance - good spot. Have you modelled how much the earnings might fall?
What concerns me is that the £49m mkt cap (£87m EV) is too small to be sustainable?
Add the overheads of running an investment trust board to the ongoing listing costs (£400k p.a.?), plus all the professional valuation fees for the property portfolio and what is left?
The Independent Investment Trust decided to throw in the towel as a solo entity once Max Ward retired and that was in the region of £200m....