Ilika - I no lika the progress
Analyst’s view:
The key Automotive EV market is being de-emphasised following mixed feedback from a key Automotive OEM tester. Meaningful revenue from Cirtec royalties is likely pushed out to 2030, given the product validation and manufacturing qualification stages still required. The cash burn suggests that they have less than a year of cash runway, despite raising £5.5m in June.
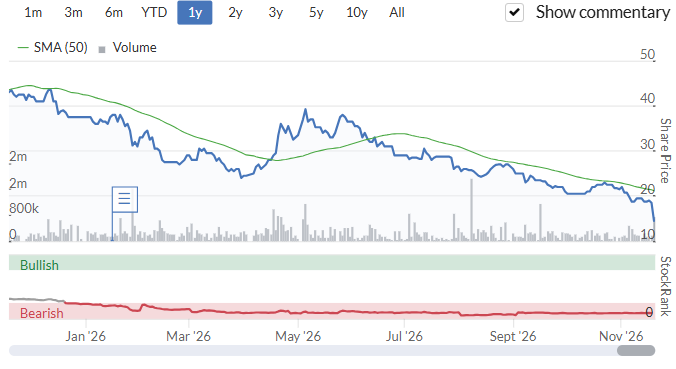
Given all this, perhaps the most surprising part of today's market reaction is not the 20% fall in the share price, but that the market cap remains above £28m! Until it is clear they have sufficient capital to reach cash-flow break-even on existing signed contracts and deals, this is exactly the sort of company we should be negative on. RED
It's probably not surprising that a Sucker Stock with a Stock Rank of 8 is disappointing investors this morning. With a chart looking like this, they perhaps need to change their name to I-no-lika:
The issue appears to be concerns around their automotive delivery. The negative point is that the cells need lower self-heating and lower internal resistance at high power for automotive use. That is a cell-performance issue, not just a manufacturing one, and it goes to whether Goliath works in EVs at all. Only one partner has reported so far, and the others are still testing:
In the first half of the Period, Ilika supplied Goliath 10Ah prototypes to three US and European automotive companies...
Testing by some partners is still ongoing, but initial feedback from one of the automotive partners highlighted:
- A much-increased repeatability of the 10 Ah cell performance compared to the 2 Ah cells tested previously, demonstrating improvement in the quality of the Goliath manufacturing process
- Alignment of the measured cells’ performance data with the prototype’s specification sheet, demonstrating increased confidence in the manufacturing readiness level of Goliath cells
- A need to reduce self-heating and internal resistance of the cells at high power for automotive duty cycles.
The Automotive EV opportunity is what supports most of the valuation, and defence, marine and e-bikes are much smaller markets, so when they start to de-emphasise this, it becomes a real worry:
In parallel, Ilika is pursuing commercialisation of its Goliath 10Ah technology in applications where its performance characteristics address identifiable customer requirements and where development and qualification cycles may offer a nearer-term route to market. Readily addressable opportunities include defence, marine and specialist mobility applications, supported by ongoing customer engagement and the Company’s ability to undertake small-volume manufacturing at its UK facilities.
The financials reveal this is a largely pre-revenue business, with the valuation based on the hope of large future sales or royalties.
Sales of Stereax, their miniature solid-state batteries, are limited. Although they have provided the initial batch of Stereax electrodes to Cirtec in March 2026, the batteries are still in “product validation”, which the company says is separate from the manufacturing qualification it already announced, so that reads like another stage before any real sales.
Cash position:
The EBITDA loss for the half was £3.4m, roughly £6.8m a year. Of course, EBITDA leaves out capital spending, so actual cash outflow is probably higher. The £3m PRIMED grant has ended, and no follow-on grant has been announced.
Cash is £6.3m, which is lower than a year ago, even though the company raised money in June 2026. This points towards less than a year of runway left and another raise on the way. Something now likely to occur at a low price that dilutes existing holders.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Ilika (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?