Intercede: first-half revenue up 32% with forecasts unchanged

Analyst’s view:
This is an line update, but existing forecasts suggest double-digit EPS growth this year, so meeting these would not be too disappointing. Overall, I don't see too much to dislike here, except perhaps for a heavy dependence on US federal agency customers and a lack of new customer wins. Given the combination of valuation, quality and momentum, I think it's fair for us to move up to a neutral view.
Down 3% at 130p (£79m) - Trading Update, New Contract Orders and Renewals
Today's update from this digital identity specialist reads fairly positively, but it is an in line update with no change to broker forecasts.
Here are the key points:
H1 27 revenue is expected to be up by 32% to c.£10.85m
Subscription revenue up 25% to c.£0.45m
Perpetual licence revenue up 153% to c.£2.73m
Support & Maintenance recurring revenue up 5% to c.£5.46m
Professional services and development income up 44% to c.£2.02m
One of Intercede's aims in recent times has been to increase the proportion of revenue that's recurring. If I've understood correctly, the numbers above suggest £5.9m of recurring revenue (subscription plus S&M), or c.55% of the total.
That's below the 66% achieved in FY25, but I think this may partly be due to the large increase in perpetual licence revenue in H1. This appears to reflect the inclusion of some licence revenue that was deferred from H2 last year. So perhaps the balance of recurring revenue will improve again over the whole of FY27.
One point that may be prospective of future growth is the increase in professional services revenue. According to broker Cavendish, this tends to represent proof of concept work. If so, it could be predictive of future business wins.
Net cash: Intercede's balance sheet remains very strong. Cash of £23.4m is reported at 30 September 2026, with no debt. This accounts for more than a quarter of the current market cap. I would have thought that the company could afford to pay a modest dividend without too much risk to future flexibility.
FY27 outlook:
The Group has made a good start to H2FY27 and the Board continues to expect that full-year financial performance will be in line with current market expectations.
Consensus expectations are given as being for FY27 revenue of £21m and adj EBITDA of £5.0m. These would represent an increase of 22% and 25% from FY26, respectively.
While some investors may have hoped for an upgrade today, achieving these forecasts would represent a respectable rate of growth.
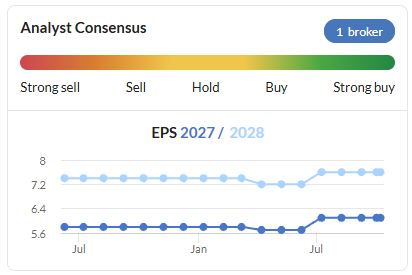
With thanks to Cavendish and Research Tree we have confirmation that earnings forecasts are unchanged today:
FY27E adj EPS: 6.1c
FY28E adj EPS: 7.6c
FY29E adj EPS: 9.6c
While forecasts were upgraded following the company's last set of results, July's Cavendish note suggests this was only done to reflect higher expected interest income (i.e. not because of an upgrade to business prospects).
New contract wins and renewals
The remainder of today's update is given over to an extensive list of recent orders and renewals. Smaller companies often like to do this, but I think it can become a little promotional.
While contract wins are sometimes material to a firm's prospects, very often they are simply business as usual. This is shown by today's in line guidance, which suggests all of this new business is already reflected in earnings forecasts.
Today's laundry list of wins and renewals includes eight items with values ranging from £420k down to £140k (< 1% of FY27 forecast revenue). Only two of these appear to be new wins:
a subscription licence order, including Support & Maintenance and additional recurring licences, for an existing US Federal Government deployment, totalling approximately £0.42 million;
a perpetual licence order, including associated Support & Maintenance, for an existing large US defence and aerospace customer, totalling approximately £0.24 million;
You can see the full list in the RNS, but what strikes me as most noteworthy is that they all come from existing customers - either US government agencies or US industrial customers. So it doesn't look like the company has won any new customers so far this year.
82% of Intercede's revenue came from the US last year, with two customers contributing more than 10% of revenue - so customer concentration is moderately high and may be worth monitoring.
Roland's view
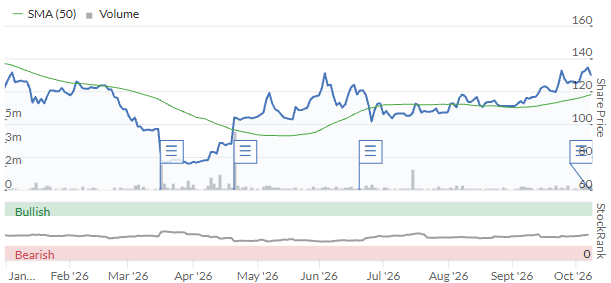
We've been moderately negative on Intercede for a while now - most recently I was AMBER/RED in April. Since then, the company has released an in-line set of results and forecasts have remained largely unchanged.
Intercede's share price has strengthened significantly since April, though:
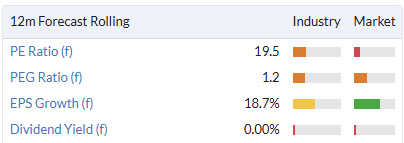
Quality metrics for this business are fairly good. Last year saw an 18% operating margin and 19% return on equity. Reflecting this, I think the current valuation looks full but probably not unreasonable (if EPS forecasts are met):
Given the strength of Intercede's balance sheet and today's unchanged forecasts for double-digit earnings growth, I don't think a negative view is appropriate here anymore.
I may be slightly late to this, but I'm going to move our view to neutral today - in line with the StockRanks. I think this is a better reflection of the mix of valuation, quality and momentum on offer here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Intercede (6)
Comments here are also visible in the Daily Stock Market Report
Any chance of a comment on Intercede (LON:IGP) ? Statement looks good albeit new business appears slower than expected. Hard to see how this business cannot be prospering given the current environment. I see cash balances are building. Appreciate the stock has motored somewhat but there has been some good sized director dealing
yes Martin, we are working on IGP.
Just to correct Roland saying Intercede (LON:IGP) haven’t won any new customers, the contracts announced today are only for the last 2 months. in August they announced 4 new customers including 2 new Federal agencies and what looks like an initial order for NATO.
Not sure why you think Intercede (LON:IGP) new business was slower than expected?
H1 revs were 10.85mm which is 52% consensus in what is a historically H2 weighted business. Licence income was 3.2mm vs 5mm FY broker forecast, Professional Services was 2mm vs 4mm FY expectations. Support and Maintenance was 5.6mm vs 12mm FY expectations but that was impacted by the weak dollar which has reversed in the last month.
Other positives include
They've managed to convert their first US Federal agency to subscription pricing. The £420k will increase their subscription income by 20% as their subscriptions are actually over £2mm but they account for it as 60% in Support & Maintenance and 40% as subscription licences,
The Proof of concept deployment (ongoing for 2 years) has stepped up to $500k per quarter which means they've added another person to the secondment taking it to 4 people. That's an annualised professional services cost of $2mm so whatever it is, it's going to be large when(if) it finally happens.
The Authority to proceed of $700k for development in support of a large deployment sets up the Professional Services income nicely for H2 and means there's now a second large deployment in the pipeline.
Cash generated of 3.4mm in H1 takes them up to 23.4mm net cash which is 30% of the mkt cap.
As ever with IGP, the timing of perpetual licence deals is out of their control but the future is looking bright IMHO.
I used to be a holder of these shares for a couple of years believing that growth would be healthy. Ended up selling after several flat announcements and wasn’t too impressed with the leadership when viewing one of their video presentations. The potential is definitely there in current environment, growth should be more aggressive in my view, but not an expert in this space.
ARR is growing by approx 10% pa but it's masked by the volatility in the perpetual licences which depend on government timing. Also, like many companies with mainly government clients, they tend to have a quiet year after a change of government so last year was subject to contract delays as Trump replaced all the senior personnel in the agencies and new contracts were put on hold for 3 months. This year is looking a lot better.