It’s a wrap - which companies caught the eye in January trading statement season?

We have almost completed the surge of trading statements that come out of UK-listed companies in January and early February. Not many appreciate how much the January trading statement season really sets the tone for the year. There’s a saying that “so goes January, so goes the year”, which sums up the idea of the January Barometer - that if stocks rise in January it’s a positive omen. So with the FTSE up 6% in January, a marker is set.
In this piece, I will review some of the announcements that caught my eye in the last few weeks, and I hope you will share some more in the comments. This is especially of interest in the light of the research work we’ve published lately on the predictive power of “ahead-of-expectations” announcements, big price jumps on trading statements days and repeating “ahead” announcements.
Calm before the storm?
The Daily Stock Market Report team has done an outstanding job covering hundreds of trading statements this month. If you look at the chart below, you can see that trading statement season typically lightens up by early February (blue line), before a giant wave of year-end final results hits the wires (orange).
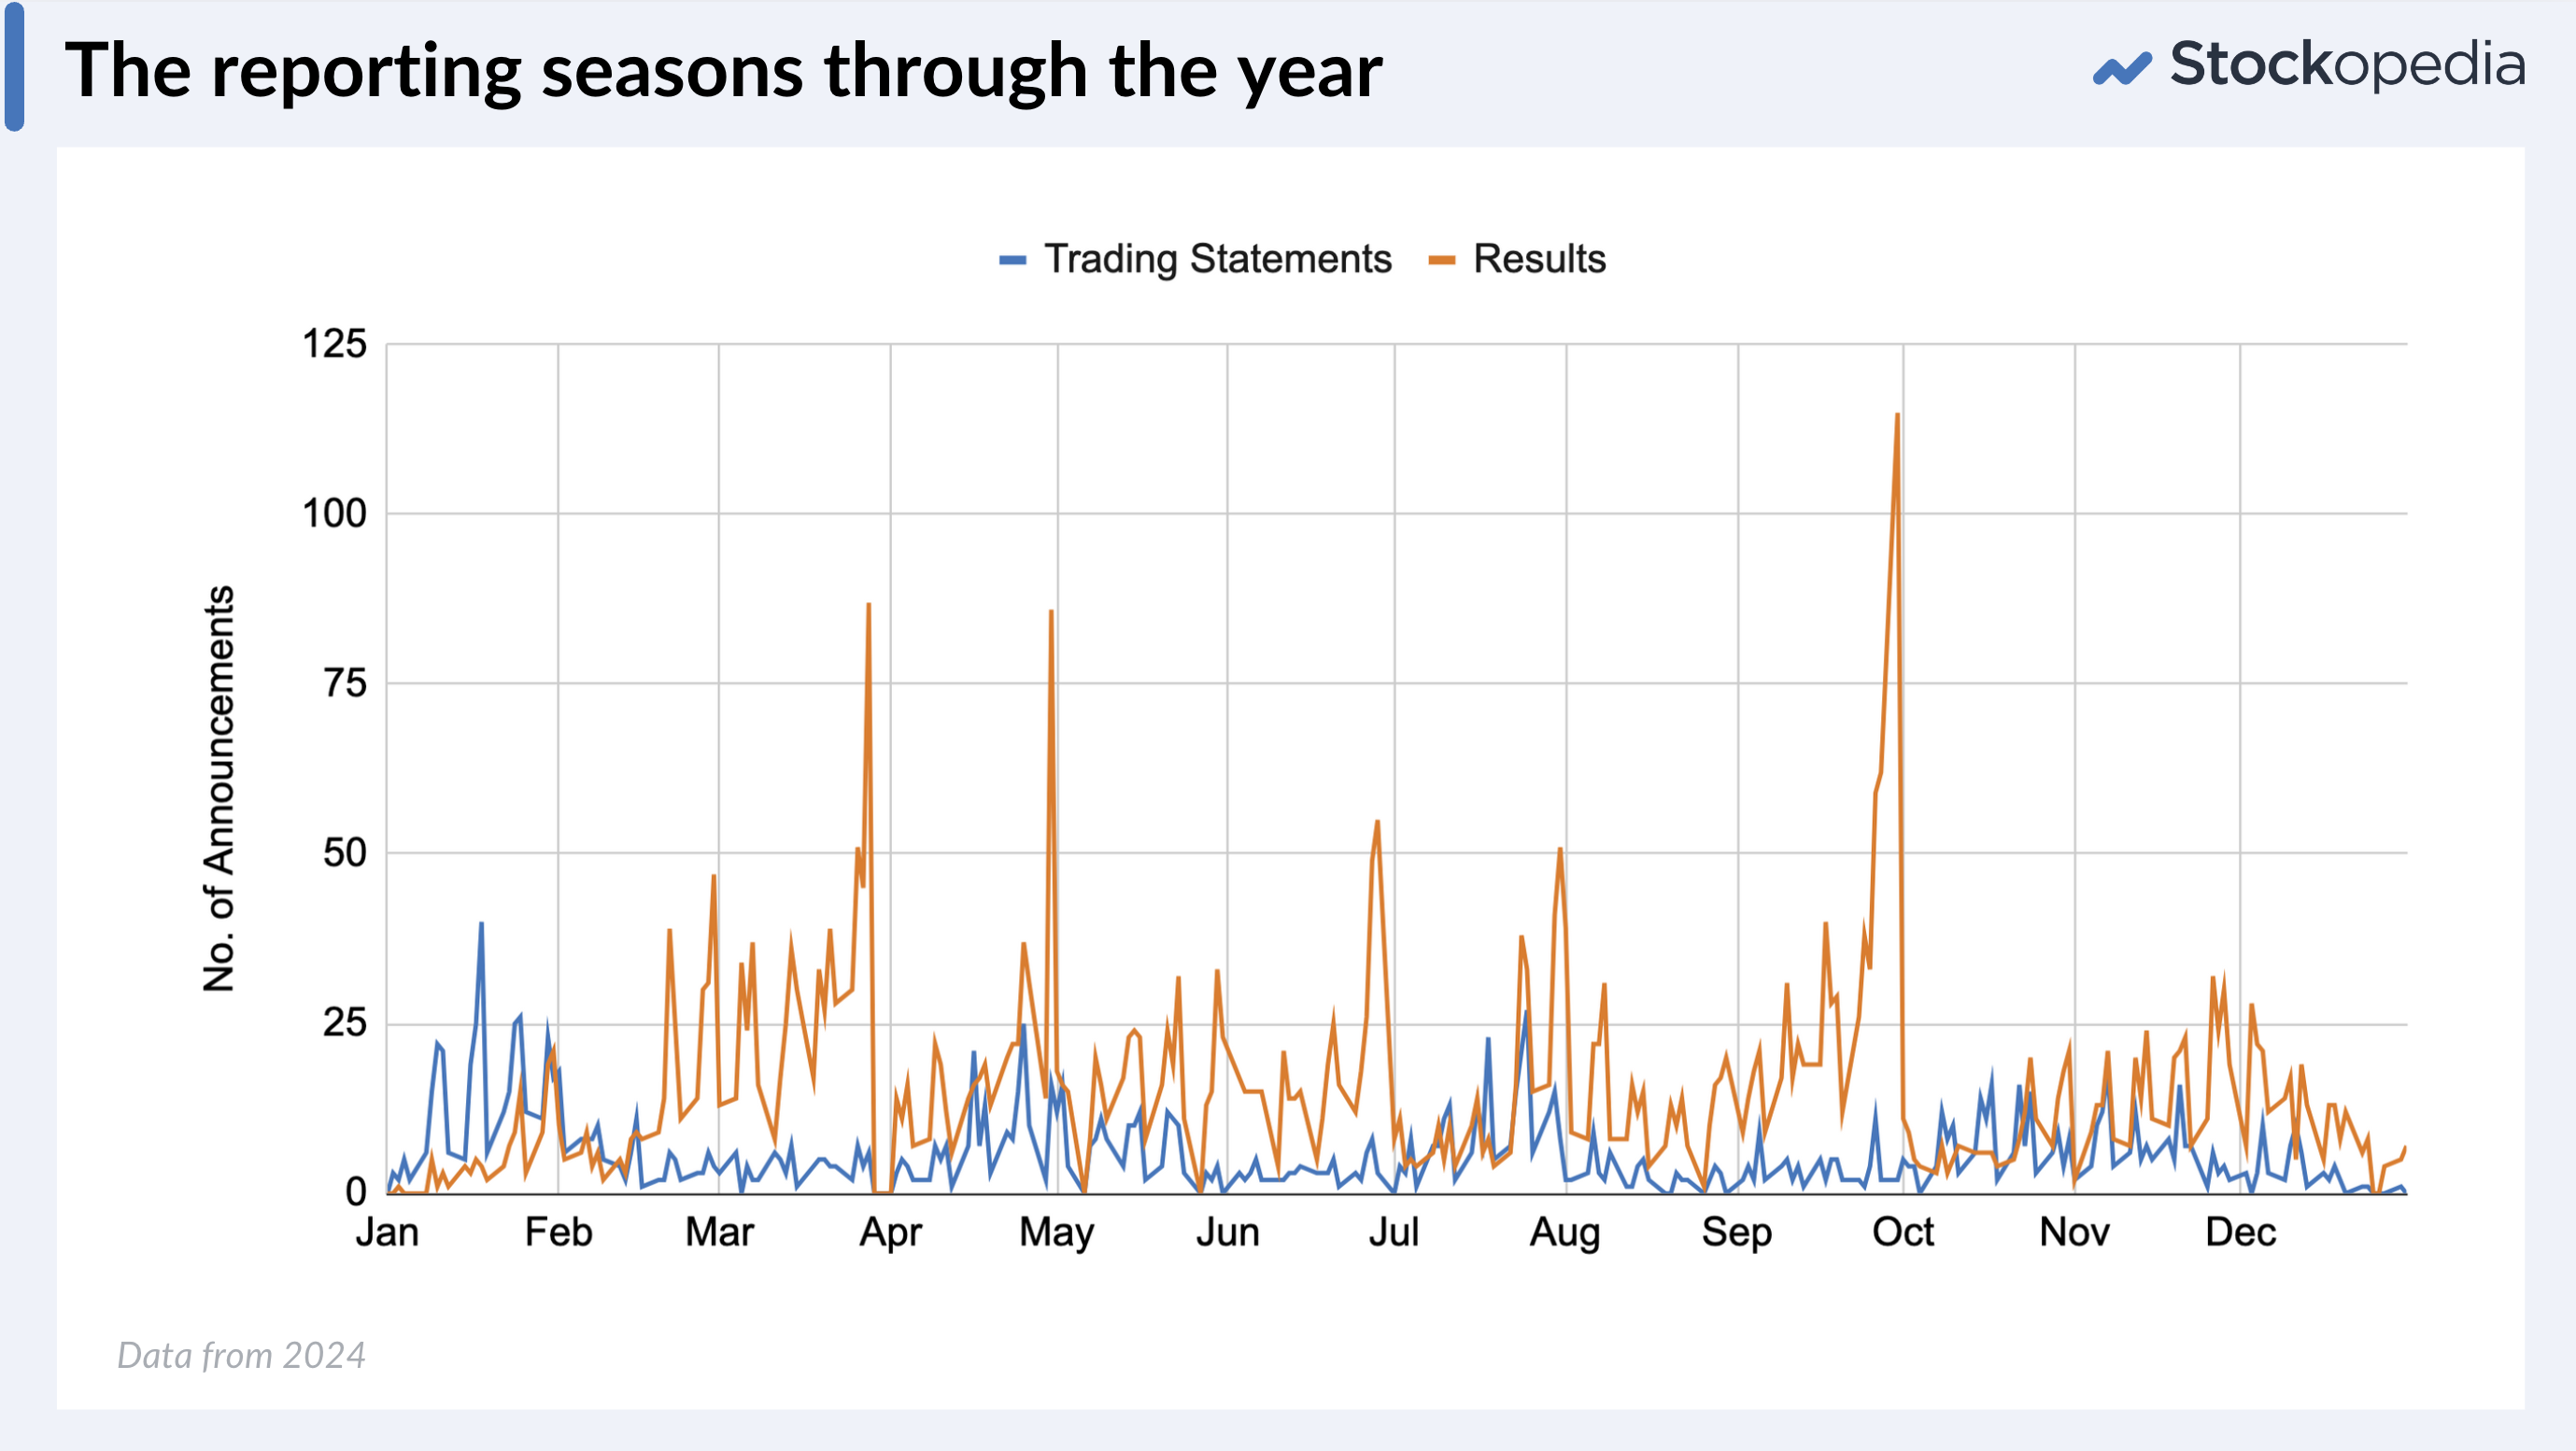
Not every company releases a trading statement, but those that do often state whether they are trading “above”, “inline”, or “below” expectations triggering big share price moves. But results too can surprise on the upside or the downside. Warpaint slightly missed its revenue numbers last week and has been hammered with a 24% share price decline. Results season will bring plenty more surprises, so get ready as it kickß off in earnest by the 21st February.
Trading statements with “big jumps”
A few weeks ago, I outlined the power of announcement-day price “jumps” to predict share price increases in the direction of the jump. We saw some big movements in January. There are too many to list, so I thought I’d pick out a few that caught my eye.
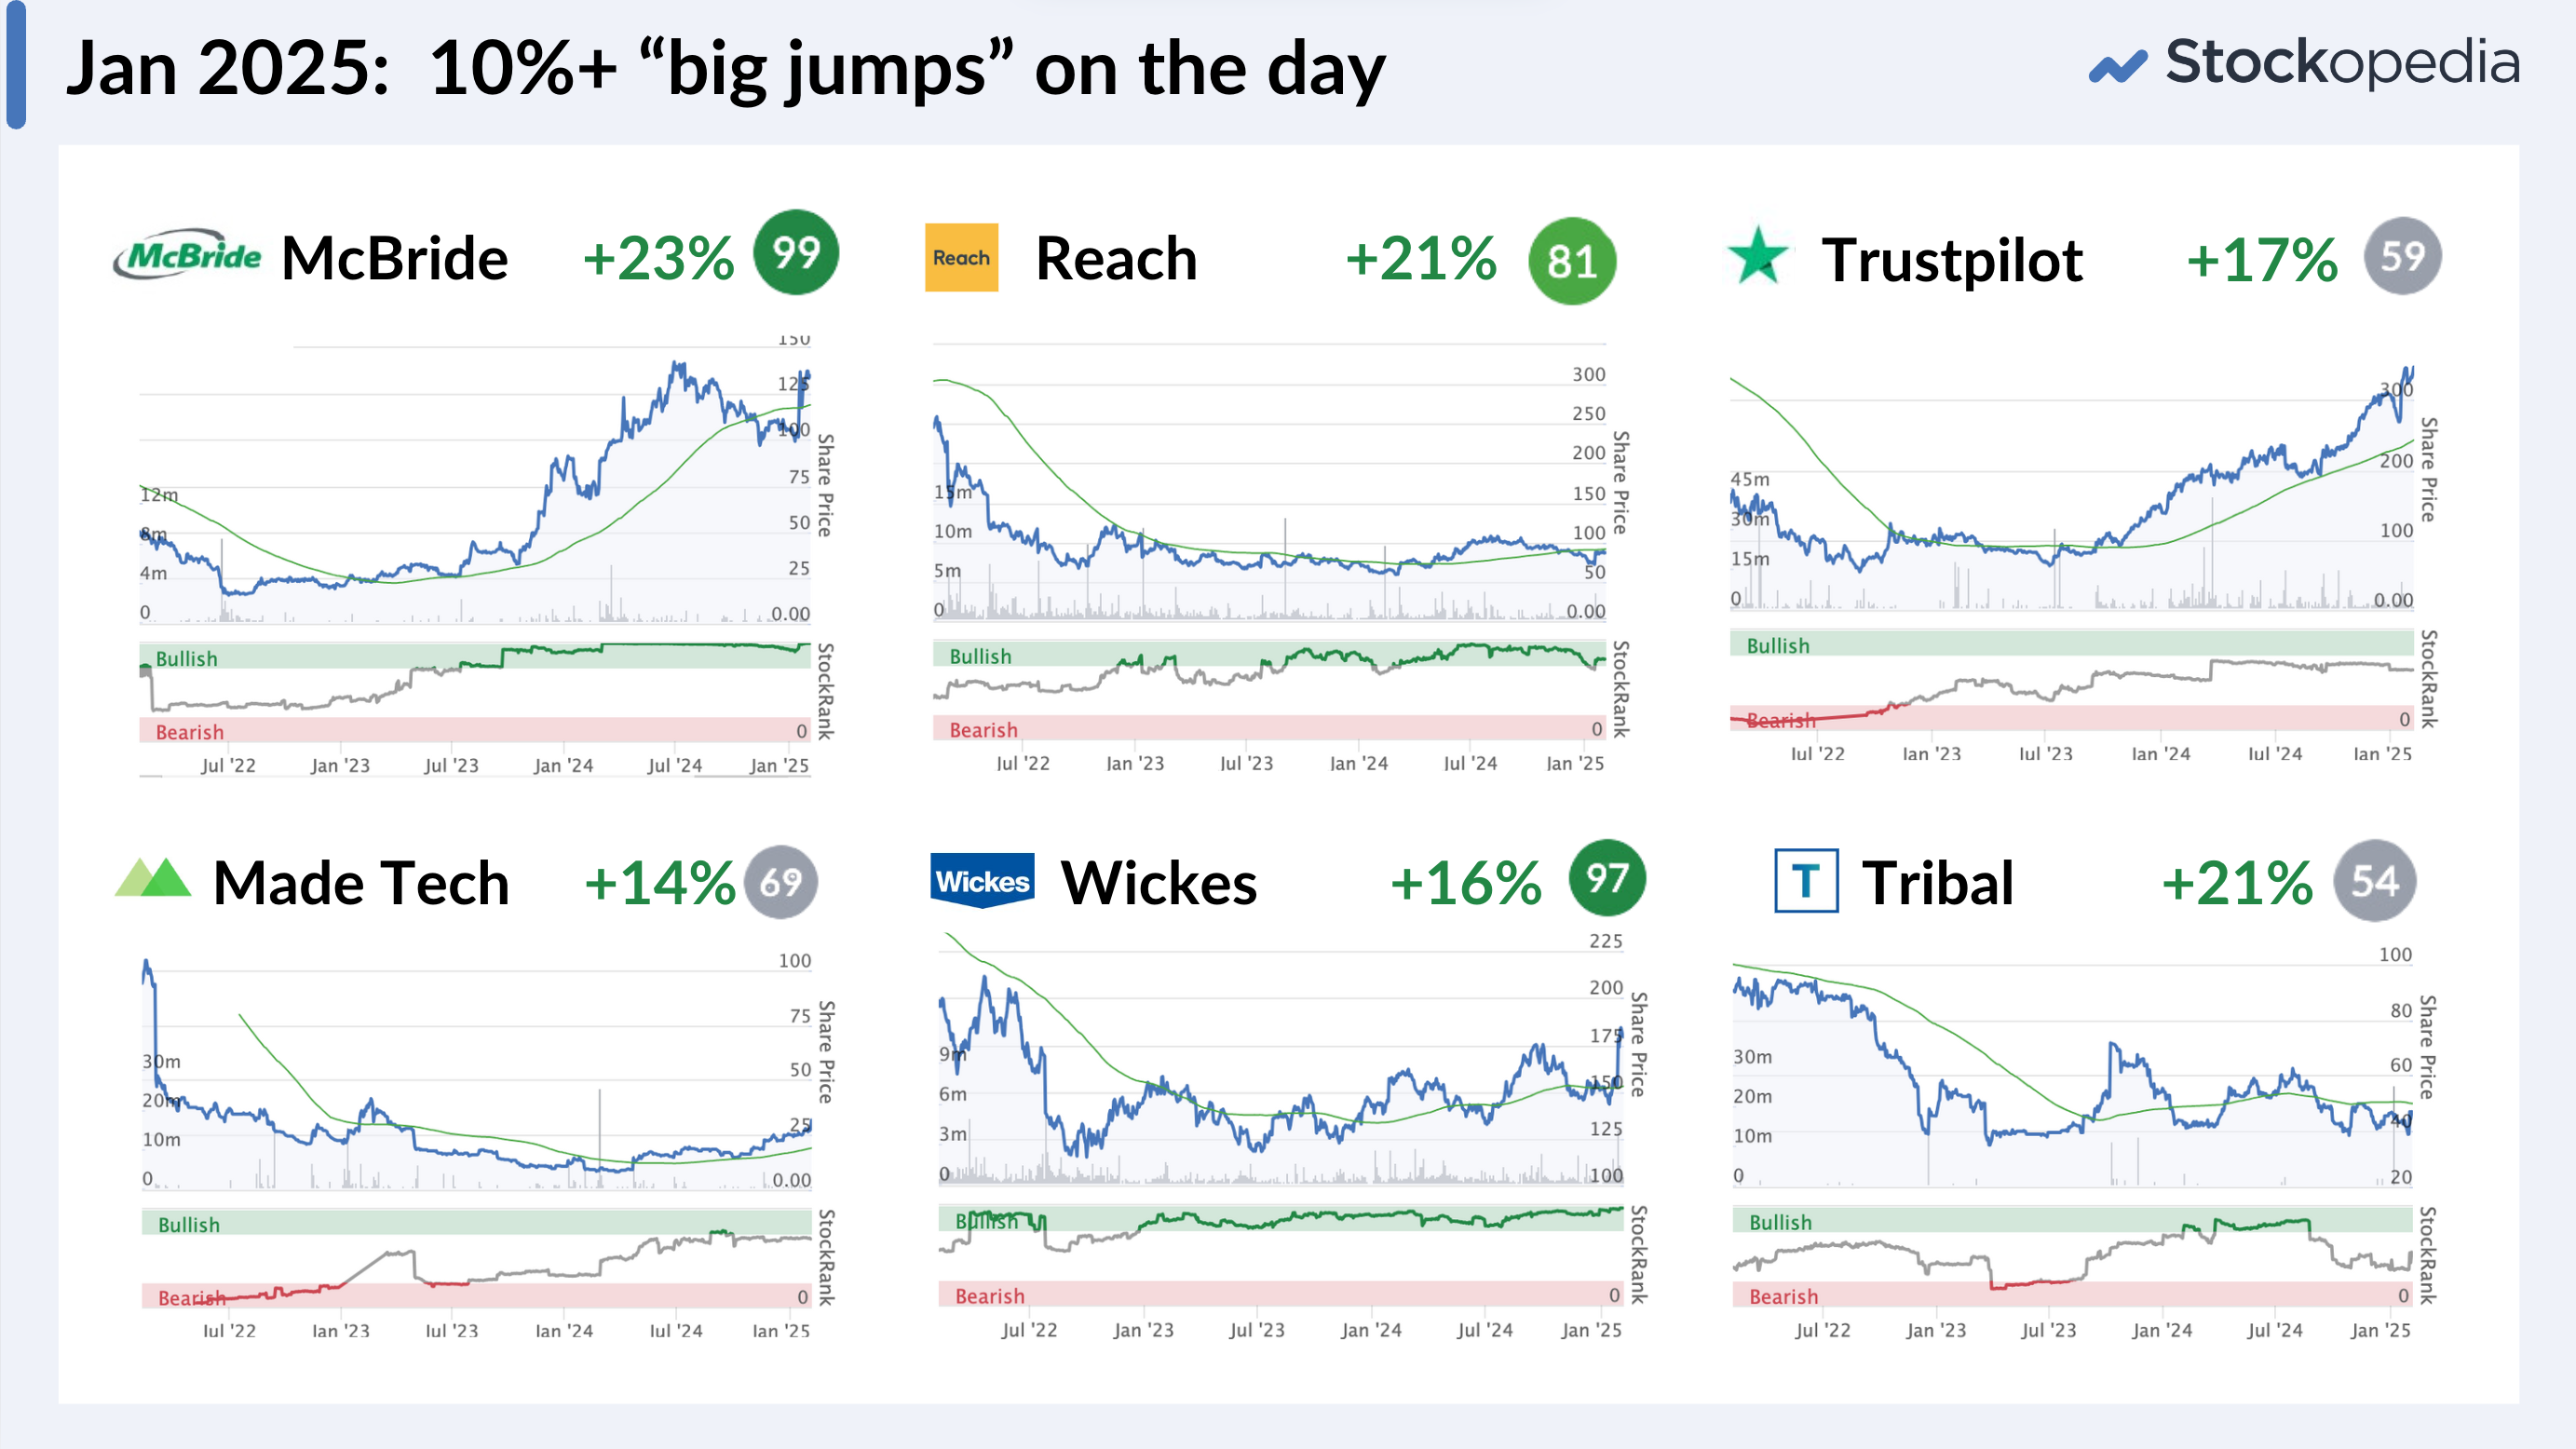
All the charts above are 3-year charts - which helps to see whether share prices have continued momentum or are in recovery mode. I’ve linked to DSMR comments where I can.
- Trustpilot – One of Graham’s standout selections over the last couple of years which jumped 17% on the day. Now on a very premium valuation, but this is a terrific business. We use Trustpilot here at Stockopedia, it has one of the best brand recognitions for company reviews and is growing strongly.
- Made Tech – Benefiting from government outsourcing (more to come there?) and recovering from a very low share price in recent years with a rising StockRank, but the valuation is again punchy!
- Reach (formerly Trinity Mirror) – A former pandemic winner that I four-bagged on back then, using the StockRank 90/70 rule to good effect. This business has a big pension deficit, but does spit off cashflow and always seems to be dirt cheap. The share price goes on a big run every few years for some reason. It reported a strong Q4 last year, which maybe is a sign the advertising environment is improving.
- McBride – A high StockRank winner over the past 12 months that’s released streams of “ahead” announcements. Just as I thought it had run out of steam, it came out with an announcement that reinstated its dividend. When dividends are reinstated, it’s a sign of confidence and often drives a new wave of dividend-hungry shareholders and funds. Hence the pop and now a drift post announcement.
- Tribal Group – A software house in the education sector that had an acquisition rejected at double the share price. An interesting situation, with its main shareholder Janzabar another education software business that’s accumulated a 26% stake. Will they take it over?
- Wickes – A household name with an upbeat forecast and strong jump on the day. High StockRank too.
Repeated “Ahead” Announcements
Many companies have stated they are ahead of expectations this month, but a few say this repeatedly. When “ahead of expectations announcements repeat themselves” it can contribute significantly to share price “drift” in the same direction, and often to multibaggers.
Here are a few of the stocks that have repeatedly told us they are “ahead” lately.
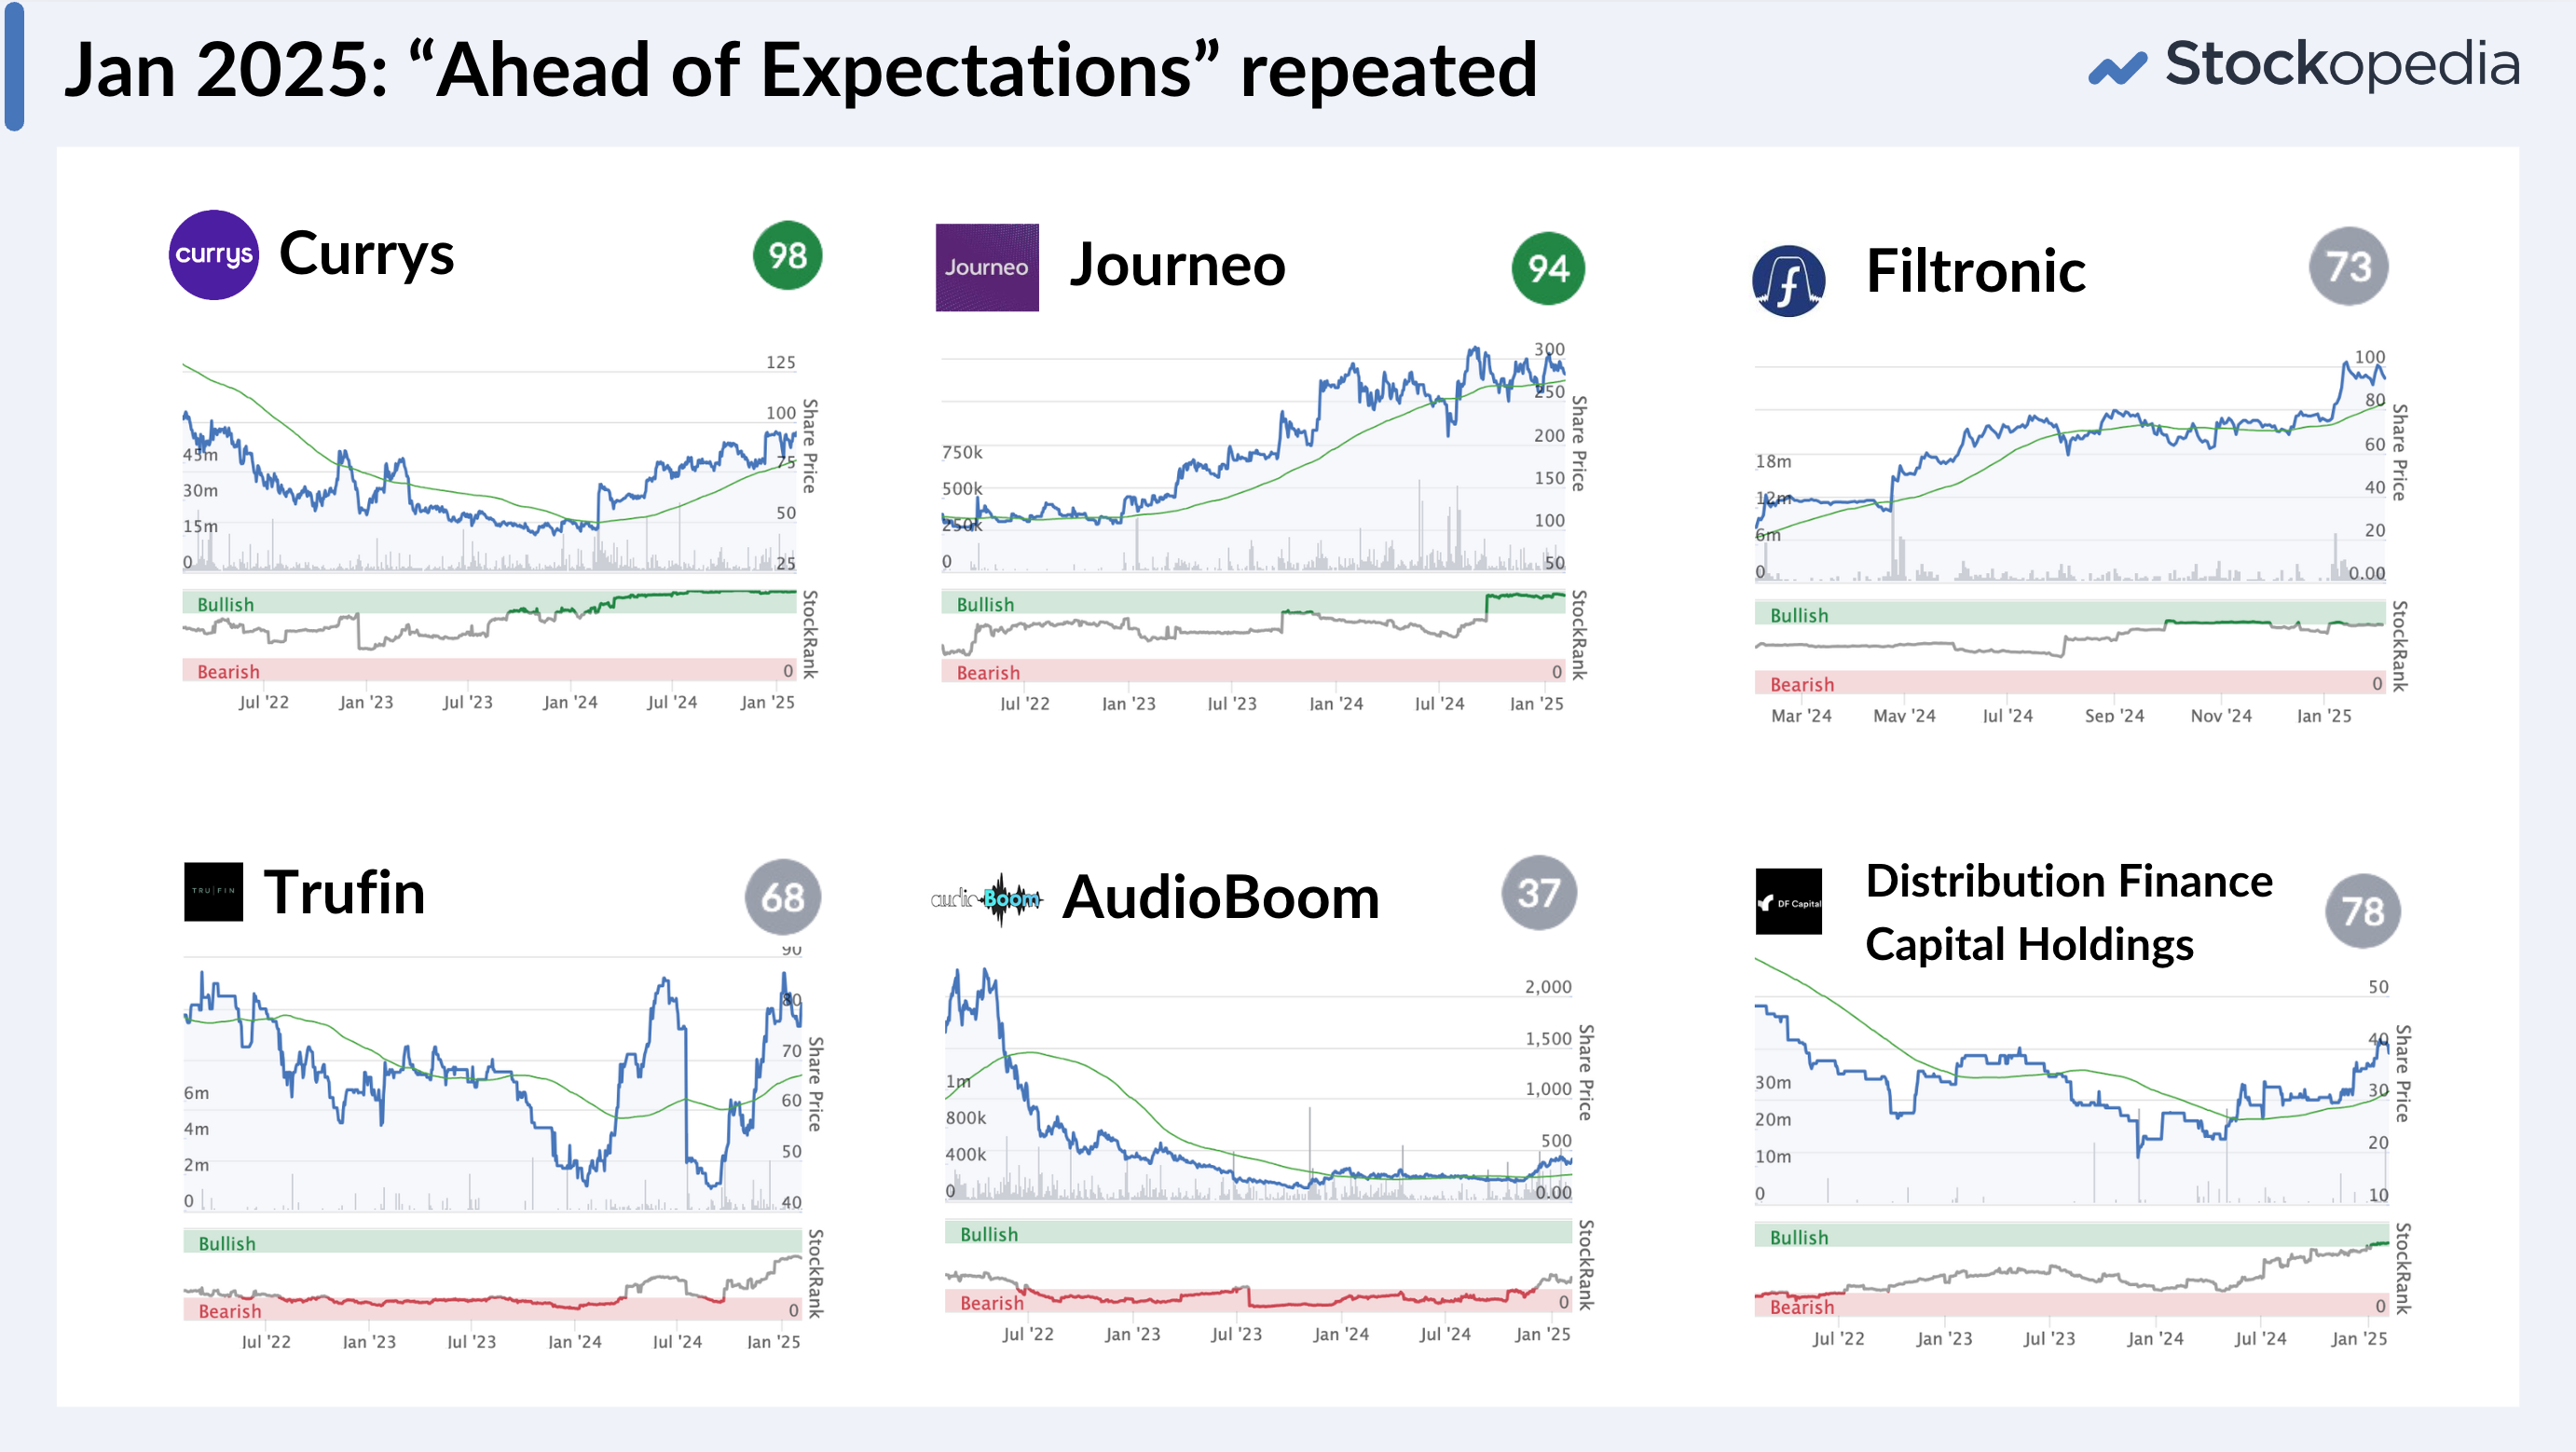
Notable among these are:
- Currys & Journeo – Both in the NAPS portfolio. Currys is maintaining strong strategic business momentum despite a challenging employment environment. Journeo is a small business in bus and rail display tech that is benefiting from the government’s significant green initiatives.
- Filtronic – This has been a powerhouse stock over the last year. It is one of the UK's exciting growth companies, but mostly down to a stream of contracts with SpaceX. The Elon effect perhaps? But it continues to deliver ahead-of-expectations announcements and won another SpaceX contract last week. The large weighting towards SpaceX is not without risk, but the satellite market is growing quickly.
- Trufin – This has reported “significantly ahead” announcements twice in two months. Is the market listening? It’s a complex little business with three subsidiaries. One of them owns the game Balatro, which is top of Apple Arcade and won all kinds of awards. I played it for 8 hours back from Australia on the plane. It seems to be what’s driving the share price - but is one game enough?
- Audioboom – The podcast platform has released “ahead” announcements for the last four consecutive months leading to a 150% share price increase. Low ranked Momentum Trap that has disappointed before, but they are telling us something.
- Distribution Finance Capital Holdings– not a stock I know well, but “significantly ahead” in December and “ahead” again in January. Graham likes the financials sector, and thinks this has some merit.
Profit Warnings
The month has also seen some quite dramatic profit warnings. If you don’t know what to do on a profit warning - I only ever do one thing… sell immediately! As Jim Slater once said “you want to be first in the queue of disappointed enthusiasts”. We’ve done bags of research on this, and for the majority of profit warning stocks, they tend to continue to underperform or just lag. It’s an opportunity cost. Sure some recover, but why fight the odds? Check out the “profit warning survival guide”.
Here are a few notables:
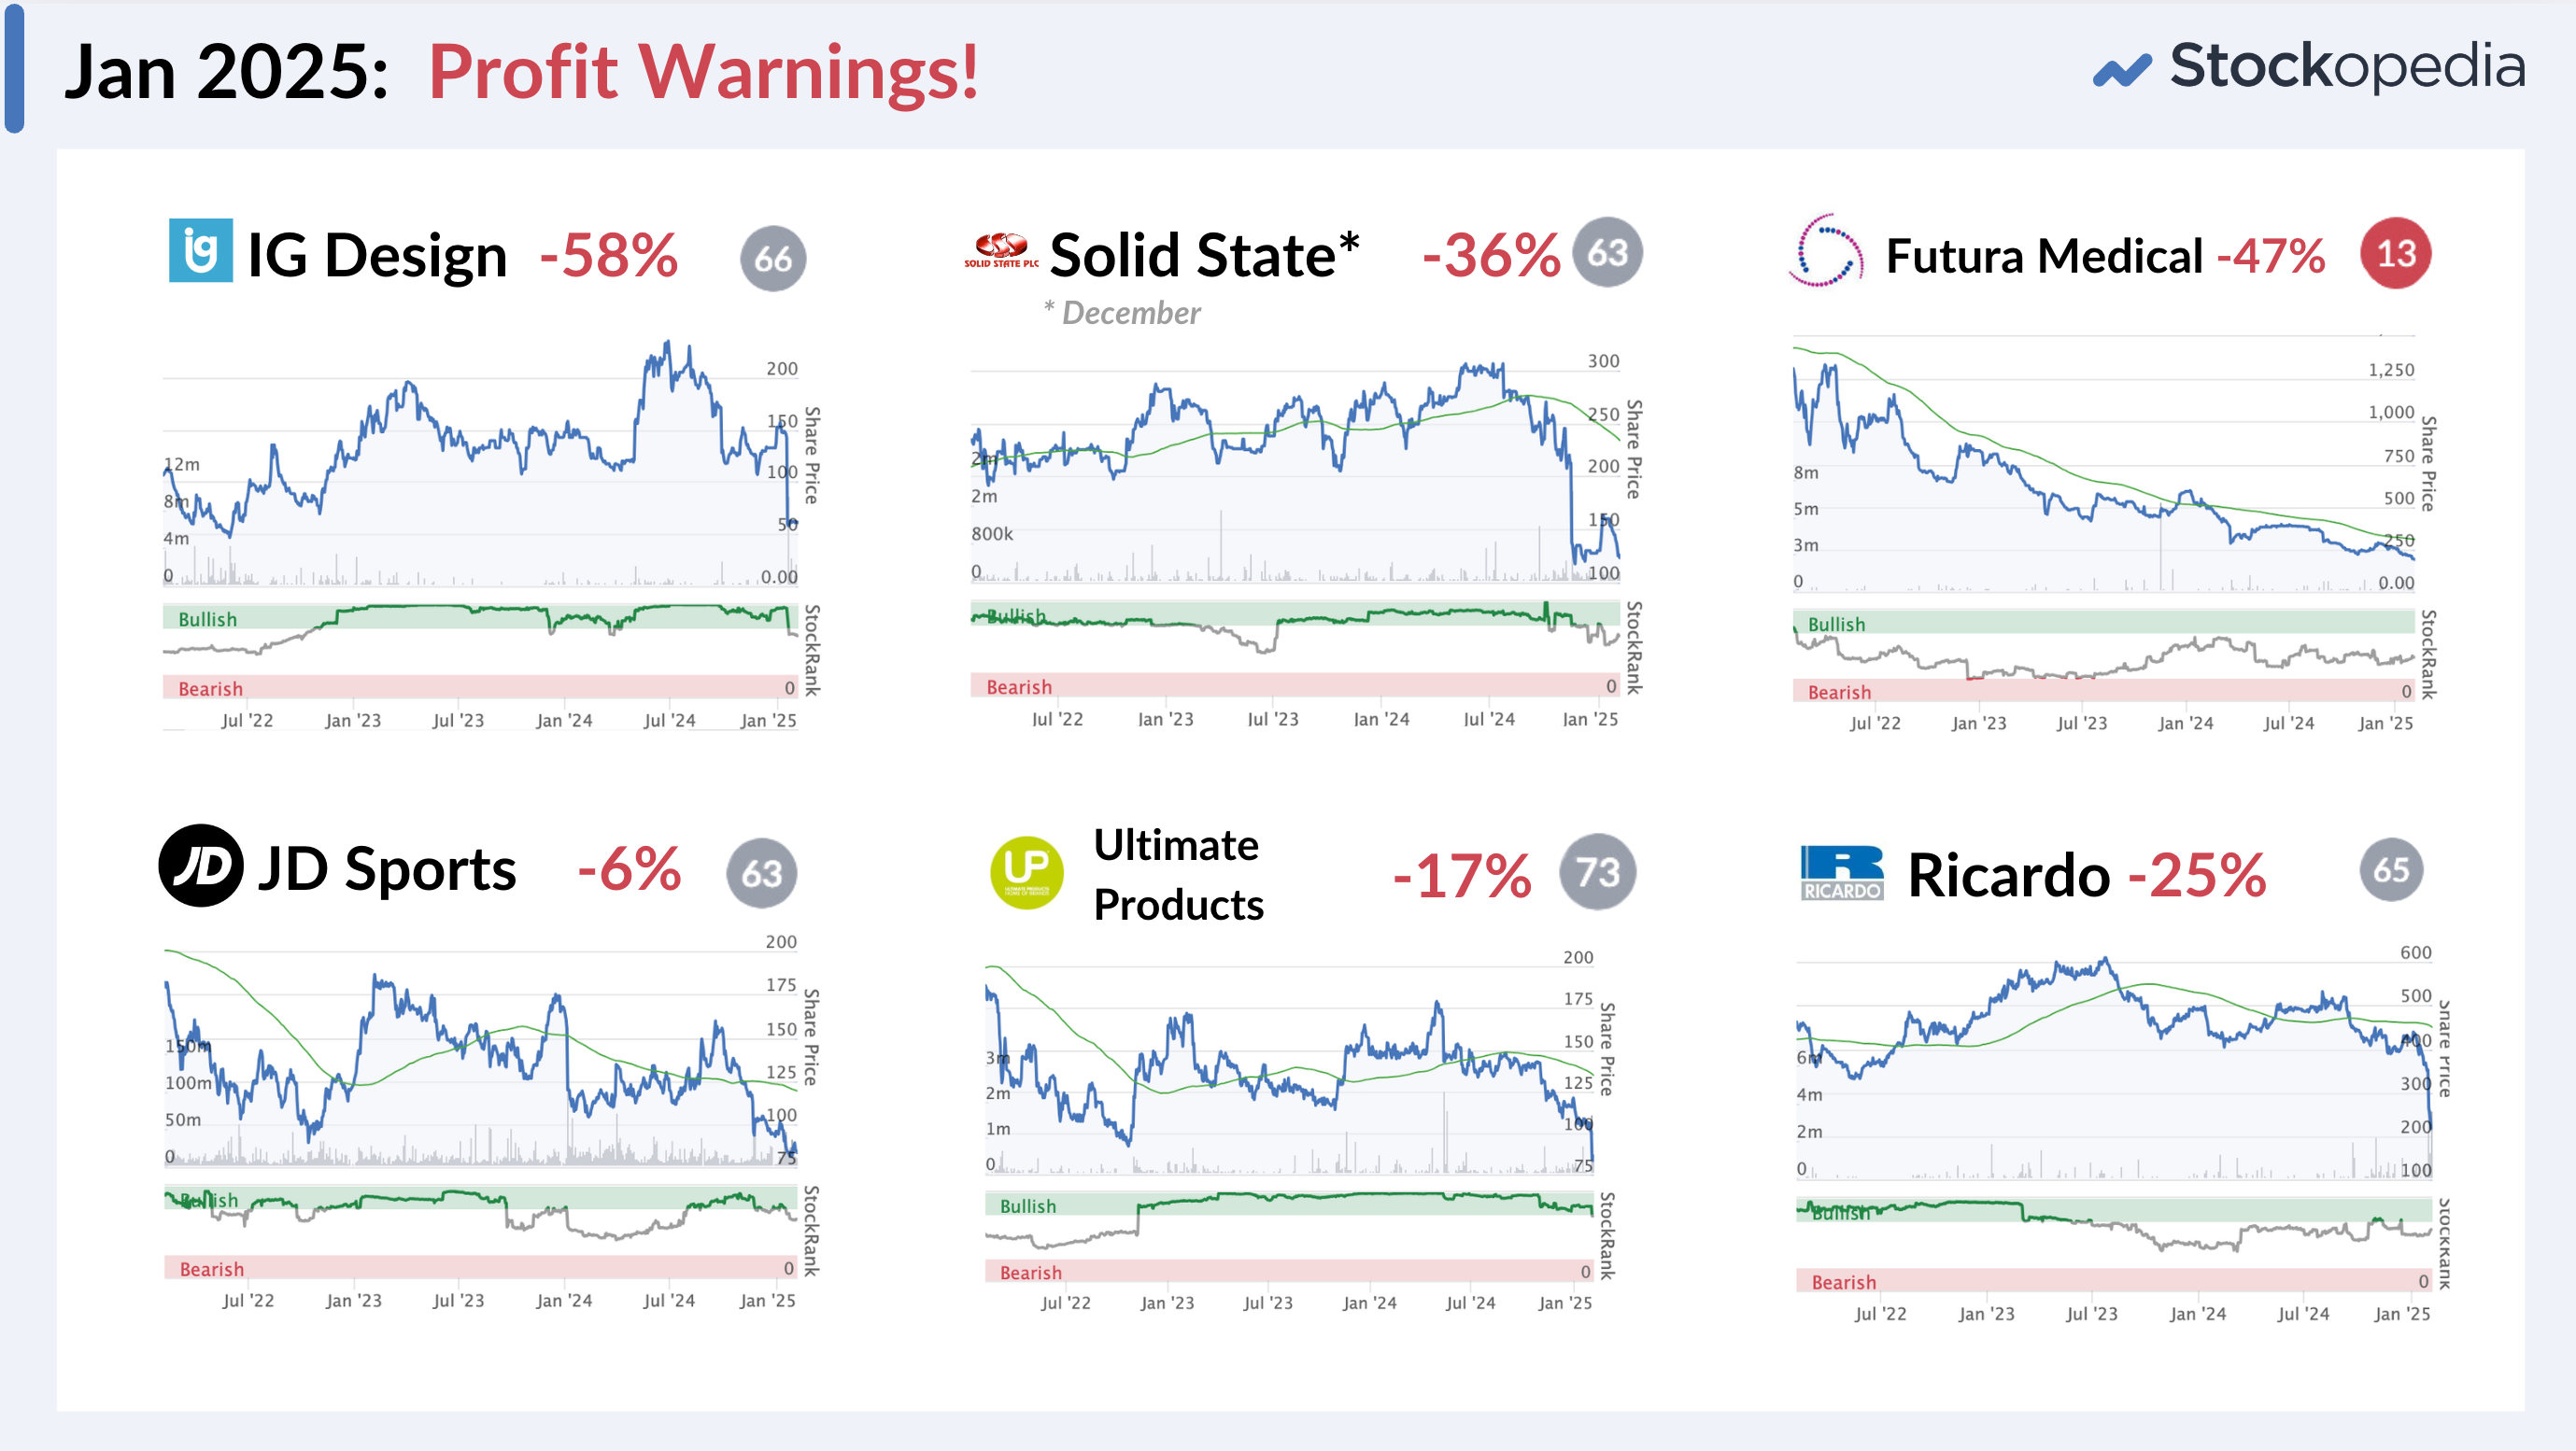
I won’t comment on all.. but:
- IG Design - dropped 58% in a day. It’s the second biggest high-ranked share price fall I’ve seen in a day - the other being DX Group many years ago which fell 65% in a day. Brutal. I’m afraid that’s investing - these things do happen - always diversify!
- JD Sports, one of our top-ten multi-baggers over the previous decade which I highlighted in a webinar and series just over a year ago. I really must follow up to see how this group has done in aggregate since - some doing well like Games Workshop - but not JD. It’s on a profit warning train right now.
What have you spotted?
Now here’s a request to the community, as I’m much more of a data person than a news reader. I don’t read the trading statements every single day, and don’t always get the time to read the DSMR. I’ve missed too much - I’m sure like many of you. So I’m really interested to hear what companies have caught your eye since the start of the year - and what trading statements most excited you? Please do post a comment below naming the company and any thoughts on their trading.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
Worth flagging that the average return to the 12 stocks mentioned in the graphics (after January trading statement season) as having had big jumps or serially ahead announcements are up an average of almost 20% since publication of this article.
Graham and I are doing a webinar on Thursday this week about results season - do sign up.
Excellent results. Will you be doing a refreshed list for this results season?
I don't understand the EPS upgrade screen, John Wood (LON:WG.) is on there but there are no EPS upgrades, they are downgrades and there was a profit warning last week, so why is it on the screen? Quite a few others, are not performing very well, considering all the EPS upgrades.
Elixirr International (LON:ELIX) however, does not feature on the screen.
I see XPS Pensions (LON:XPS) have issued an unscheduled "Materially Ahead" update this morning. This follows an "Ahead" back in October. I am hoping for a decent price jump today from those that recall Ed's articles and are optimistic of another Ahead to come!
I am a long term buy-and-hold investor and have just one new share this year - Hargreaves Services (LON:HSP)
The trigger was that it appeared for the first time on your Multibaggers: Extreme Criteria at Breakout screen on 7th Feb. following Interims on 29th Jan.
A quick look around ticked a lot of boxes for me:
SR 95 (85/64/88) fwd p/e 13.2 y 5.8% p/tang book 1.16.
A green from Roland https://www.stockopedia.com/co...
Comments from Christopher Mills of 28% shareholder Harwood https://www.stockopedia.com/co...
Presentation on IMC https://www.investormeetcompan...
The interesting thing here is that the TU part of the report was simply in line for the full year, but there were noises about all being well beyond that. The clue came from joint broker Cavendish who left current year (to end May) unchanged but raised PBT forecasts for FY26E and FY27E by 17.9% and 5.5% respectively.
So ...I got in at 662.5 and current offer is 671.8 so right direction so far!
I would add regarding your Extreme Criteria at Breakout screen that as I think you said at the time you need to do work on each company and be highly selective. The others I have added from that screen are:
Nichols (LON:NICL) 12/7/24 at 1236p current offer 1315p
Elixirr International (LON:ELIX) 29/8/24 at 639p current offer 770p
MPAC (LON:MPAC) 2/9/24 at 483p current offer 540p
sharw A great spot. I see that the current price is at a new 10 year High reflecting its potential as a “Sum of the Parts” play. Shares magazine highlighted Hargreaves Services (LON:HSP) in its Great Ideas section yesterday….
….The strong first-half results have spurred a round of upgrades to 2026 revenue and earnings forecasts, mainly at the (Earth Moving) Services business, adding to the medium term valuation upside. The company is moving to a capital-light model, which means no acquisitions and no equity raises, and as it already has a net cash position it will start returning surplus capital to shareholders.
Having taken your links and news into account I initiated a position at the open.
I mentioned Elixirr International (LON:ELIX) in my comment. Somewhat behind the pack it has put out its year-end trading statement today, which is 'ahead'. That = just ahead - Cavendish previously had revenue £109.5m and adj. EBITDA £30.4m - now "greater than £111m" and "approximately £31m".
Market reaction has taken the SP to an all time high so that is another thumbs up for Ed's screen.
Fantastic article as always Ed - Would you be able to create a feature to save articles to review and remind ourselves about key concepts?
Hi Ed, thanks for this article and the associated webinar. I'm really enjoying these new and insightful ways of looking at the performance of shares. It'd be wonderful in the future to somehow have these kinds of insights embedded into the stock reports and screens.
My current favourite is Synectics (LON:SNX) which was inline on 24 April 2024, comfortably in line on 04 June 2024, materially ahead on 16 September 2024, and then materially ahead again on Dec 9, 2024.
Your research around PEAD has underpinned my confidence in the investment case for Synectics in the medium term although the nature of the business may be towards large and lumpy contracts so I'll be keeping my eye out for the waning of the PEAD over the coming months.
Interestingly the clue was given in June with the "comfortably in line" update which did little to move the share price. Astute investors who spotted that tip would have pretty much 1-bagged since then.
I'm keeping my fingers crossed for a third in the series of materially ahead updates.
Thanks Johnsmith68.
Synectics (LON:SNX) was one of three tech firms highlighted in the small cap clear trends work I did last year - along with Concurrent Technologies (LON:CNC) and Filtronic (LON:FTC) - they've all been doing well since. Streams of ahead announcements bodes well !
Yet another great subject matter Ed
On the upside, Alumasc (LON:ALU) , Concurrent Technologies (LON:CNC) , Anpario (LON:ANP) and Filtronic (LON:FTC) all put out positive updates ( I hold all) and you can foresee market expectations being beaten this year by all of them. The market responded accordingly.
On the flip side Warpaint London (LON:W7L) put out a very belated market update (compared to its practice in previous years) and the numbers on the face of it didn't seem too bad.
But once digested those numbers did not fit for a business with such a high PER and the manner and tone of the update left an awful lot to be desired.
Someone like Ed should use this example to write a book about how not to behave when interacting with the market ! The market response seemed brutal but you have to wonder that it wasn't just due to the numbers. The credibility of the management and their advisors have taken a massive hit. I can see also further adverse market updates to come for sure. Unfortunately I also hold ! Cest la vie !
Hi Ed. In addition to some of those already mentioned by others -
Everplay (LON:EVPL) trading slightly ahead of forecasts with the share price up 12.5% on the day. The share price has drifted downwards since the trading update was issued on the 23rd January.
Frontier Developments (LON:FDEV) up 24% on the day but now down 11%, since. Intercede (LON:IGP) is another, up 10% but now fallen back Staffline (LON:STAF) up over 20% but given half back now.
It is interesting that Frontier Developments, Intercede, and Everplay all made their highs on the day of their trading update in the 1st hour of trading, and Staffline only surpassed the 1st hour high by 10p. Maybe the market makers pushed the price up too much and there was no demand. Maybe we should be looking for shares that demonstrate momentum on the day of the trading update as well.
That's a great suggestion DLTTWTG... Although it will never be possible to produce a fool proof system ( which some seem to expect ) or else we would all be sitting on our own private islands... many thanks indeed Ed for yet another excellent article...
Interesting, but not sure if it is market makers or just holders selling out. But these are based on the closing prices, on the day of the update, so they are all quite large risers, on the day.
Seems to be a lot of profit taking, on the big risers, on subsequent days. Fevertree Drinks (LON:FEVR) fell back around 12%, seemed like a good deal to me.
That's a good idea @Tailwagdog - for further research. I do have the gaps data, but we don't store much intraday pricing data. I also want to research whether already upward trending stocks that have good announcements are more likely to show drift than those in sideways trends.
Hi Ed
There are several shares I would like to buy but as I am nearly always fully invested I need to sell first, which is often a problem.
Anyway stocks that I have recently bought or added to, often for different reasons are:
Bought: Zotefoams (LON:ZTF) Reason: ceased investing in Rezorce. New CEO. Management can now focus fully on the core business that is trading ahead of expectations, albeit slightly The shares remain too cheap for a company that owns excellent technology and is trading strongly.
Bought: WH Smith (LON:SMWH) Reason: Not dissimilar to Zotefoams. The company has announced its decision to explore the sale of its high street stores and focus on its travel business, which accounts for 85% plus of profits and is trading well. Assuming it is able to sell its High Street presence, which is a drag on performance, management can focus fully on the growing travel business. The proceeds from any sale may be returned to investors, used to reduce debt and/or invested in expanding the travel business, probably a mix of all three. The company is trading well and has recently commenced a 50m share buy back program. Again given the potential the shares look too cheap.
Bought: Premier Miton (LON:PMI) Reason: Like all asset managers the company has struggled given the outflows from UK equity funds. However the recent trading update disclosed that AUM had stabilised. The shares currently yield more than 10% with the dividend covered by earnings. The company has £30m or thereabouts on the balance sheet which is 33% or so of its market cap. Graham makes the point that for £1 invested in the company one is getting £120 plus of assets under management. Additionally Interest rates are falling, which is positive for equities, so excepting Armageddon the shares are just too cheap. Forward PE 8.75 and 10.5% yield
Added to: Ramsdens Holdings (LON:RFX) Reason: My favourite way to play the gold price that has been on a tear for the last 12 months or so; currently above £2300/ounce. This is a significant tailwind for the company, in terms of precious metal revenue and profit. The company is trading well with revenue and profit also increasing, albeit more slowly at the other three 'divisions' FX. jewellery/watches and pawn broking. Forward PE 8.9 and 4.8% yield. I like the management under CEO, Peter Kenyon who holds 3% of the shares. The shares have been gaining momentum of late as a consequence of the gold price, I would suggest. My blended purchase price is around 217p. Again given the above and continuing strength of the gold price I think that the shares are currently too cheap.
Just my view as always.
All the best
jonno - excellent write up - I'll say thanks from all of us for sharing your reasoning !
Have been tracking this, so highlights (other than those already stated) are: Anpario (LON:ANP) up 12% on 10/1 up 10% since, Genus (LON:GNS) up 23% on 15/1, up 6% since, Concurrent Technologies (LON:CNC) up 12% on 16/1, up 23% since, Mortgage Advice Bureau (Holdings) (LON:MAB1) up 15% on 23/1, up 23% since, Luceco (LON:LUCE) up 13% on 23/1, up 9% since, Iqe (LON:IQE) up 7% on 23/1, up 19% since, Brave Bison (LON:BBSN) up 3.5% on 24/1, up 18% since, Staffline (LON:STAF) up 29% on 4/2, down 10% since, James Fisher And Sons (LON:FSJ) up 8% on 5/2 , up 5.8% since. All these beat market expectations, apart from Genus who said profits would be at the top of range of market estimates. Its a shame I hadnt tracked this previously as I may have bought more of these shares. Looks like I will have to wait until April for another flurry of trading statements.
Mortgage Advice Bureau (Holdings) (LON:MAB1) l have that up 24%, after the TU 23/1/25. I have McBride (LON:MCB) up 16%, l thought was 125p at the close of the update day?
I have quite a few in a folio, overall very flat, Ashtead Technology Holdings (LON:AT.) fell back quite sharply after the update, so have several others.
Graham deselected Trustpilot (LON:TRST) from his portfolio this year, his replacements are not performing so well.
Yesterday Wynnstay (LON:WYN) jumped nearly 10% on the release of results and at the time of writing is up another 2.6% today on heavier than average volume which is possibly an example of early stage PEAD. This was covered positively (GREEN) in the DSMR main content yesterday and in subscriber comments. Despite a bad year for a variety of external reasons and some business units underperforming, cash flows were still considered good enough to raise the dividend. It has a good balance sheet. This isn't a classic case of continued momentum but could indicate a turning point towards a recovery in the share price. Time will tell.