IXICO: £2.7m contract win signals credibility and underpins forecasts

Analyst’s view:
This contract helps to underpin current forecasts and support the recovery of IXICO's order book following £1.5m of contract losses last year. I'm taking a neutral view today because I haven't done the research needed to form a conviction on this loss-making and specialised business, but my initial impression is that IXICO might be worth further research for investors with an interest in this sector.
Up 25% at 14.8p (£33m) - £2.7m clinical phase 3 contract win
IXICO describes itself as "a global leader in neuroscience imaging and biomarker analytics, using its AI-driven platform to help advance drug development and diagnostics in neurological disorders".
Contract win: today's share price jump has been triggered by news that IXICO has won "a global Phase 3 clinical trial contract in Huntington’s disease (HD) with an international biotechnology company."
The contract is expected to generate £2.7m in revenue over the next six years.
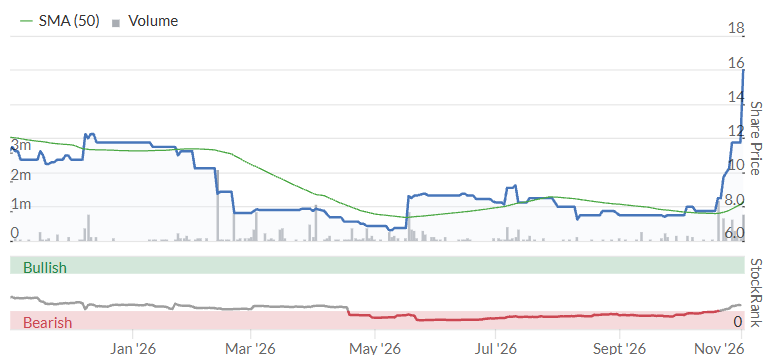
What it means: today's contract win announcement appears to have been seen by investors as an important indicator of the credibility of the company's offering in the Huntington's disease market.
While forecasts from house broker Cavendish are unchanged today, this win should help to underpin current expectations and support the rebuild of IXICO's order backlog, following the cancellation of £1.5m of programmes earlier this year.
A winning streak? Today's win is the latest in a series of positive news from IXICO:
20 Oct 26 - Trading Update for y/e 30 Sept 26: revenue rose by 28% to £8.3m last year and is expected to support a reduced EBITDA loss versus previous guidance of £(1.7)m. The company also reported an improved order book of £16.0m (FY25: £13.8m) and year-end cash of £10.4m, following a £9.4m capital raise in April 2026.
22 oct 26 - Alzheimer's Contract Wins: IXICO reported two wins with separate clients with a total value of £1.5m, to be recognised over multiple years. These wins relate to neuroimaging services the company is providing for Alzheimer's Disease diagnostics and clinical developments.
Outlook & Broker Estimates
In a note available on Research Tree today, IXICO's broker Cavendish leaves forecasts unchanged but says it will update estimates when the company's FY26 results are published in December.
As things stand, the business is expected to remain both loss-making and cash-burning in FY26 and FY27 (y/e 30 Sept).
FY26E adj EPS: -1.4p
FY27E adj EPS: -1.3p
Roland's view
This isn't a business or a sector that I know very well. However, there are a few points I think are worth considering when reviewing IXICO as a potential investment.
Firstly, this isn't purely a blue-sky business with no track record. IXICO was founded in 1995 and has been listed since 2013. It has a track record of revenue generation and has been profitable (at times) in the past:
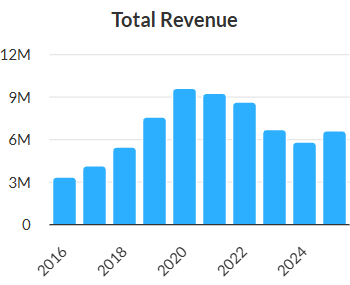
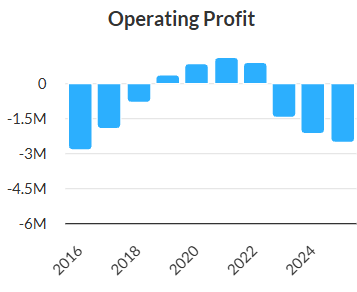
I don't know the story behind the company's previous growth and decline, so tracking back to these years would probably be my first step if I was interested in investing. I'd want to know if the business model has remained consistent or pivoted and whether the company has historically been able to deliver on its plans.
My next step would be to take a closer look at cash burn and fundraising in recent years. The FY25 cash flow statement showed net cash outflows of c.£2m. If this remains a meaningful guide, then the c.£10m cash balance reported recently could underpin operations for a number of years without further dilution.
I think IXICO has a reasonable record in terms of fundraising. Shareholders have only been diluted twice in the last decade, although the share count has tripled over this period:
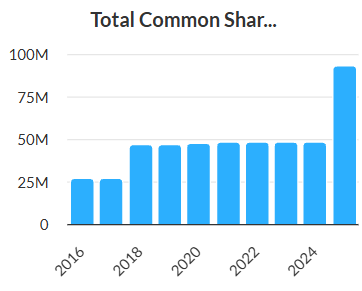
In my view, fewer, larger raises are generally better for investors. They're also a sign management is confident and commands some respect from key investors. IXICO has a relatively impressive shareholder base for a business of this size, with a number of well-known institutions.
Valuation is always difficult for a loss-making company, as we can't be sure the business will ever scale sufficiently to reach profitability. It's for this reason I'd start by trying to understand the business model - what's the potential opportunity?
What we know today is that the shares are trading at around 3.5x FY27E revenue and around 28x historic peak operating profit (from FY21).
I don't know if this profit figure will be repeatable in the future, but if it is, then I might conclude that the current valuation is not completely unreasonable.
I'm going to take a neutral view on IXICO today because I haven't done the research needed to form a conviction on this loss-making and highly-specialised business.
But based on what I have seen today, I'd say that this business might justify further research for investors with an interest in this sector.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on IXICO (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?