JD Sports share price dips as profit guidance cut, cash flow hints at opportunity

Analyst’s view:
Today's update nudges profit guidance lower, but my number crunching suggests that this was already priced into analysts' forecasts. The opportunity is that JD will return to growth and enjoy a re-rating. The risk is that momentum still seems weak to me. I'm staying neutral.
Down 3.5% to 91p (£4.3bn) - Q3 2026/27 Trading Statement
When is a profit warning not a profit warning? In today's third-quarter update, JD has narrowed its profit expectations for the year to the bottom half of its previous guidance range.
The company now expects adjusted pre-tax profit for the year ending in January 2027 to be between £700m and £750m, compared to £700-800m previously. Fortunately, free cash flow guidance of £460m to £520m is unchanged.
I don't think we need to classify this as a profit warning, but it's definitely a sign that trading remains challenging.
The summary of regional sales performance today suggests that JD is facing headwinds in all of its main markets. Geographic diversification doesn't seem to be helping very much:
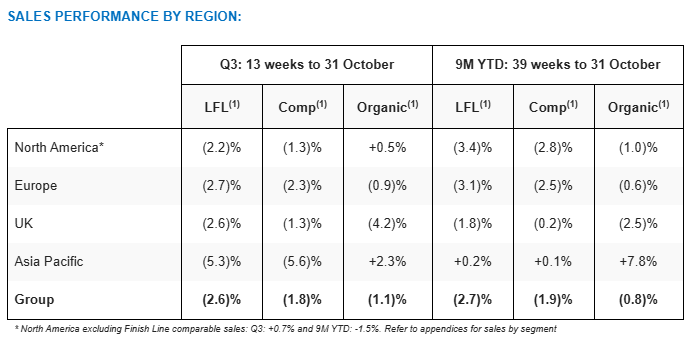
Management commentary suggests footwear continues to be the main area of weakness, with "resilient sales trends in apparel and accessories". As I've commented before, I think softer footwear sales are tied into weak performance at NIKE (NYQ:NKE) - the US giant generates around 40% of JD's sales.
Geographically, the company says that comparable sales (an alternative LFL measure) improved in North America during Q3, falling by just 1.3% (vs Q2 -6.0%). This is said to reflect back-to-school demand and the popularity of "performance-based running".
In the UK and Europe, demand was softer in Q3 following stronger sales during World Cup period in Q2. Sales in the outdoor business (e.g. Go Outdoors in the UK) were also said to remain positive.
Profit margin: JD says that gross margin for the third quarter was in line with expectations, but it doesn't say what those expectations were or how they compared to H1. However, the company does say that it made "controlled price investments in Q3 to remain competitive" . Clearly discounting remains necessary to maintain sales volumes.
Outlook
Narrowing FY27 profit before tax and adjusting items guidance range to £700m to £750m (from £700m to £800m); free cash flow guidance unchanged at £460m to £520m
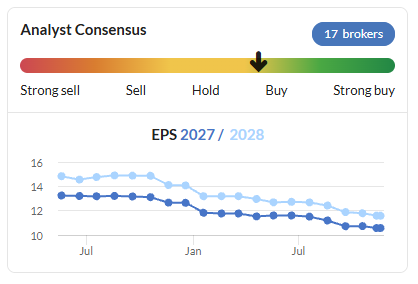
Reverse engineering the latest consensus EPS estimates on the StockReport suggests to me that analysts were already forecasting full-year profits towards the lower end of the £700-800m guidance range. For this reason I don't expect big cuts to forecasts today.
This is probably reflected in the lack of share price movement this morning - JD's stock is only down by 3% as I write.
Roland's view
Checking back through our archives, JD issued a profit warning in August. This was followed by an in-line set of half-year results in September. At the time, I noted the possible correlation with Nike's weak performance.
Interestingly, the two companies' share prices have diverged this year, after moving in lockstep for most of the last decade:
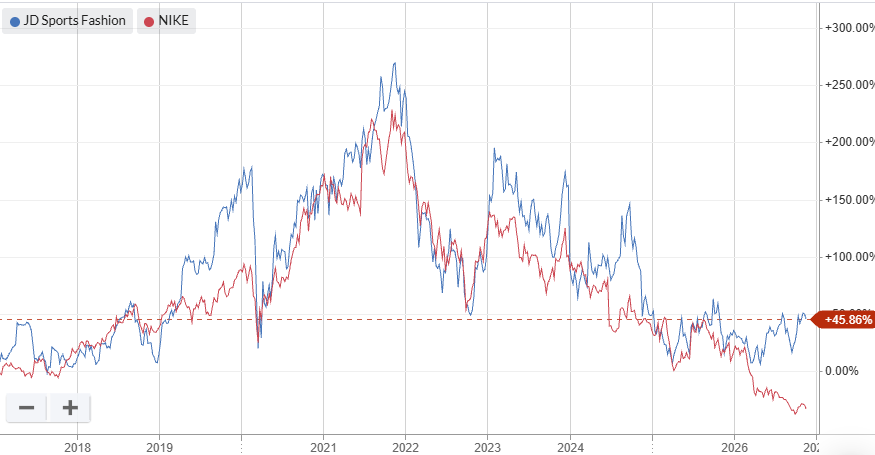
We'll have to see whether this divergence continues or if the two companies' fortunes remain linked.
From my perspective, it would be good to see JD reduce its dependence on a single supplier, but I'm not sure how feasible this is. Newer challenger brands such as On and Hoka, that have taken share from Nike, don't seem to depend so heavily on store-based sales.
Our algorithms view JD as a Super Stock, at least prior to today's update. To my eye, the StockRank factor profile is closer to that of a Contrarian, with high quality and value scores but weaker momentum. The attraction here is that any improvement in momentum could prompt a re-rating from JD's current single-digit P/E:
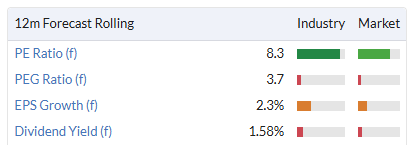
It's also worth emphasising that free cash flow is expected to remain strong. Taking the midpoint of today's £460-520m guidance range implies a forecast free cash flow yield of 11%. That could be cheap if it's sustainable and might support further buybacks or more generous dividends.
The risk is that this momentum will remain lacking, as suggested by today's trading update. That could leave JD running to stand still, justifying a low valuation.
On balance I think it's fair to leave my previous neutral view unchanged today. While this may be too cautious, I'm conscious of the broad-based weakness of JD's sales and the possibility that a turnaround could still take some time.
With only a minimal dividend yield, investors don't get paid for waiting and face an opportunity cost compared to more compelling opportunities elsewhere.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on JD Sports Fashion (5)
Comments here are also visible in the Daily Stock Market Report
JD Sports Fashion (LON:JD.) looks like a profit warning to me, with profit guidance narrowed to the bottom half (£700-750m) of the previous guidance range (£700-800m)...
Still within the guidance, so not sure it would be classed as a profit warning.
Re JD Sports Fashion (LON:JD.), point taken bsharman! But sounds a bit like getting off on a technicality to me! If a company tells me they might make £800m and then tells me it will be £750m best case, I consider myself warned!
JD Sports Fashion (LON:JD.)
If a company tells me they might make £800m and then tells me it will be £750m best case, I consider myself warned!
Yes but the company also warned you previously they might make £700 million profit and it looks like they might be on track to make £725 million - its you thats chosen to take a positive spjn here by ignoring the low end of the range - their job is done they have stayed in range. and as things stand midpoint is £25 mil above where they said we may be at year end previously.
Its obvious that a net tweak down in range isnt good news thats a fact i think we can all agree on and move on with less pedantry hoepfully!
JD Sports Fashion (LON:JD.)
looks like a profit warning to me, with profit guidance narrowed to the bottom half (£700-750m) of the previous guidance range (£700-800m)...
sorry for being pendantic here but they are still in their original range - thats the reason why using ranges exists and why they are by far the best and most transparent way of telling us what to expect. results are very much on track for what was promised previously BY THEM as they are still in range - you can call ita profit warning if you want to - but they are still within previous range of guidance given ? - deffo yep. is that reallya profit warning - answers on a posctcard (Graham will call it as a profit warning i am sure so you wont be alone in taking that viewpoint)
As a holder you should very much have been expecting the possibility profits might be £700 mill when the range is £7-8 hunderd mill. thats the purpose of a range to hopefully give everyone crystal clear guidance where we are likely to end up. the larger the range - well the further away from midpoint we may end up - its on your head only if you chose to believe they would earn £750 mill before and now believe its £725 - company are plainly telling you it could be £700
So whilst on the balance of probabilities the midpoint has moved and its likely analysists wil have guided the one published point of data down from £750 to £725 (or more) - they most certainly are still exactly on track now as they have previously guided - its you that has chosen to pick an expectation in range higher than then lowpoint of their promised range,
If you go withn then lowpoint of the range from the getgo - well thats kinds not a bad thing to do.
Note you can kinda geta feel for whether a business and economy is in a sweet spot or not - so if the high street is struggling - Nike are struggling to sell trainers - and projections have been on downward trend for a while. Well i would think the £700 mill is perhaps the most likely result if there is zero pickupn in fortunes - the extra profits kinda needed some bounce have you seen a bounce in fortunes? - management need to be semi hopeful about the future (to keep their jobs !! - no plan and all that) and thats one huge issues with one fixed point - but if its trending flat to down - well to hit top end or even midpoint i think it needed some upturn - if you aint seen the opturn that says its not here.