Kainos: H1 revenue up 37% but shares sink on guidance for slower H2

Analyst’s view:
I'm not surprised to see the Kainos share price ease back today, given in-line guidance for a slower H2 and the reduction in gross margin. However, the group's quality metrics remain excellent and current forecasts already imply c.25% EPS growth this year. I'm happy to maintain our broadly-positive view based on these half-year results.
Down 12% to 1,079p (£1.31bn) - Interim Results
In The Week Ahead I suggested that shares in Kainos might be up with events unless the company included another earnings upgrade with today's results.
The initial market reaction to today's in-line guidance suggests others share my view - this IT service provider's share price is down by 12% this morning.
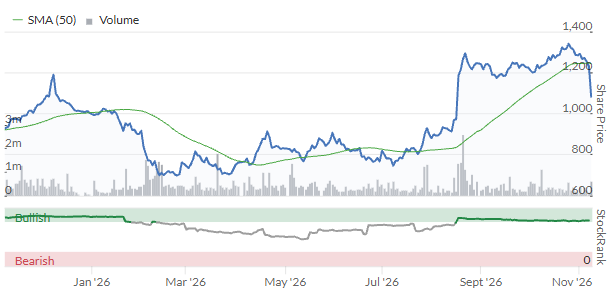
Despite this negative reaction, these look like a good set of results to me, with double-digit growth for both profits and the group's order backlog.
Interim results: key points
August's trading update included upgraded guidance for the current financial year, which ends on 31 March 2027. Today's half-year results expand on August's guidance and confirm strong growth in the group's core Digital Services business.
Revenue up 37% to £268.8m
Adjusted pre-tax profit up 30% to £41.7m
Operating margin: 13.0% (H1 26: 13.0%)
Adj EPS up 45% to 27.4p
Interim dividend up 6% to 10.4p
Net cash (excluding leases) down 18% to £86.5m
Forward-looking measures highlight strong growth compared to H1 last year:
Product annual recurring revenue (the company's own Workday Products): up 24% to £96.0m
New bookings up 27% to £402.3m
Contracted backlog up 26% to £853.0m
Turning to the divisional results, growth was biased towards the Digital Services business (IT services for public sector and large corporates). Growth was a little more modest in the group's two Workday (NSQ:WDAY)-related businesses:
Digital Services (revenue +57% to £162.5m)
Healthcare revenue (UK NHS) rose by 85% to £54.7m with broader public sector revenue +55% to £76.0m. Bookings rose by 44% to £296.5m while the contracted backlog was almost £600m at the end of the period.
North America (+50% to £11.7m) and the Defence sector (+44% to £15.3m) both continue to make an increased contribution.
Rapid growth triggers margin pressures: one negative highlighted by the company is a decline in Digital Services gross margin (-3.9% to 31.9%) due to the increased use of contractors and supply partners to support rapid growth.
This is described as "a short-term staffing decision" today, but it was also flagged up in last year's results. At that time, the company said they expected this to unwind over the course of the current year as temporary staff were replaced with permanent employees. That doesn't seem to have happened in H1. Today we get a slightly different, more nuanced explanation of the reasons for this decline in margins.
Management says that revenue delivered by partners and contractors rose from £15.1m in H1 26 to £49.2m in H1 27. Within this, management sees an approximate 60/40 split between timing effects and structural changes:
Timing effects (c.60%): temporary use of capacity partners and contractors to scale up new projects
Structural changes (c.40%): increasing strategic use of partners to deliver large projects, where Kainos acts as prime contractor.
The company points out that while this approach leads to lower gross margins, it also allows Kainos to take on much higher value contracts. As a result, overall Digital Services gross profit still rose by 40% to £37.1m in H1.
In addition, while contractors and partners have higher upfront costs (including in cost of sales), they have lower employment-related overheads such as training and holiday pay. As a reflection of this, Digital Services' direct expenses only rose by 23% in H1, despite revenue rising by 57%.
I think this trend is worth monitoring, not least because there is perhaps more risk of project delivery problems when a larger number of external contractors are involved. However, I don't think the fall in gross margin is a major cause for concern just yet.
Workday Products (revenue +22% to £48.0m, ARR +24% to £96.0m)
Kainos is one of Workday's leaving approved partners globally. The products business represents a logical extension to this: the company builds and sells its own extensions to Workday's HR platform, such as Pay Transparency Adviser and Employee Document Management. Selling these provides both upsell opportunities and recurring revenue.
This is an increasingly important part of the business for Kainos and the company is actively investing to drive growth. R&D spending (fully expensed) rose by 33% to £11.4m during the period, while Sales & Marketing spend was 11% higher, at £11.1m. Several senior hires were made to lead growth.
Workday Services (revenue +9% to £58.3m)
Performance here was flatter than in the remainder of the group.
North America revenue rose by 10%, while EMEA (including Australia) was 8% higher. New bookings were largely unchanged at £54.3m, but the contracted backlog fell slightly to £73.4m during the period (FY26: £74.9m).
Outlook
My guess is that this is one of the reasons for today's share price slump:
Following the strong performance in FY26 and H1 27, we expect further growth in revenue and adjusted profit before tax in the second half of FY27, in line with current market expectations.
This unchanged guidance implies that revenue growth will slow in H2 - consensus is for a full-year figure of £532m, which implies H2 revenue of c.£263m, slightly below the H1 figure of £269m.
A similar balance acquires to earnings: H1 adj EPS of 27.4p is 54% of the StockReport consensus estimate of 51.2p.
Roland's view
I'm not surprised to see the share price ease back today given the in-line guidance for a slightly weaker H2.
The decline in Digital Services gross margin is also a potential risk, in my view. As Kainos takes on more, larger contracts as prime contractor, I'd argue that the risk of project-specific problems may rise.
However, these risks probably need to be kept in context. Kainos has a good track record in this sector and also benefits from management ownership: long-time CEO Brendan Mooney has a 9%+ shareholding. That should act as a check on reckless expansion and help to ensure financial discipline and operational execution remain priorities.
Another tailwind is that UK government IT spend is almost certain to remain in structural growth, rising well ahead of inflation. Kainos appears to be well positioned to gain in this environment and says it has been one of the top-performing suppliers to the UK government since April, by value of contracts won.
The group is also investing in AI capabilities. Kainos has launched an AI deployment business and is now certified in the Claude Partner Network. It's also supporting the Cosine initiative to develop a "UK sovereign AI model for organisations needing frontier capabilities in a secure environment".
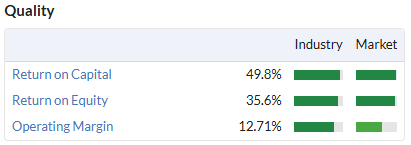
Kainos's quality metrics were excellent ahead of today's results and I don't expect these ratios to change too much when the H1 numbers are included:
This morning's share price drop leaves Kainos trading on a FY27E P/E of 21x, with a c.3% dividend yield.
While this isn't cheap, I don't think it's too unreasonable for a business of this quality that's generating double-digit EPS growth. I'm going to leave our AMBER/GREEN view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Workday (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?