Mainfreight - is it a Buffett worthy stock?

Stockopedia contributor Roland Head, recently wrote an article titled “Screening for Warren Buffett stocks: the ultimate strategy?”, Roland created a screen that he believes would closely mimic the approach Warren Buffett uses to choose stocks that are likely to be great compounders. When that screen is applied to the Australian and New Zealand market today, only 10 stocks make the grade. Universal Store Holdings (ASX:UNI) is one of them and I wrote about them two weeks ago. Another is NZE listed Mainfreight (NZE:MFT) which is the subject of today’s article.
Mainfreight is a global logistics provider with its main office in Auckland, NZ. They have been the definition of a great compounder. The shares have produced a CAGR of over 20% per annum for more than 20 years. Over the past five years, book value has increased at 17%p.a. and EPS at 28%. ROE has averaged 19% and the Greenblatt Return on Capital has averaged 22%. The Greenblatt ROC measure excludes intangible assets, something that Buffett is known to prefer.
Clearly Mainfreight has an enviable track record, but what about the future. Predicting the future is hard (massive understatement). But one thing we can do is try and assess a company’s sustainable growth. To do this we focus on retained earnings and a company’s ability to fund long-term growth from retained earnings. Such a business is more likely to have a competitive advantage.
Stockopedia has an Expected Return metric in the Screener tool which is calculated by looking at the company's 10 year average ROE and its typical dividend payout ratio. It is then possible to calculate an expected sustainable growth rate, based on retained earnings. Roland Head set a minimum threshold of 6% for this metric in his screen. Mainfreight’s expected return is 16.9%.
Companies that are able to fund their growth from retained earnings do not need to raise equity capital thereby diluting existing shareholders. Mainfreight have scarcely issued any new shares over the past 10 years, and none whatsoever in the last five.
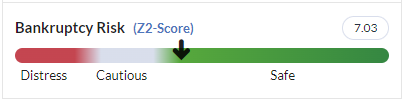
The next question is whether they have used debt to fund their expansion. Using debt can boost the return on equity provided those returns exceed the cost of debt, but it introduces a higher element of risk as the debt will need to be serviced, in the good times and the bad. Mainfreight does make use of debt but it is conservatively managed. The Bankruptcy Risk is low as shown by the Altman Z-score. Gearing levels are moderate with Net Gearing of 45% and Interest coverage is very solid at 28.
Whilst Mainfreight originated in New Zealand and is still based there, it is a truly global business. As shown in the table below, revenue is generated around the world, with the Americas being the largest region followed by Australia and then New Zealand and Europe. The business in Asia is relatively small, but they already have operations in 10 countries with Indonesia being the latest addition and are planning to open a branch in India this year.
They are by no means a small company, with revenue approaching NZ$ 6 billion and a market capitalisation of about NZ$7 billion.
Despite their size they are continuing to grow at a rapid clip, and they are doing so organically. The table below includes a column with recent growth rates, which was 17% across the group. This measured the revenue growth from the beginning of April 2022 to the end of January 2023 compared with the same period in the prior year. Outside the Americas and Asia, growth was very strong. In part, this was influenced by the normalisation of trade as the impacts of COVID started to dissipate.
Revenue by Region
| Region | Breakdown | Recent growth rates |
|---|---|---|
New Zealand | 21% | 19% |
Australia | 26% | 25% |
Americas | 30% | 1% |
Europe | 18% | 17% |
Asia | 5% | -32% |
Group Total | 100% | 17% |
Their revenue is split across three product groups as shown below, all of which have been growing strongly.
Revenue by Product
| Product | Breakdown | Recent growth rates |
|---|---|---|
Transport | 38% | 21% |
Warehousing | 13% | 32% |
Air & Ocean | 49% | 10% |
Group Total | 100% | 17% |
Mainfreight intends to continue to invest in expanding their network and intensification. They planned to invest NZ$360 million in capital expenditure in the year ending 31 March 2023 and are planning on a further NZ$347 million in 2024. A major portion of this is for land and buildings across New Zealand, Australia, the Americas and Europe.
With a Quality score of 97 Mainfreight ranks right near the top of Australasian companies.
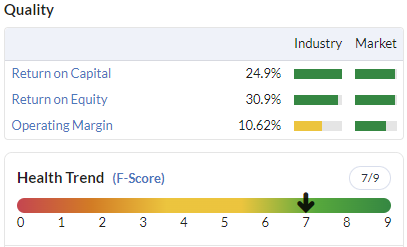
Return on capital and equity are very high and margins are strong. A Piotroski F-score of 7 is also very good. Cash flow is also strong with profits resulting in actual cash generation. This means that the Earnings Manipulation Risk (M-score) is low.
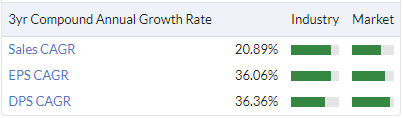
The growth in the share price has corresponded with long term growth in revenue and profits. Revenue growth CAGR has averaged 17.5% over the last five years and EPS has grown at 28%. Over the last three years the performance has been even more impressive as shown in the table below. Revenue is more than double where it was five years ago and profits have quadrupled. And all without raising equity capital.
The value metrics are average, reflecting the fact that Mainfreight is more of a growth play than a value play. However the value metrics are not excessive with a forecast PE of 19, EV to EBITDA of 9 and a dividend yield of 2.4%.
Lastly, momentum has started to bounce back, having increased by 6 to 77 in the last 30 days. The share price has been very strong over the last 5 years but peaked in December 2021 and has been trending down since. This correction reflects a perception that the COVID boost is over and that growth may be harder to come by moving forward. Analysts are actually predicting a decline in revenue in 2024. Despite Mainfreight not being directly impacted, the sector is also still coming to terms with the liquidation of Scott's Refrigerated Logistics and what that will mean for Australian and New Zealand logistic services.
But Mainfreight is known as a company that focuses on the long-term. They look to grow organically and they promote staff from within. Each branch is its own profit centre and accountable for its results. Every staff member is entitled to a slice of the profit bonus pool. Taking the long term perspective, it is just possible that the short term price correction represents a long term investment opportunity.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?