Market Musings 110726: finding favour in Financials

Market Musings 110726: finding favour in Financials
Podcast: Defence back on the radar
In this podcast, Edmund Shing, Global Chief Investment Officer, argues the case for investing in the defence sector.
Consider Banks and insurance for value
While the dominant stock market theme remains Artificial Intelligence, there are pockets of value that are performing very well at present. One such segment of the stock market is Financials, notably Banks and Insurance.
US banks have only relatively recently passed their prior all-time high set back before the Global Financial Crisis (GFC) in 2007, 19 years ago.
US Banks have only this year finally set a new all-time high
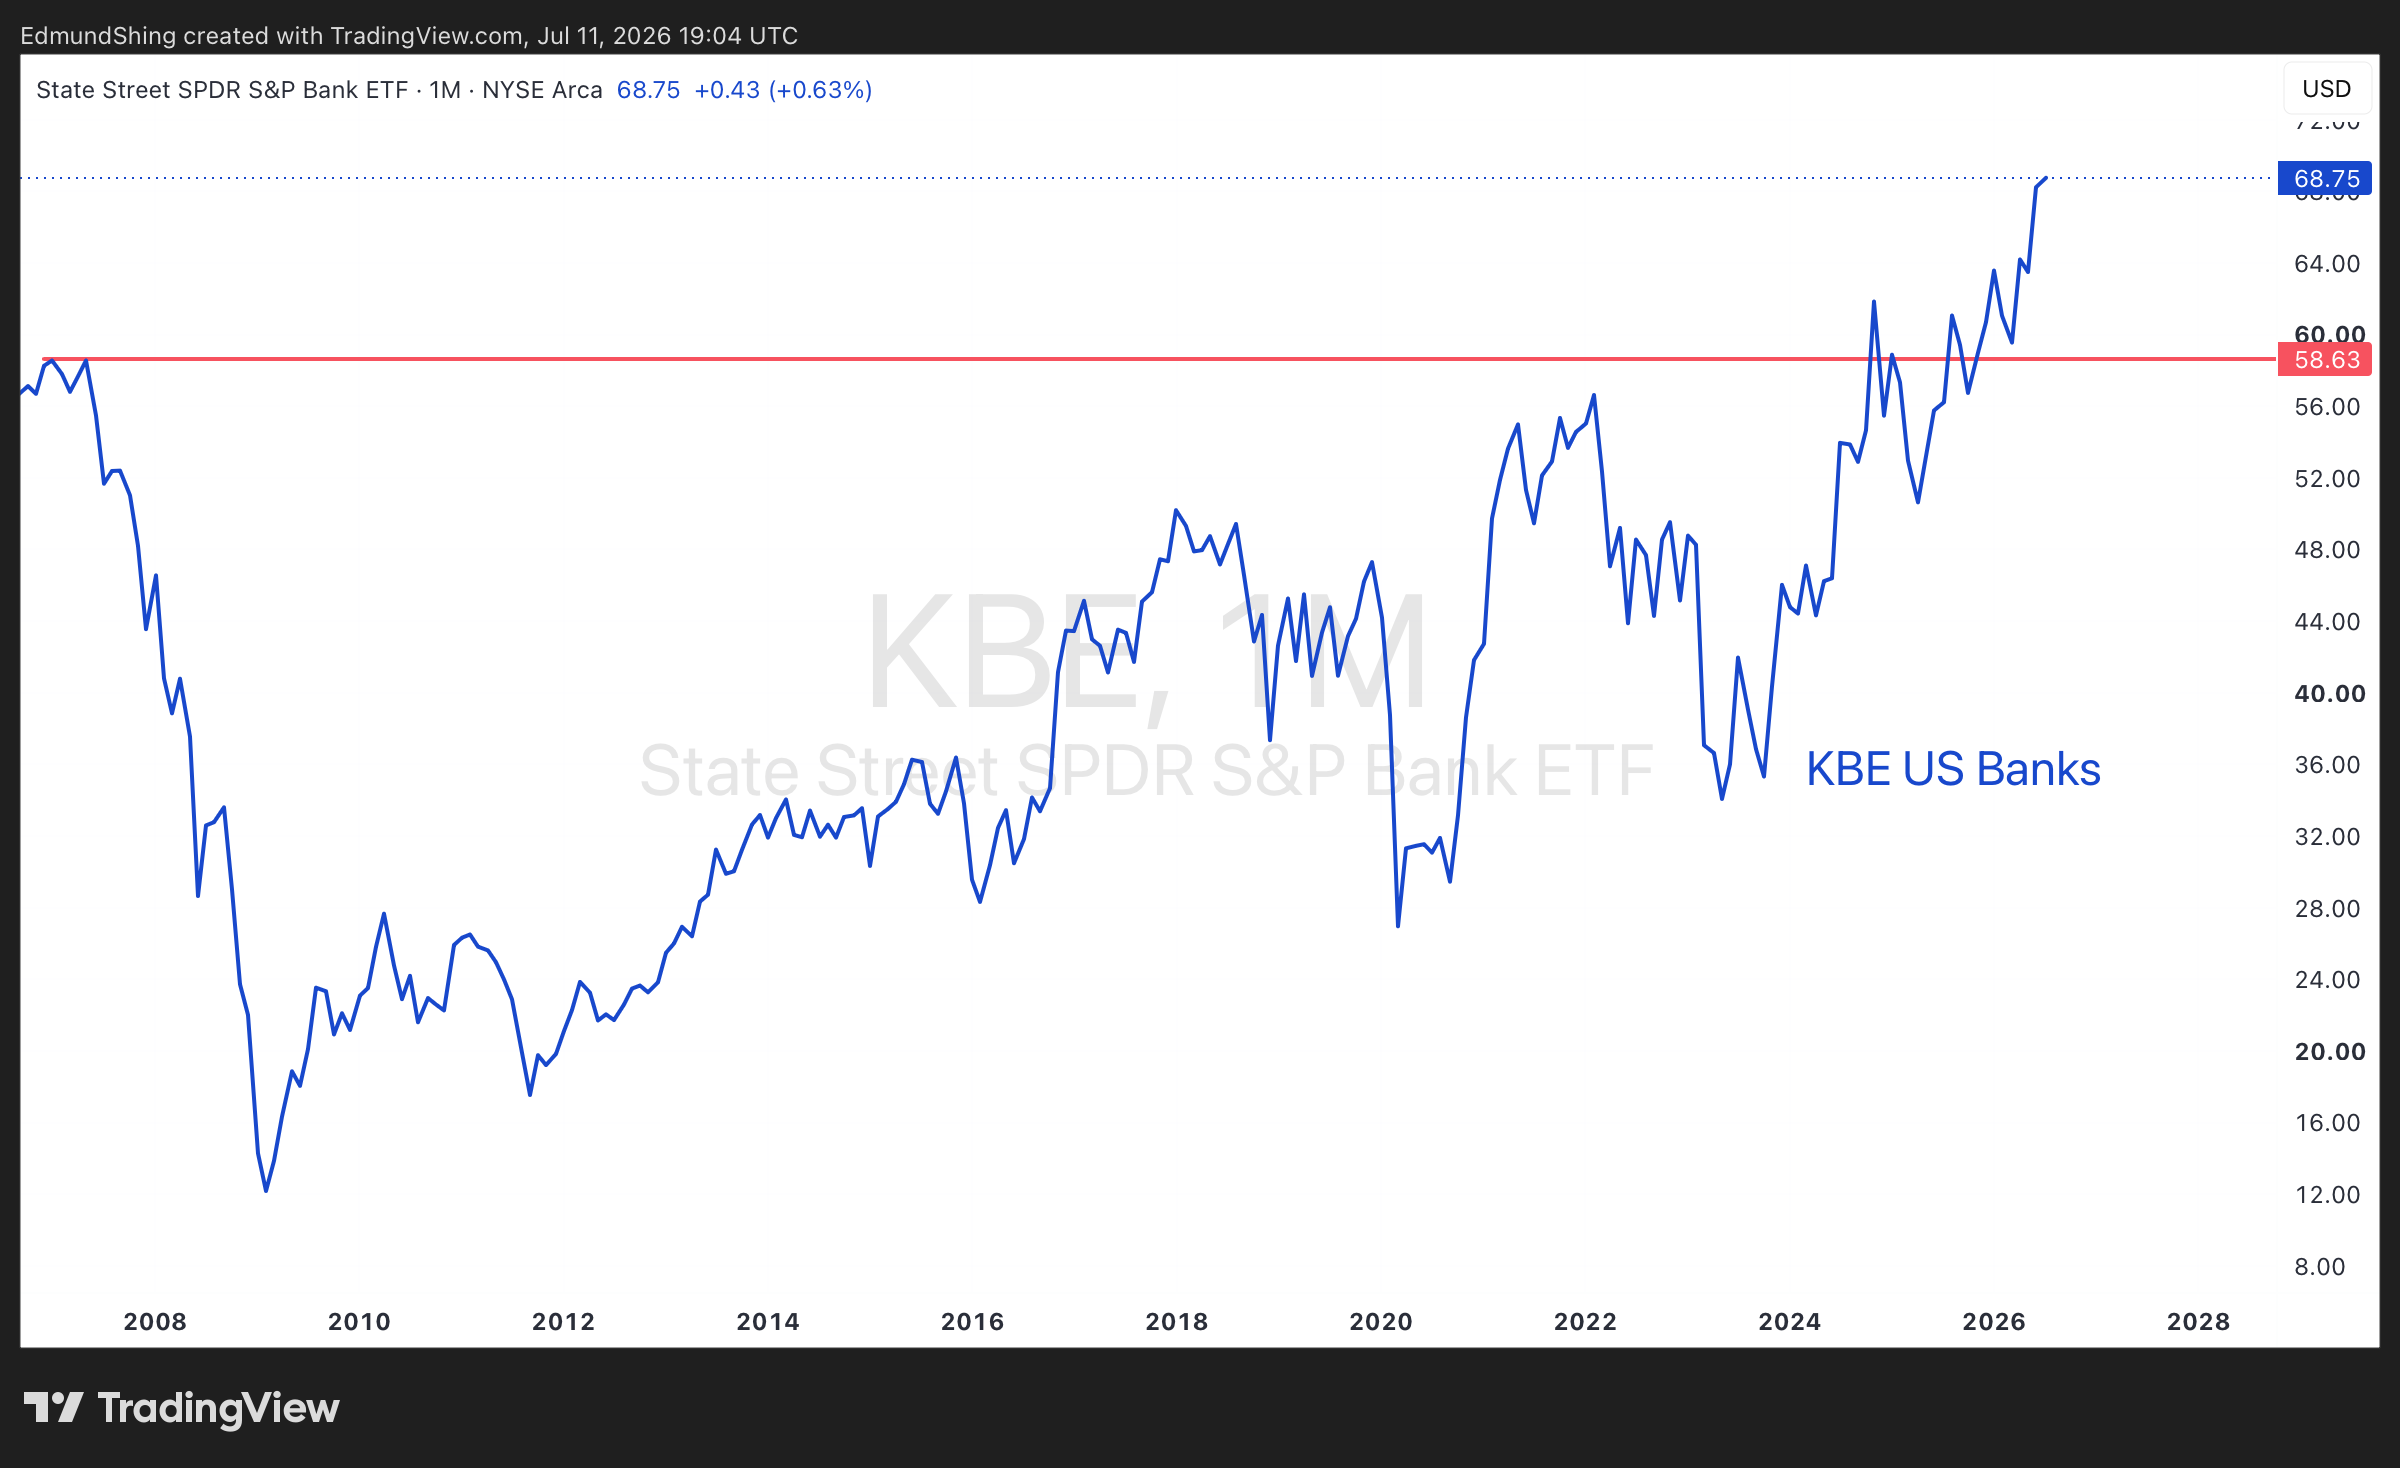
In the case of European Banks, they have still not yet revisited their 2007 pre-crisis highs… Certain banks have just managed to recapture their former all-time highs, including BNP Paribas in France, for instance.
European Banks: Still not back at the 2007 highs
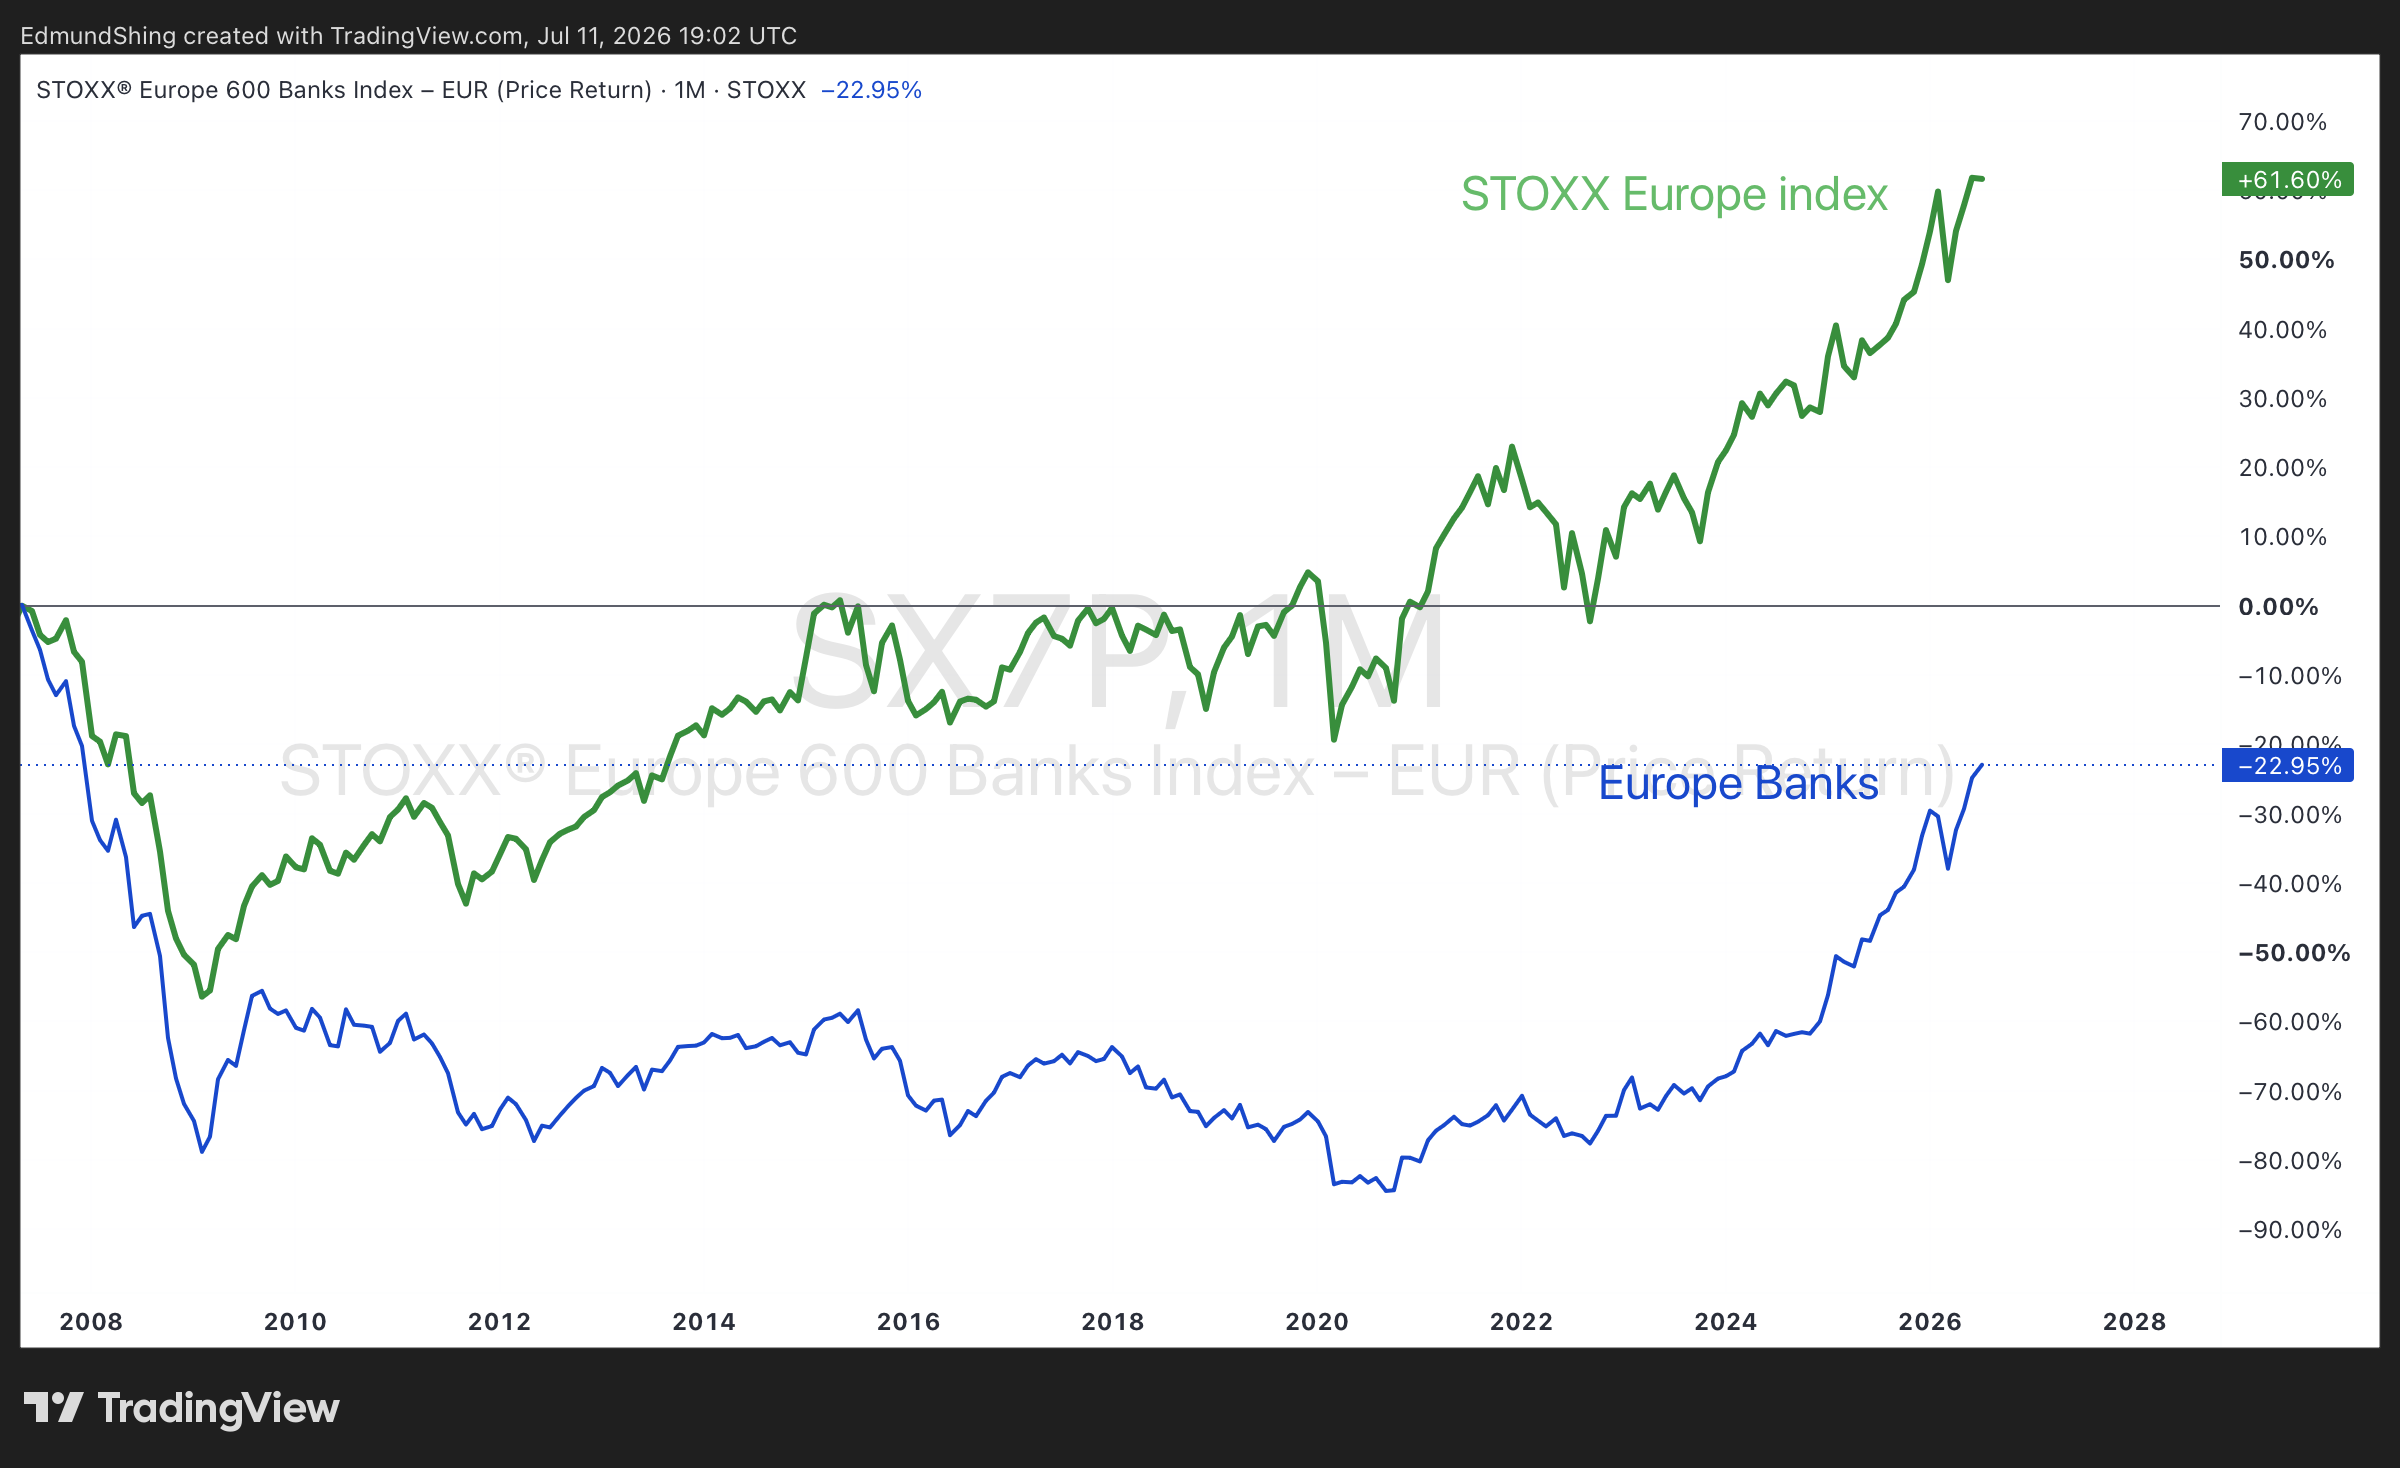
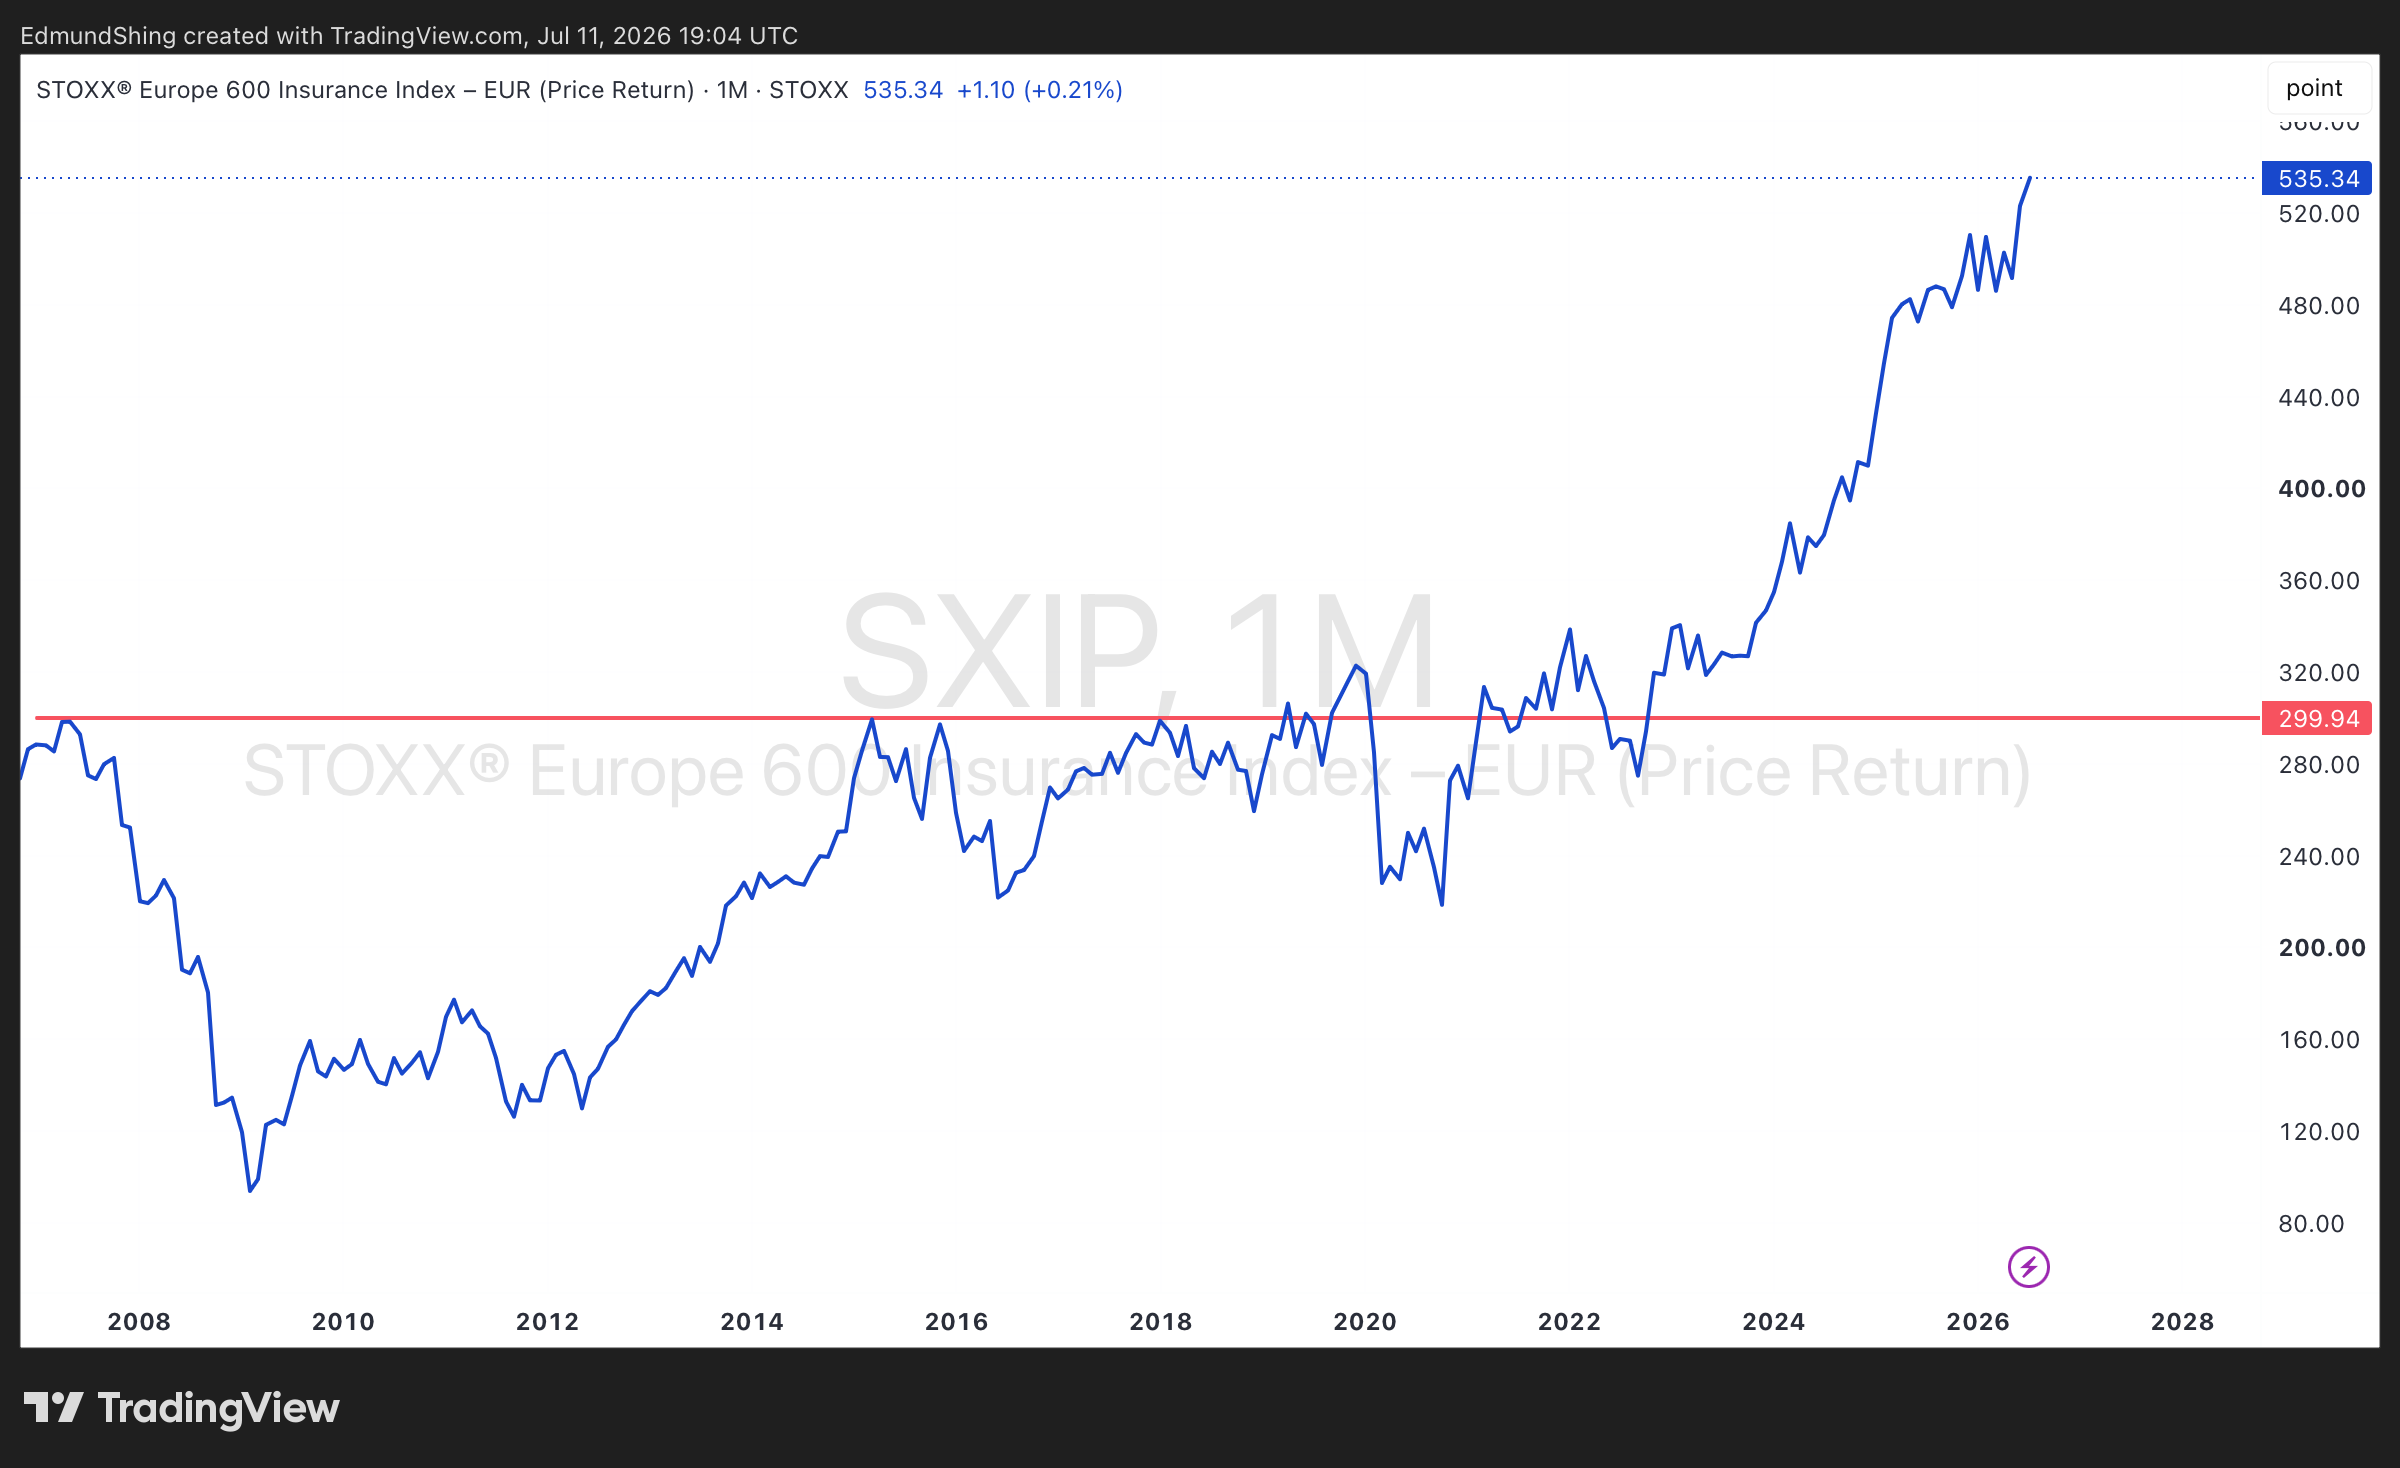
Interestingly, the European Insurance sector has in fact done rather better than Banks over the last 19 years, recovering faster from the GFC.
European Insurance has been stronger since 2007
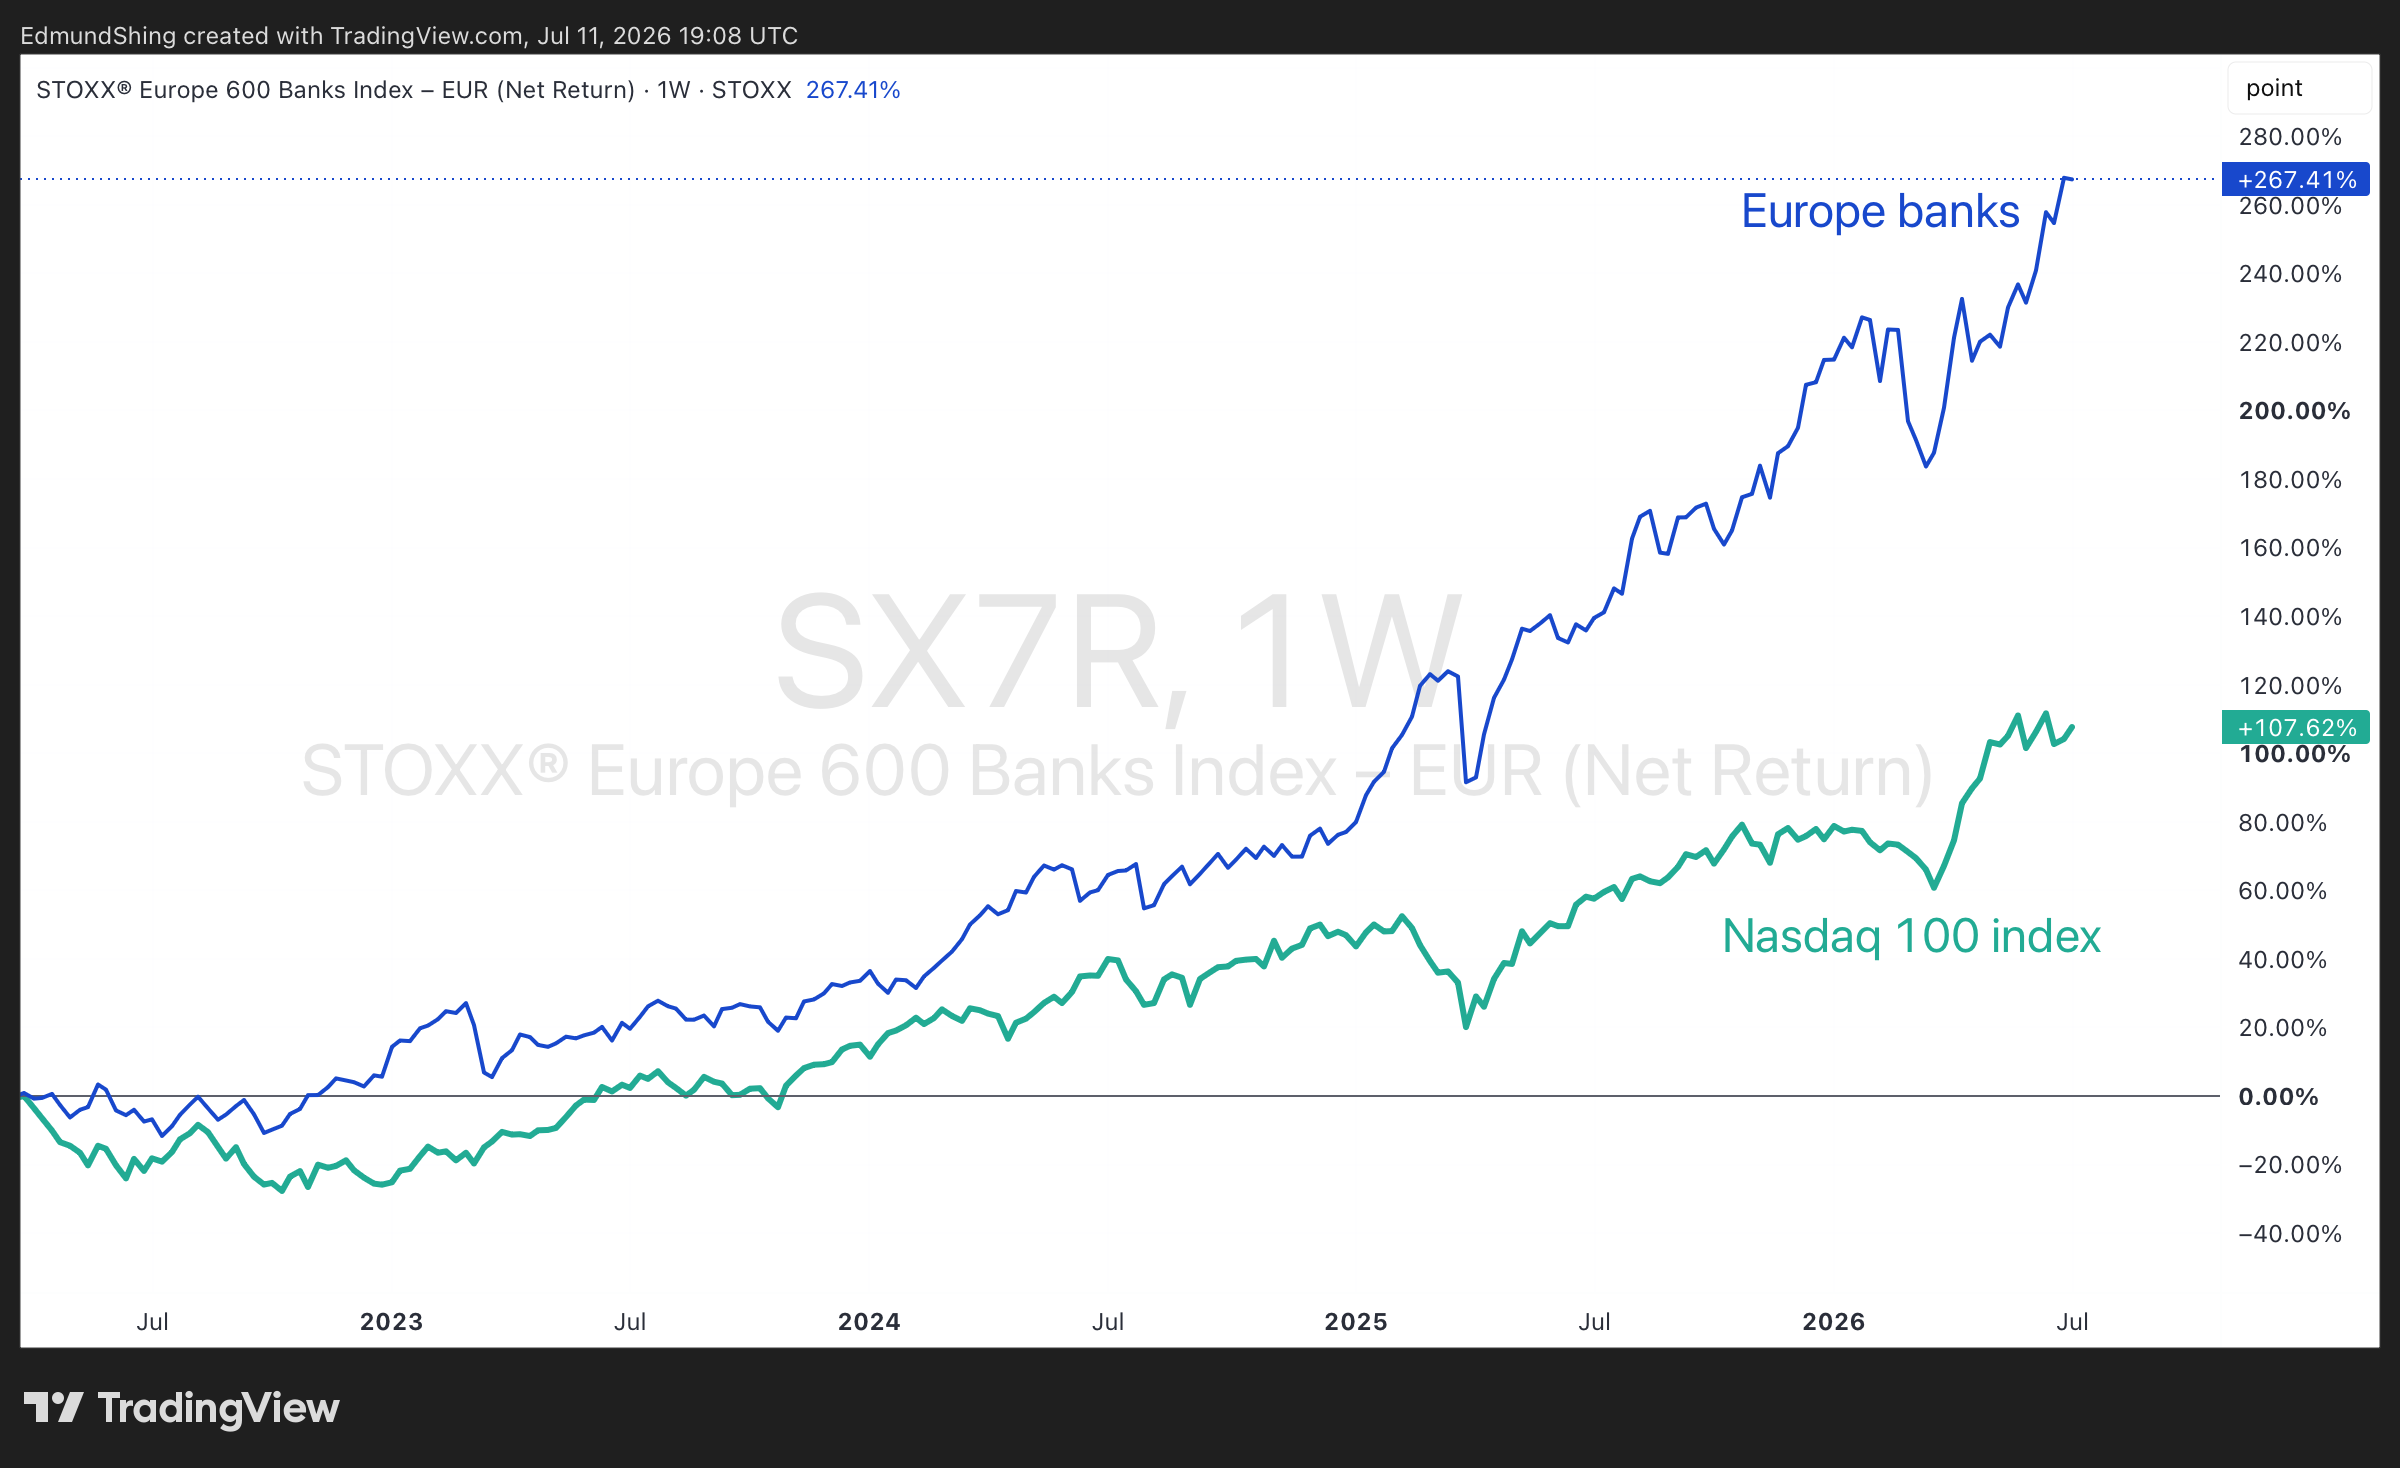
Over te last 4 years however, European Banks have been stellar performers, even outperforming US Tech stocks as strong earnings growth and record-high profitability (ROE) has driven a rerating,. Share buybacks and high and growing dividend payments have also boosted shareholder returns.
European Banks have beaten the Nasdaq 100 since 2022
Today, European Financials offer a dividend yield around 5% together with record-high ROE profitability and double-digit earnings growth. This rosy sector outlook is backed by positive macro trends in the form of higher interest rates and accelerating loan demand from both households and companies.
The current trend of sector consolidation both within-country (e.g. in Italy and Spain) and also cross-border (Unicredit in Italy taking effective control of Commerzbank in Germany) is a further positive, as it could lead to greater integration and thus cost savings, in time boosting earnings growth)..
II would expect a modest further rerating of the European Banks sector in the months ahead from its current 10x forward PE, as it offers today a higher Return on Equity than the US banks sector, but still trades at a big PE discount to their American counterparts.
Given earnings growth of 10%+ and a dividend yield of 5%+, European Banks and Insurance companies could in theory generate a total return to shareholders (price gain plus dividends paid) of 15% over the next 12 months, less impressive perhaps than in 2025 but healthy nonetheless.
ETFs to consider include:
- ESIF iShares MSCI Europe Financials UCITS ETF (Banks + Insurance sectors)
- CB5 Amundi STOXX Europe Banks UCITS ETF
All the best for next week,
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
Edmund great analysis. esp when trying to diversify from AI trade and avoid rollercoster of other thematic ETFs. I have invested in BNKE is it the same composition as CB5? `if i were to invest in one ETF should i stick to bank or better returns with bank + insurance? Thanks
Banks started outperforming in 2022 from a very low valuation basis, 50% of book in some cases.
Insurance started outperforming in 2024, agian low valuations, low p/e's, and in the UK, yields up at 9% (Chesnara, Phoenix and Legals)
Next has got to be the property sector hasn't it? Some big discounts to NAV, low p/e's and high yields. The NAVs are predicated on higher cap rates than historically and they have stopped falling, many are starting to go up. With rents also starting to rise, you should have a good couple of tailwinds.
Derwent London (LON:DLN) Great Portland Estates (LON:GPE) Londonmetric Property (LON:LMP) and Schroder Real Estate Investment Trust (LON:SREI) are a few suggestions, even Land Securities (LON:LAND) if the others are too racy for you.!
Or if you fancy a bit of spice, Regional REIT (LON:RGL)
Hi Chris
I share your view on some of these. I think London Metric needs to have some time to absorb all of its acquisitions and whilst I am a holder, not sure there is so much value outside the yield here. I am more bullish on quality London Offices and hold GPE. I also know the new CEO of Derwent although the estate is a little from his more comfort zone, Stocko like Derwent more than GPE as it stands