Marks and Spencer: Solid H1 results with food sales up 13.9%
Analyst’s view:
A solid set of H1 results from Marks and Spencer today. There are some issues in Fashion, Home & Beauty but the Food division is performing well.
Up 3% at 427p (£8.6bn) - Half-year Financial Report - Ed S - AMBER =
Marks and Spencer Group has today published its interim results for the 26 weeks ended 26 September 2026. Let’s unpack them.
Highlights:
Sales of £9,255.0m, up 16.2%
Operating profit before adjusting items of £486.5m versus £251.4m in H1 FY2026
M&S Group adjusted PBT of £403.2m versus £184.1m in H1 FY2026
Adjusted basic EPS of 14.8p versus 6.6p in H1 FY2026
H1 dividend of 1.4p versus 1.2p for H1 FY2026 (+16.7%)
Net debt of £2,466.7m versus £2,528.3m
Net funds ex. lease liabilities of £374.7m versus £176.1m
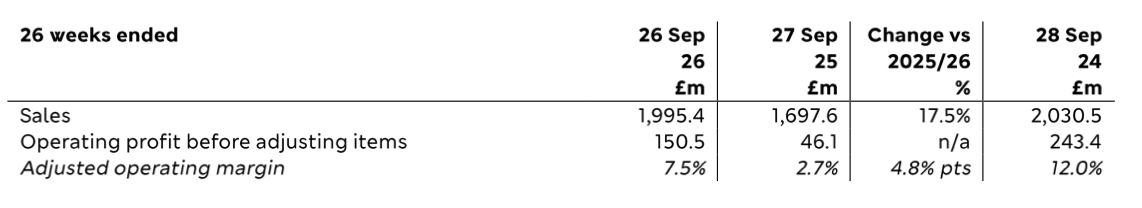
Food sales up 13.9%, margin of 5.6%
Fashion, Home & Beauty sales up 17.5%, margin of 7.5%
International sales up 22.1%, margin of 4.9%
Ocado Retail sales up 20.6%, margin of 1.4%
Outlook:
Expects group adjusted PBT for the full year to be in line with current market expectations.
In Fashion, Home & Beauty, market conditions remain challenging. However, performance is expected to improve in the second half compared with the first as availability has recovered.
Continues to build its structural cost reduction programme across technology, logistics, and stores. Cost growth including marketing was weighted towards the first half while structural cost savings are planned to build through the second half.
For the full year, food margins are expected to be ahead of 2024/2025.
In Fashion, Home & Beauty, the actions underway are expected to support a progressive improvement in profitability.
Over the medium term, its ambition is to generate mid-to-high single-digit revenue growth and higher growth in profit and EPS.
Ed S’s view:
These results are tricky to analyse as last year’s results were obviously impacted significantly by the major cyber attack the company experienced in April 2025. But I think M&S is heading in the right direction.
The Food division is a highlight. Here, the company saw double-digit volume growth in a flat market with market share gains since 2024/2025 and margin expansion (margins here were 5.6% versus 5.1% two years ago).
“Our food business is ahead, delivering double-digit volume growth in a flat market and we have momentum as the UK’s fastest growing grocer. One and a half million more customers are shopping with us and our continued focus on quality, innovation, and value is appealing to more families.”
The company notes here that given its low overall market share in food, there remains significant opportunity to increase customer numbers and basket size. Looking ahead, it is planning to double the size of its food business.
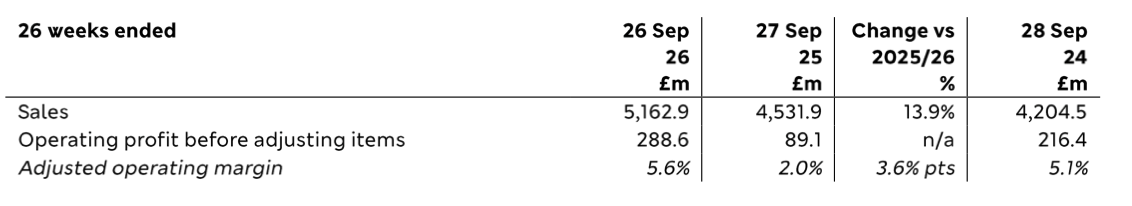
In Fashion, Home & Beauty, the company is struggling a little, with sales and margins remaining below 2024/2025 levels (margins of 7.5% versus 12.0% two years earlier) due to availability issues and the prolonged summer heat. However, it notes that performance is expected to improve in the second half compared with the first as availability has recovered.
I’ll point out here that I often buy basics (e.g. polo shirts) online at M&S and I have been frustrated with a lack of availability in certain sizes over the last 18 months or so. I would have spent more money with them if certain sizes had been in stock so if they can fix the availability issues there’s an easy win for them.
In terms of costs – an ongoing risk – the company says that it has absorbed significant external cost headwinds versus two years ago including approx. £35m of packaging taxes arising from the Extended Producer Responsibility (EPR) scheme, increased pay and National Insurance costs, and costs related to the disruption in the Middle East, partially offset by its ability to mitigate costs. It adds that structural cost savings are planned to build through the second half, however, I still see costs as a risk given the energy backdrop.
As for the outlook, the company says that it enters H2 in a strong position, which is encouraging. Even more encouraging is the 16.7% increase in the H1 dividend – that suggests to me that management is genuinely confident that the business is heading in the right direction.
It seems the market is happy with today’s results. As I write, the share price is up about 3%.
At current levels, the stock is trading on a forward-looking P/E ratio of about 13. To me, that valuation is about right – I don’t see a lot of scope for multiple expansion.
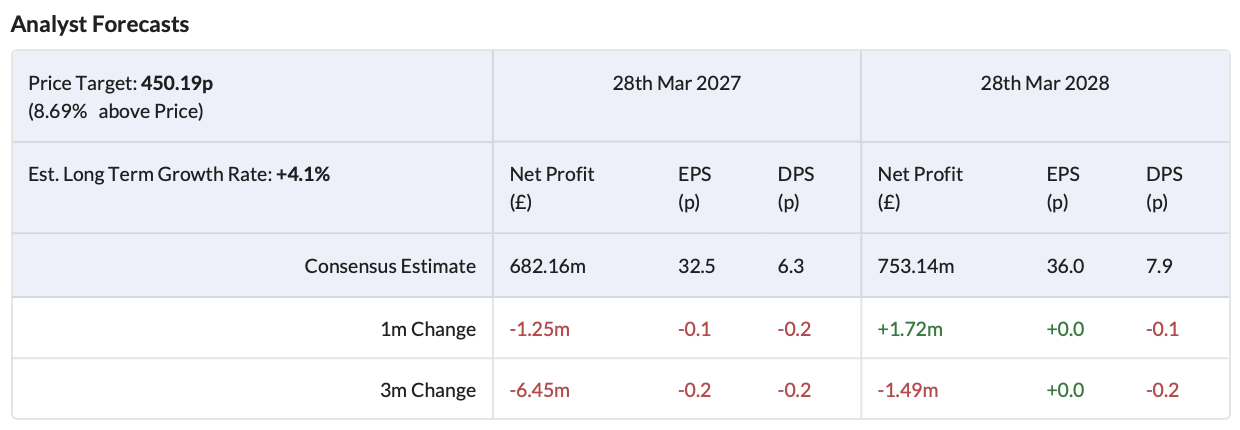
That said, analysts expect a decent rise in earnings next financial year. So, the share price could continue to trend up.
It’s worth noting here that the share price appears to be breaking out above a key resistance level of around 410p (its sixth attempt at this level). So, that’s something to watch.
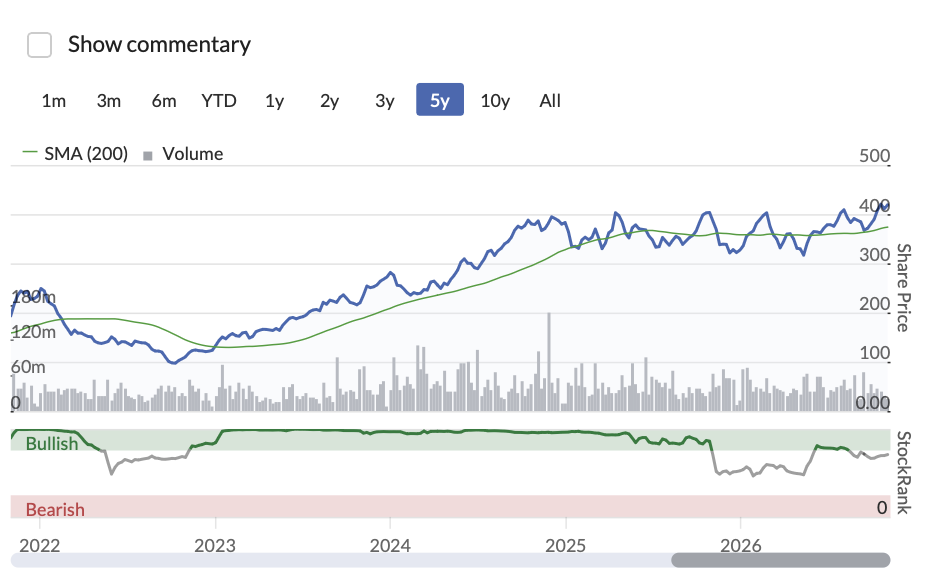
Weighing everything up, I’m going to leave the stock on an AMBER rating for now. I’m tempted to go to AMBER/GREEN but the struggles in Fashion, Home & Beauty and the valuation lead me to think that an AMBER rating is more appropriate for now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Marks and Spencer (5)
Comments here are also visible in the Daily Stock Market Report
I have only skimmed thru the Marks and Spencer (LON:MKS) interims but as the food part of the business has been so strong this is probably a good read across for strength in Greencore (LON:GNC) who derive around 15% of their business from Marks and Spencer.
Marks and Spencer (LON:MKS) looks fully valued now. I’ve held for 4 years and the time to buy was ahead of the share more than quadrupling from when the share price fell to under £1. The market ignored the upside potential for their clear and well explained proposals/ four year plan for radically improving their prospects. Perhaps a drop to amber rating is a bit harsh, but it’s certain that the big share price gains have been had.
Hi Ken, yes I agree re the MKS valuation.
Quite a helpful table from 'selfside' on X re Marks and Spencer (LON:MKS) results - I hope they don't mind me replicating here. Food is doing tremendously well - more work to do on fashion, home and beauty following last year's cyber disruption.
A jump in m&s stock rank to come quality and value ranks to be upgraded should jump sr tp above 90?