Daily Stock Market Report (Wed 4th Nov 2026) - MKS, SNWS, MTEC, MTRO, WEIR

Good morning. US voters have delivered their verdict on President Trump’s policies, handing full control of Congress to the Democrats. High fuel prices and the war in Iran have played against the Republicans in recent months.
The impact on markets is yet to be seen. One potential concern is that Democrats will take a tougher stance on tech regulation and the build-out of AI data centres.
Another possibility is that geopolitics – and fuel prices – will have more of an immediate impact than the change in Congress. In an interview with the FT yesterday (£), the President said discussions with Iran remained ongoing and that he had no immediate plans to restart attacks on Iran.
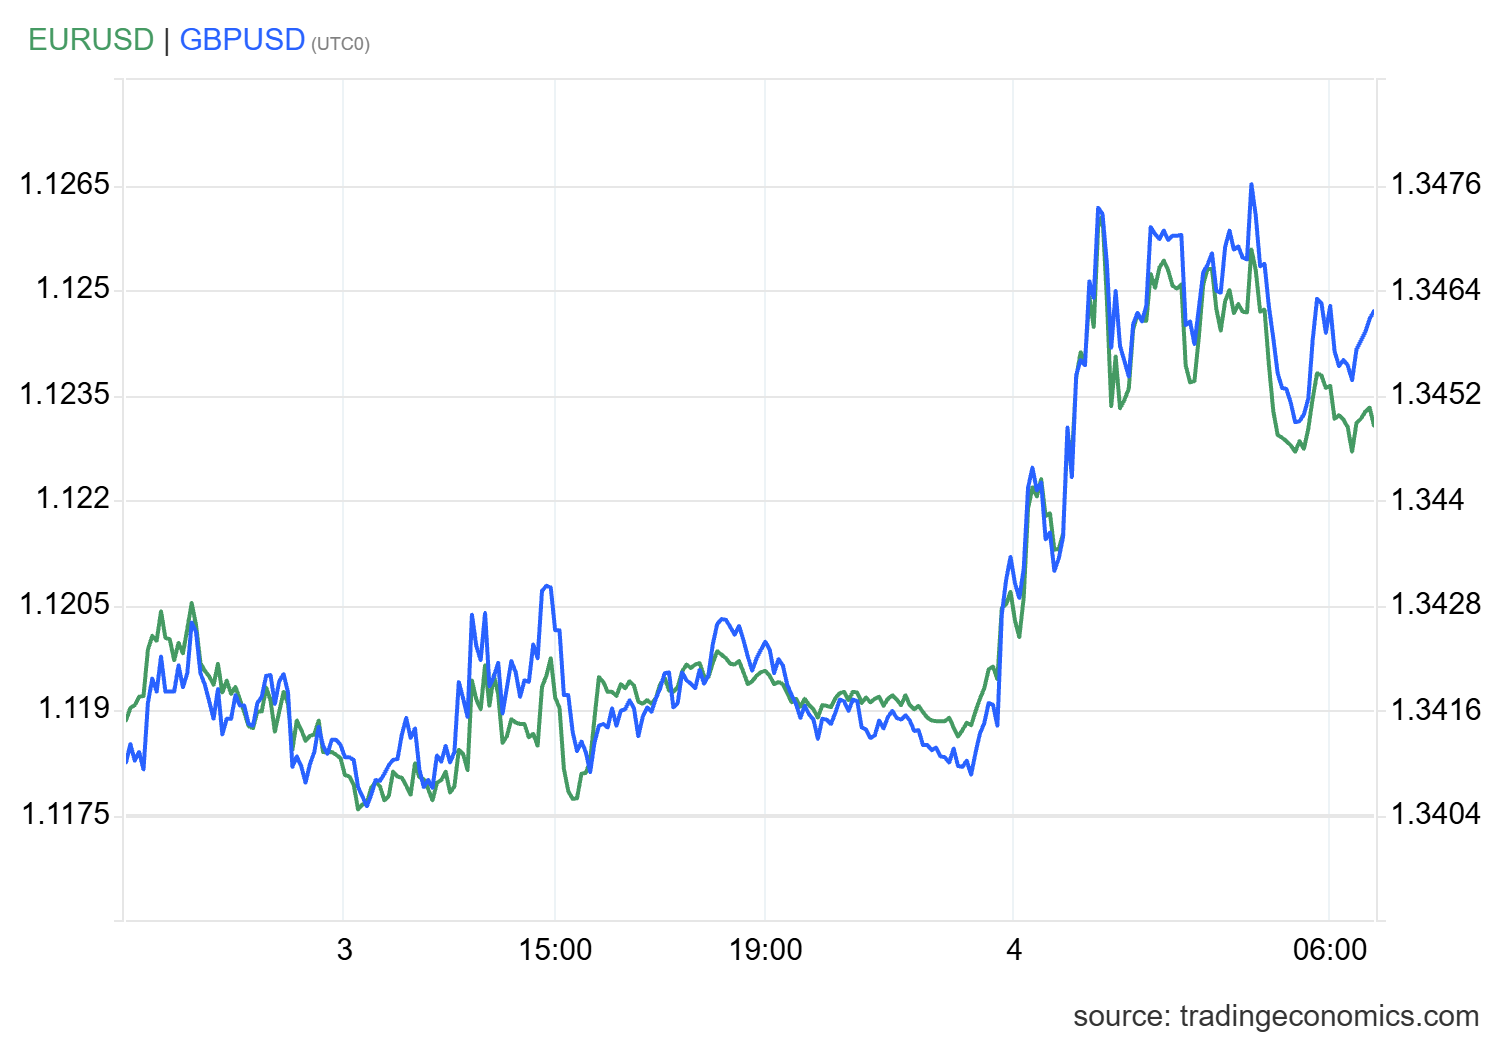
The dollar fell against the pound and the euro as news emerged of the win:
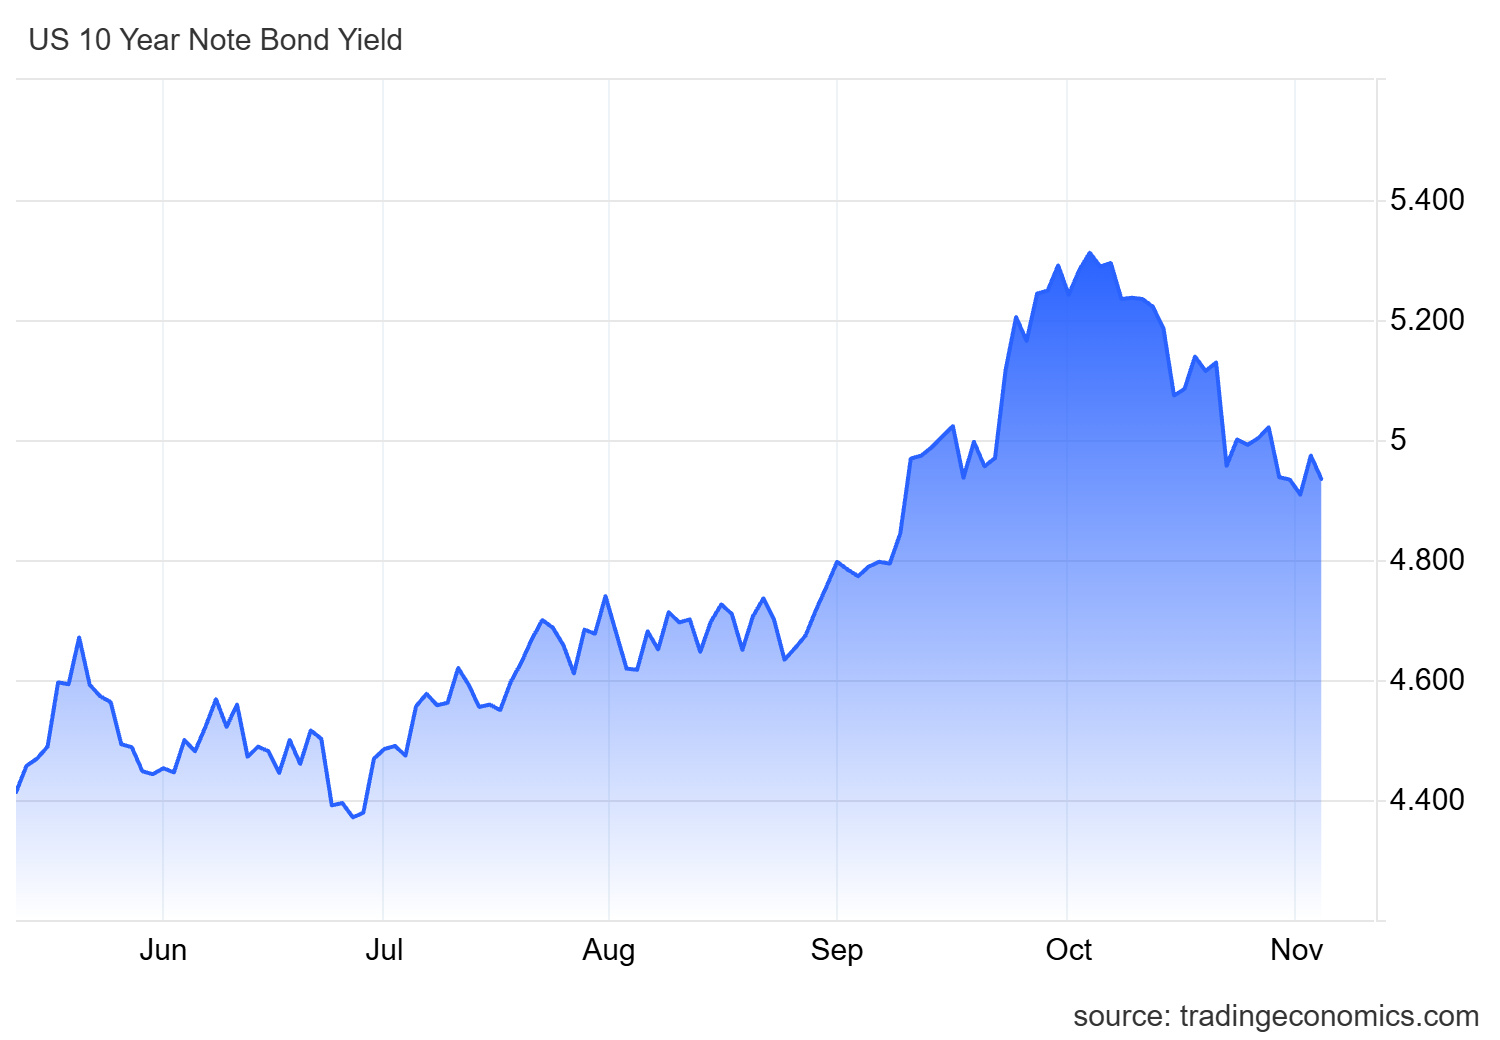
US Treasury yields have also eased over the last month, perhaps in the hope that government spending will be restrained:
Early indications suggest markets will open slightly lower this morning, but without any drastic ructions. It may be interesting to see how the big tech stocks trade later when US markets open.
Overnight market movements:
The FTSE is down 0.4% at 10,605
S&P 500 is down 0.3% at 7,549
Brent crude (January) is up 0.4% at $104.00/bbl
Gold is flat at $4,019/oz
Bitcoin is up 0.6% at $77,826
Spreadsheet accompanying this report: link.
Ed Sheldon joins me (Roland) today.
Today's report is now complete.
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Coca-Cola HBC AG (LON:CCH) (£17.4bn | SR79) | Q3 net sales revenue +9.6%, with volume +5.4% and price per case +4%. Upgraded FY26 guidance: now expects revenue growth “slightly above our 6% to 7% range” (previously “around the top end”). Guidance for organic EBIT growth of 8% to 10% is unchanged. | ||
Smith & Nephew (LON:SN.). (£9.4bn | SR48) | Q3 revenue +3.4% to $1,551m with strong Sports Medicine and ENT performance. Conditions mixed elsewhere. Outlook: guidance updated to reflect outlook for US Hips and Knees. Now expects full-year revenue growth of c.3% (previously 4%) and trading profit of “around $1.25bn” (previously “around $1.3bn”). | PROFIT WARNING | |
Marks and Spencer (LON:MKS) (£8.6bn | SR70) | H1 sales +16.2% to £9,255m with adj pre-tax profit of £403m and adj EPS of 14.8p. Food sales +13.9% with Fashion, Home & Beauty +17.5%, reflecting the recovery from last year’s cyber attack. FY27 Outlook: adj pre-tax profit is expected to be in line with market expectations. | AMBER = (Ed S) | |
Weir (LON:WEIR) (£6.8bn | SR42) | Q3 group orders +8%, with aftermarket +10% and OE +3%. Outlook: strong orderbook, expect to deliver FY26 in line with expectations. | AMBER (Roland) | |
Lion Finance (LON:BGEO) (£5.2bn | SR58) | 3rd Quarter Results & GEL 62.0 million share buyback programme extension | Q3 profit +21% to GEL 661.9m with return on average equity of 27.2%. Announcing Q3 dividend up 22.6% to GEL 3.25 per share, with a further GEL 62m share buyback. | |
Barratt Redrow (LON:BTRW) (£4.38bn | SR69) | Completions during the first 17 weeks of FY27 fell by 12% to 3,223. The underlying private sale reservations fell to 0.53 (FY26: 0.57), but there was an increase in bulk sales to the rental sector. The forward order book rose by 1% to £3,315m, compared to the same period last year. FY27 guidance remains unchanged. | ||
Glanbia (LON:GLB) (£3.93bn | SR66) | YTD revenue +9.9% on a like-for-like basis, with volume growth across all three segments. FY26 outlook upgraded: now expects adj EPS growth of 22% to 24% at constant currency (previously 17% to 20%). | ||
Lancashire Holdings (LON:LRE) (£1.69bn | SR75) | Gross premiums written -1.1% to $1,806m with insurance revenue +0.7% to $1,409.7m. Will pay a special dividend of 75 cents per share ($182m). Outlook: remains on track to deliver high-teens RoE in 2026. | ||
J D Wetherspoon (LON:JDW) (£1.08bn | SR57) | Total sales +9.1% for the year to date, with like-for-like sales +8.2%. Net debt was £736m at the end of the first quarter. FY26 Outlook: “profit forecasts are very dependent on sales growth”, but “we are comfortable with current market expectations, once adjusted for the 53-week period”. | ||
Metro Bank Holdings (LON:MTRO) (£1.03bn | SR68) | Total lending +5% £9,425m, with lending in target segments +37% and run-off lending -32%. Net interest margin +0.42% to 3.45% with “strong credit quality maintained”. Outlook: reaffirming all guidance. Expect RoTE greater than 15% in 2027. | AMBER/GREEN = (Roland) | |
Trainline (LON:TRN) (£733m | SR77) | H1 revenue -1% to £233m with operating profit -5% to £64m. Adj EPS -10% to 13.8p. FY27 outlook: guidance unchanged, with underlying revenue of £440m to £455m and adj EBITDA at c.2.9% of ticket sales. | ||
Funding Circle Holdings (LON:FCH) (£592m | SR63) | Has appointed Rob Straathof as CEO, subject to regulatory approval. Rob previously spent a decade as CEO of Liberis, leading its growth from a UK small business lender with a single partner, into a global embedded finance platform offering multiple products and providing over $4bn of funding to more than 100,000 small businesses. He is currently CEO of Grover, a leading European technology subscription platform based in Germany. | ||
Foresight Solar Fund (LON:FSFL) (£366m | SR79) | Unaudited net asset value was £511.1m at 30 September 2026 (30 June 2026: £517.9m). This results in a NAV per ordinary share of 93.8p (30 June 2026: 94.9p). Global portfolio generation for the third quarter was 9.8% above budget, supported by solar resource 10.7% ahead of expectations. | ||
Zotefoams (LON:ZTF) (£237m | SR78) | Total Q3 group revenue of £41.8m (Q3 2025: £38.2m), up 9%, including a £6.2m contribution from OKC. Organic revenue was £35.6m, down 7%, reflecting lower footwear revenue of £9.3m (Q3 2025: £17.6m). Based on trading to date and the current order book, and subject to there being no material disruption to the group’s key markets, the Board expects full-year adjusted profit before tax for the year ending 31 December 2026 to be in line with market expectations. | ||
Smiths News (LON:SNWS) (£201m | SR98) | Revenue down 2.6% to £1,036.2m. Adjusted profit after tax up 1.5% to £27.4m. Adjusted EPS up 1.8% to 11.3p. Full-year dividend of 5.65p, up 0.1p. Net cash of £3.9m. FY2027 trading has started positively. Short-term profitability impact expected in FY2027 as the business absorbs expansion and transition costs. | PROFIT WARNING (AMBER/GREEN ↓) (Roland) | |
Strategic Minerals (LON:SML) (£140m | SR38) | The Australian Foreign Investment Review Board approval has been received and the sale of Leigh Creek Copper Mine Pty Ltd to South Pacific Minerals Investments Pty Ltd, trading as Cuprum Metals, has now completed. | ||
FDM (Holdings) (LON:FDM) (£111m | SR71) | Momentum in customer engagement has continued since the company’s half-year results. The Board anticipates that the group's financial performance for the full year to 31 December 2026 will be in line with its expectations. The group has maintained its robust balance sheet, with £31.9m of cash at 31 October 2026. | ||
Made Tech (LON:MTEC) (£83m | SR81) | Acquisition of the entire issued share capital of Glasgow-based housing technology provider Target Applications Limited, which trades as CX Feedback. Initial cash consideration of £3.0m, subject to adjustments, with up to £3.0m of additional performance-based consideration. The acquisition will be fully funded from existing cash reserves. Target Applications had annual recurring revenue of £1.05m as of 27 October 2026, and the deal is expected to be earnings-enhancing on an adjusted earnings basis in the financial year ending 31 May 2027. | GREEN = (Ed S) | |
Braemar (LON:BMS) (£79m | SR82) | Revenue up 16% to £74.3m. PBT up 34% to £5.1m. EPS up 28% to 11.89p. Interim dividend raised 10% to 2.75p. Full year trading expected to be in line with market expectations. FY30 targets unchanged. | ||
Chapel Down (LON:CDGP) (£73m | SR28) | Placing to raise approx. £5.5m (approx. £5.1m net) by way of an accelerated bookbuild. A separate retail offer to raise up to approx. £0.5m, giving total gross proceeds of up to approx. £6.0m. Net proceeds to fund a £4.5m investment in a new soft pressing facility at the company's Tenterden winery, together with the additional working capital required to support the increased level of Traditional Method Sparkling production resulting from the Soft Pressing Project. | ||
Orosur Mining (LON:OMI) (£53m | SR9) | Latest drill results from APTA: MAP109 - 15.35m @ 0.97g/t Au, MAP110 - 43.55m @ 1.53g/t Au, including 14.2m @ 3.1g/t Au. | ||
Medpal AI (LON:MPAL) (£49m | SR14) | New Health revenue of £3.63m in October, up 33% on September revenue. New Health repeat order revenue more than doubled in October to £1.34m, representing 37% of New Health revenue. Group revenue of approximately £4.1m in October, up from approximately £3.2m in September. Group annualised revenue run rate of £49m. | ||
Gem Diamonds (LON:GEMD) (£20m | SR87) | Carats recovered during the Period were 19,299 (Q3 2025: 22,268). Following strong operational performance and cost containment the group is positively revising its FY2026 guidance. |
Analyst notes
- Smiths News (LON:SNWS)
Smiths News: FY27 broker forecasts cut ~25% on expansion costs — but does opportunity remain?
Smiths' FY26 results look good to me and are in line with September's revised forecasts. I'm also encouraged by this year's contract wins and the opportunity for the company to gain market share in its core business. Realising these benefits will carry some execution risk and temporarily depress earnings, however. While I'm confident value remains, I've moved our view down by one notch today.
A solid set of H1 results from Marks and Spencer today. There are some issues in Fashion, Home & Beauty but the Food division is performing well.
- Metro Bank Holdings (LON:MTRO)
Metro Bank: target lending up 37%, on track to deliver improved profitability
Metro Bank's shift to a specialist lending model appears to be progressing well and is on track to deliver the expected improvements in profitability. My valuation sums suggest that the shares could still offer some value, even after recent gains. I'm comfortable maintaining our AMBER/GREEN view ahead of this year's results.
While the market is spooked by the news of the Target Applications acquisition, there appears to be strategic rationale for the deal. Not only will it broaden Made Tech's existing housing solutions and increase its recurring revenue but it is expected to be earnings-enhancing this financial year.
- Weir (LON:WEIR)
Weir Group: Q3 orders up 8%, but project delays and market headwinds point to downside risks
Although Weir is very well respected, it's also exposed to the same cyclical and geopolitical pressures as its mining and oil customers. As things stand, I think the valuation is up with events and carries some downside risk if recent trends don't improve. I'm going to open our coverage by taking a neutral view today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
38 comments
Smiths News (LON:SNWS) is in the current NAPs portfolio. Difficult to know if this would be kept given the profit warning. It does have a quality rank of 75 though. One of those that could go either way.
Yesterday shawr asked/reminded folk to name the stocks they were discussing. As several still haven't today I thought I would reiterate the plea today. It isn't too hard, see helpful tip above, and saves those of us who prefer unthreaded comments much time searching for the original comments. Thankyou
I agree, it's a real pain trying to work out which stock is being talked about.
I have only skimmed thru the Marks and Spencer (LON:MKS) interims but as the food part of the business has been so strong this is probably a good read across for strength in Greencore (LON:GNC) who derive around 15% of their business from Marks and Spencer.
Marks and Spencer (LON:MKS) looks fully valued now. I’ve held for 4 years and the time to buy was ahead of the share more than quadrupling from when the share price fell to under £1. The market ignored the upside potential for their clear and well explained proposals/ four year plan for radically improving their prospects. Perhaps a drop to amber rating is a bit harsh, but it’s certain that the big share price gains have been had.
Hi Ken, yes I agree re the MKS valuation.
I suppose the valuation opportunity could be via upside potential in repairing food, beauty and home category. When I get more time I might try and look at what brokers are estimating for that side of the business to see if the upside is already in forecasts or if there's an opportunity to beat them.
Zotefoams (LON:ZTF)
Not sure what the market was expecting? A trading ahead statement? The company had already said it was trading in line when it announced the acquisition of Verttec on 13 October.
The management team are doing what they said and shaping a more balanced business that is not overly dependent on Nike and high spec running shoes. It takes time and the shares remain cheap, cheaper this morning and too cheap in my view. Admittedly the fall of in revenue in athletics footwear has been more than anticipated but the company states that it is trading in line and provides consensus of £26.3m for adjusted profit before tax bang in line with current forecasts.
I hold
Thoughts from Roland or Ed would be welcomed.
Very interested to hear what you have to say on the Made Tech (LON:MTEC) acquisition.
Made Tech (LON:MTEC) Small but decent looking acquisition, of course the share price drops!
You nudged Braemar up to Amber 29/9/26 Roland, I'd be interested in your opinion on today's HY results if you have time. We're long term holders and as you pointed out then, the shares have been a disappointing investment to put it kindly! As you've shown the main points in today's Agenda I won't repeat them. The shares have so far dropped 1p since the September TU as of 8.35am.
If you could cover Smiths News (LON:SNWS) and Made Tech (LON:MTEC) that would be great.
On the US midterms, possibly with a majority win it's better then deadlocks. Ai is still critical (race against China). Capex commitment might weaken. As markets tends to be up 12 months after a midterm this will just be a buy the dip.
Just a line in the sand re bonds - market seems "unmoved" excuse the pun.... MOVE is 99 - not really high or low but off recent lows and VIX just north of 20 reflecting the AI pull back. Broadly speaking the market behaving and yields have pulled back already.... which tweaks current sensitivity more to weakening economy than inflation fear. If anything I think the blue wave supports that but it depends what knee jerk policies we see.... as things stand today the bond market is calm... and moving in the right direction...ie Up and yields down...
Smiths News (LON:SNWS)
This is new holding for me as I only bought in at the beginning of the month. I think the attractions here are obvious high stock tabk and reasonably lowly rating and generous divi.
Today’s update seems broadly fine the key here that gave me confidence to buy in is their new contracts that seem to provide great base for them to continue to tick over for the next 5 years - there should be opportunities along the way to pimp out the fact they have vehicles out their delivering stuff daily. - lots of scope to tie in here and their to get stuff regularly to fixed locations on behalf of others.
Share has tendered upwards nicely over the last 30 days - rather annoyingly looks like they downgraded 2027 expectations a tad in stocky for new year like 3 days after my purchase - at sane timing upgrading 2026 - with lowly rating though i will overlook that for now - what is key to know is what 2028 numbers will be - if anyone has any clues I am all ears - to me it’s the one thing with stocky often the next year numbers are “awol” and don’t show up till final year finished numbers are banked and closed off - presuming next year forecasts may be released before ye numbers are banked that’s kinda uber annoying bit having info that may exists ? Not sure what the official position is here ? Not all companies will have next year forecasts yet so perhaps it’s me wishing for data that doesn’t exist.
Hopefully ref new year started there won’t be any further chops - I have hopes they will be upping profits not lowering here next 3 years.
In my view it is an underrated stock , it has clear strategy to realign the business and its distribution network is extensive
I also hold. To me, this is a nice profit warning (if there is such a thing). They surprised the market with their recent wins but have now put some meat on the bone regards the inevitable cost of servicing that new work.
A temporary profit hit to invest in growing revenues and opening up the possibilites you mention seems perfectly reasonable. I'll be interesting in what the Stocko experts say assuming they review this one today.
Smiths News (LON:SNWS)
A temporary profit hit to invest in growing revenues and opening up the possibilites you mention seems perfectly reasonable. I'll be interesting in what the Stocko experts say assuming they review this one today.
cheers Cayman69 - that makes complete sense as explanation and its kinds good reason for them to have the temporary hit if it comes with the payback over the rest of the contract. so happy days unless there are any hidden downgrades today - hopefully they are well placed to beat next time the dial moves rather than downgrade again.
The market initially reacted very positively to these recent contract wins, driving share price to multi-year highs. I did wonder at the time about the huge costs not to mention operational risks of all this expansion - seems the market was somewhat caught out by the actual costs. Quite a hefty 27% downgrade to EPS next year, so after the recent run-up I can't see much attraction in the shares for the time being. Perhaps one to revisit in a year or so as we start to see the upside from these new contracts?
If they hadn't done the recent deals one could assume that revenue would continue to decline at 3% p.a. and cost cutting would have kept eps at 10.1p
They made it clear over the last 6 months that there would be extra costs involved. Both Edison and Cannacord made it quite clear in their notes over the summer.
So the new numbers from Cannacord has t/o falling by -2% to Aug '276, up from -3%.
For Aug 28 t/o, instead of declining 3% again, the new number is up 20%.
For Aug 29, the new forecast t/o is up 2% to £1,263m Without the deals and the costs involved the t/o might have been around £934m.
As mentioned earlier this year, costs have risen. So yes, there is 27% hit to Aug 27 and 7% to Aug 28 eps numbers. But for Aug 29 we may have expected 10.1p again, instead we are looking at on Cannacord's numbers of 12.1p.
So that investment is turning a declining business struggling to maintain eps to one with turnover growth and significant growth in eps.
After today's fall, on Cannacord's Aug 29 numbers, Smiths News (LON:SNWS) is on a p/e of 5.8x and a yield of 8.8%. (Oh, and a fee cash flow yield of over 15%)
Obviously there are execution risks, but the mkt seems o me to be very short term.
Is this an issue in theUK? Punishing investment in long term growth?
P.S. I own a few
What have you been waiting for rmillaree? This is new holding for me as I only bought in at the beginning of the month. I've been holding Smiths News (LON:SNWS) right from 2011, only selling twice in bed and ISA adjustments. Seeing the recent rising share prices means to me a lowering dividend and don't envisage buying any more shares beyond a 70 pence price.
Smiths News (LON:SNWS)
What have you been waiting for rmillaree?
a well run buisness in a declining marketplace doesnt have that much interest to me normally - perhaps i have unfairly tarred it with that brush over the years as they seem to have manged to keep profits up with events over the years - so not sure if core sales have held up long term better than expected or they have manged to fine new avenues to mitigtae decline in newspapers (thats alywas the ricky one if you dont know that replacement profits will turn up if main income source is reducing yoy.
the fact that thney have manged the decline so well and the fact they have these new contracts - that kinda says to me that whatever they are doijg has fully worked so they are a different beast from 10-15 years ago when we knew that newspaper sales would cperhaps drop 50% and they needed a cunning plan - they have kinda delivered the cunning plan. Yes newspaper sales will continue to drop going forward - but i would be semi hopeful volume of drop next 5 years will be nothing like prior 10 years - i think sales for year just done in growth verticals were up 30% plus - so i dont know exactly what splits are between newspapeers and magizines and others but it all looks pretty sweet at present overall
were you aware results were today when you bought? buying immediately before trading updates is best avoided unless you’re a gambler. Exact dates are not always provided although I believe they were in this case.
Smiths News (LON:SNWS)
were you aware results were today when you bought? buying immediately before trading updates is best avoided unless you’re a gambler. Exact dates are not always provided although I believe they were in this case.
agreed - i have checked exactly when i bought and i actually bought on the 29th September ** which was actually on the day of the recent trading update - whilst todays news is clearly "short term pain" - i get it that investment is needed - the price i paid 70p still leaving me in profit if i choose to sell (i dont think i will) but i kinda need to know that the investment is going to up profits from where we were bearing in short term the chunky hit we have that is real.
perhaps they could have been clearer ref downgrades - but i accept the principle you gotta splash the cash to have the infrastructure to pimp out those assets later ref efficiciency gains (not to disimilar to ZIGUP (LON:ZIG) where debt had been rising with investment in van fleet - payback is later on)
here is the comments from Septemeber ref outlook that gave me confidence - with the benefit of hindsight perhaps there is a clue here hiding in plain sight ref startup costs. Shame they werent slightly more transparent from get go in that regard. Albeit someone did have an inlking i think early october.
Moving into FY2027, trading has started positively and the Company has begun its transformational programme to establish a national distribution footprint to service the new contract wins announced in H2 FY2026, ahead of the first go-live in July 2027.
i have copted the following comments from the other place (ad..)- taken from wealth oracle - these numbers if taken at face value kinda make sense. What i cant immediatley get my head around is how the material uplift of £12-£18 million from 2029 onwards is calculated thereafter - is that from low point of compared to year just finished - if its gonna be 12p eps aftre £13 miluplift per ChrisW's comments - well overall thats not much forward progress - albeit pe wil be cheap as chips.. If all then investment takes place this year though i think the market will kinda look more forward than backward once we get closer towards next year.
from the other place
The more consequential development is strategic: management has locked in long-term national publisher contracts worth around £375m of incremental annual revenue, with potential to reach £600m, prompting a step-change expansion to roughly 700 routes and 23 depots under the Go National programme. That transition carries a price — £21–27m of investment plus £7–9m of FY2027 transition costs — and will visibly depress profitability in the coming year, with only a £0–2m uplift modelled for FY2028 before the material £12–18m per annum benefit crystallises from FY2029.
**(trade settled in october annoyingly my broker details settlement date on history screen rather than actual purchase date - so i thought it was last month when it was late sep)
Quite a helpful table from 'selfside' on X re Marks and Spencer (LON:MKS) results - I hope they don't mind me replicating here. Food is doing tremendously well - more work to do on fashion, home and beauty following last year's cyber disruption.
A jump in m&s stock rank to come quality and value ranks to be upgraded should jump sr tp above 90?
A seismic change in the US. Any views on the market winners and losers?
Free trade again?
Could see more negativity towards the AI trade given some Democrats were elected on data centre opposition.
Might renewables get a boost?
Zotefoams (LON:ZTF)
On track (broadly?) trading update here - ignoring Footwear sales everything seems to be 100% firing on all cylinders and they reiterate they on track for their ambitious plan to raise operating profit to 40 million pa by 2029 - we should perhaps pay lip service to stuff like that as we don’t know if they will need to make £50 million acquisition to get their. It’s a completely meaningless number if it’s achieve with material bought in profits. IMHO tho at start of 2027 we will only be 24 months away from starting 2029 and it at least shows they have reasonably clear plans where they want to be - they have shown decent ability up to now to trend profits upwards well medium term.
Plans ref new Vietnam facility seem very pleasingly on budget and on track to deliver the real wonga next year - that’s key great news - execution to plan new factory and expanded new customer and partners won’t ever be be easy so great alto see the rate no slippages - with their partner In the region hopefully demand will be good.
What may dominate the conversation today is the huge drop off ref footwear sales - must admit I wasn’t expecting such a brutal slowdown - not normalisation was very much flagged up and expected here - % drop does seem uber high though - I suspect this drop off will take the headlines today and might spook the market a little in that regard to me it all depends on broker updates ref next year - with new Vietnam facility about to go live (and that will be footwear hub) if they don’t downgrade 2027 expectations today it’s tickety boo. I’m done trsiects the bumper orders they had received from Nike was always gonna be double edged sword in that - as and when they lose that business or it drops off they need to find replacent saies wise where - in that regard their plan seeks to be working to me unless there are behind the scenes updates ref 2027 - we won’t have long to wait to see what the brokers say.
For what its worth im glad im out - the slowdown in footwear is much worse than I expected or feared - and leaves them missing two big data points - they exited their new packaging technology as they could not sell it - and captured the losses in rising profits but footwear has slipped away. In fact footwear is so bad they are talking about XFootwear sales - this company simply isn't as good as I thought or hoped. I can't believe no downgrades today but if not I would move on.... because they are likely coming.
Zotefoams (LON:ZTF)
We will have to await broker updates regarding 2027 to see - it’s never simply been about the footwear though - that was a flashy headline - obviously they have jay jade with Nike tie up but I am personally fairly confident that once Vietnam is up and running you will be proved wrong in you lt assumptions that they can’t overall cut the mustard.
2027 I agree is a tricky year they need to prove you completely wrong in your assumptions - obviously the new Vietnam facility will take time to get upto full capacity - so I don’t blame he anyone for being on now but I have seen nothing in direct comments today that suggest overall they aren’t on track.
The packaging was blue sky fluff really - it made less than didly squat and was rightly sidelined being waste if focus - that sideline has zero relevance to the now and the future - albeit they could perhaps benefit.
Seems crazy to be knocking a company that prior to 2025 made like 10 mill pa - as things stand it’s gonna be 20 mill pa plus profit for 2025 2026 and 2027 - with the extra capacity coming on tap in 2027 - are you of opinion they are gonna struggle to make 20 mill plus with this extra facility right in the centre of key footwear markets - non footwear stuff seems to be taking up the slack? I get doubts about 2027 but their vision seems crystal clear to me.
I also disagree with you RDHowarth. I think the new management team under Ronan Cox have done all the right things so far. Exiting the new packaging technology was pragmatic. The new Vietnamese jv should underpin future growth in footwear, bolt-on acquisitions have been sensible and well priced but, most importantly, the rest of the Group's revenues have been growing very impressively. In the long-term this will be key to cushioning the impact of volatile footwear sales.
If Zotefoams (LON:ZTF) can hit 2029 targets the business looks fundamentally too cheap and as rmillaree says the £20m+ profits now being generated are a good step in that direction.
Happy to disagree - the £4m or so uplift they captured in 2025 from losses in reZorce falling away looks to me like its been given back .. and so they are struggling to hit near term forecast which make longer term 2029 expectations look unrealistic - unless they hit this target through acquisitions which Im less keen on. Like I say - not what I thought it was going to be and feels like a company struggling.
Zotefoams (LON:ZTF)
Very good points by everyone
I don’t hold but I’m watching closely as I think it’s a well run company with potentially a good future
The reason I don’t hold is because the two key executives have never been prepared to risk their own cash in buying shares in the company, which I have always found to be very strange given the potential upside. So until they do I don’t see why I should !
But I think today’s update shows why they have have been so reluctant.
Lancashire Holdings (LON:LRE) maintain their 75c special. That keeps the yield at 16%.
Morning all!
£ getting stronger v $
Gold is flat? Really!? Gold has regained 4000!!