Smiths News: FY27 broker forecasts cut ~25% on expansion costs — but does opportunity remain?

Analyst’s view:
Smiths' FY26 results look good to me and are in line with September's revised forecasts. I'm also encouraged by this year's contract wins and the opportunity for the company to gain market share in its core business. Realising these benefits will carry some execution risk and temporarily depress earnings, however. While I'm confident value remains, I've moved our view down by one notch today.
Down 9.6% to 73p (£187m) - Preliminary Results
Today's results from the UK's largest newspaper wholesaler starts well, with FY26 figures that are in line with consensus forecasts. The sting in the tail is that management expects a hit to profits during the current year as Smiths makes the investment needed to expand its distribution network nationally to service a number of recent contract wins.
I've put this down as a profit warning as there are material cuts to broker earnings forecasts this morning. However, I do think we need to recognise the context here: near-term profits are going to disappoint because the company is investing to support contract wins, not because of any trading shortfall.
We've been positive in the past on Smiths News, most recently in September when the company upgraded its FY26 guidance (y/e 29 Aug 26) to reflect a strong performance from collectables (e.g. FIFA World Cup stickers).
Let's take a look at today's results to see if our positive view can be maintained.
FY26 results summary
Today's headline numbers are as we've come to expect from this business - a small decline in revenue with flattish (adjusted) profits:
Revenue down 2.6% to £1,036.2m
Adjusted operating profit down 1% to £38.7m
Adjusted earnings per share up 1.8% to 11.3p
Dividend up 0.1p to 5.65p per share
Free cash flow: £24m
Net cash: £3.9m (FY25: £3.3m)
If this was the end of the story, then I'd suggest a neutral view was fair here based on the combination of an attractive, sustainable dividend yield but no growth.
However, that isn't the whole story. Smiths News has secured a number of large contracts over the summer. Management says these wins represent c.£375m of additional annual revenue and will support an expanded national distribution network. That opens the door to the potential that this business could return to growth over the next few years, potentially justifying a higher valuation.
The company has helpfully provided a summary of its revised contract situation today, highlighting both additional volume and duration:
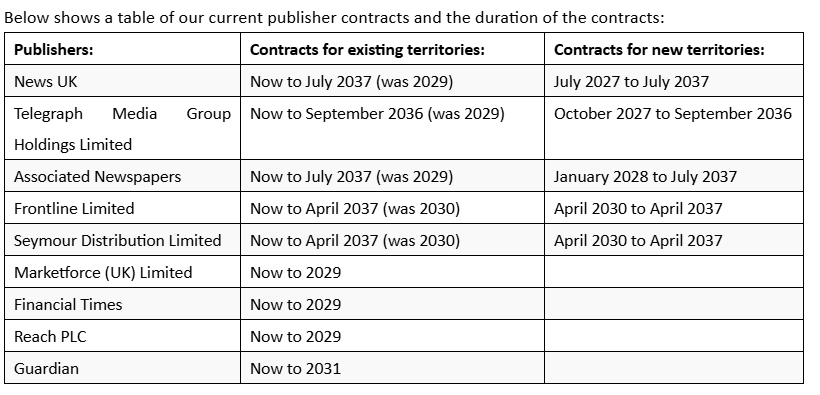
Go National expansion plan: these contract wins will see Smiths News become the UK's largest newspaper and magazine distributor, with a 61% share of these combined markets at the point when contracts commence. Alongside this, the company is pursuing growth opportunities in areas such as cardboard and paper recycling collection (for return loads).
To service this extended workload the company needs to expand its network to offer national coverage. This will involve adding 700 additional routes and 23 new depots; a substantial investment.
As promised, management has provided financial guidance for this expansion with today's results:
Total implementation costs of £21m to £27m
Additional "early life transition costs" of between £7m and £9m in FY27 relating to onboarding new clients.
New contracts are expected to deliver incremental net profit of £0m to £2m in FY28 and between £12m and £18m from FY29.
It's clear that if the new contracts can deliver the hoped-for net profit (i.e. profit after tax) from FY29, then the implementation costs outlined today should provide attractive returns on investment.
A short-term hit to earnings in FY27 could be a reasonable price to pay to achieve this growth potential.
Although there's obviously scope for mishaps and cost overruns when carrying out such a significant expansion, I think it's reassuring that the new work remains within the company's core competency. By adding new routes and depots, Smiths isn't doing anything it hasn't done many times before. That should reduce the likelihood of problems.
The other potential risk is the ongoing decline in print volumes that will continue in the background. The company has won a much larger slice of a shrinking pie. Consolidation is the correct solution to this problem, but the exact pace of future decline is hard to predict.
Updated broker estimates
Consensus forecasts for FY27 fell slightly in September, when the company outlined its plans and upgraded FY26 guidance:
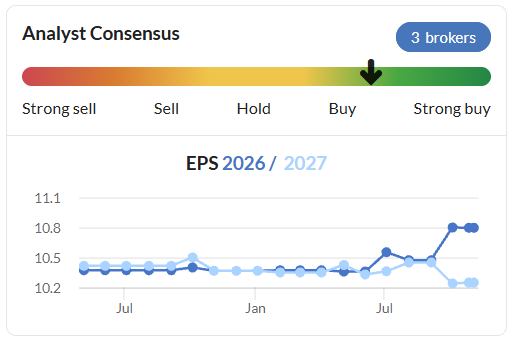
However, today's cut is much more material. Broker Canaccord Genuity has helpfully published an updated note on Research Tree today, including revised EPS estimates:
FY27E adj EPS: 7.3p (-27.7% vs 10.1p previously)
FY28E adj EPS: 9.4p (-6.9% vs 10.1p previously)
FY29E adj EPS: 12.1p (new forecasts)
A 28% cut to FY27E earnings is a big reduction - adjusted EPS has been hovering around 10p for a number of years now.
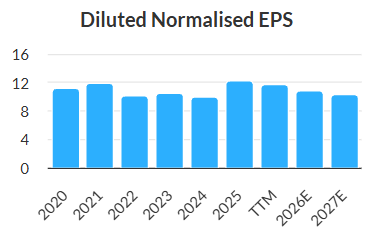
However, the opportunity appears to be significant, so the short-term pain may be worthwhile.
Roland's view
In my view, this year's contract wins and the associated expansion plan have increased both the risk and the opportunity for shareholders.
Arguably, the risk is mitigated by the company's continued focus on its core business and its solid execution in recent years. But I can't ignore the reality that earnings in both FY27 and FY28 are now likely to be lower than previously expected.
Today's downgrade leaves Smiths trading on a FY27E P/E of 10, falling to a P/E of around six in FY29.
The company expects to maintain the current dividend through the next year, providing a potential dividend yield of 7.6% after this morning's drop.
There could be attractive value here, but there's also increased execution risk and potentially a longer timeframe before this value will be realised.
To reflect this situation, I'm moving our view down by one notch to AMBER/GREEN today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Smiths News (10)
Comments here are also visible in the Daily Stock Market Report
If they hadn't done the recent deals one could assume that revenue would continue to decline at 3% p.a. and cost cutting would have kept eps at 10.1p
They made it clear over the last 6 months that there would be extra costs involved. Both Edison and Cannacord made it quite clear in their notes over the summer.
So the new numbers from Cannacord has t/o falling by -2% to Aug '276, up from -3%.
For Aug 28 t/o, instead of declining 3% again, the new number is up 20%.
For Aug 29, the new forecast t/o is up 2% to £1,263m Without the deals and the costs involved the t/o might have been around £934m.
As mentioned earlier this year, costs have risen. So yes, there is 27% hit to Aug 27 and 7% to Aug 28 eps numbers. But for Aug 29 we may have expected 10.1p again, instead we are looking at on Cannacord's numbers of 12.1p.
So that investment is turning a declining business struggling to maintain eps to one with turnover growth and significant growth in eps.
After today's fall, on Cannacord's Aug 29 numbers, Smiths News (LON:SNWS) is on a p/e of 5.8x and a yield of 8.8%. (Oh, and a fee cash flow yield of over 15%)
Obviously there are execution risks, but the mkt seems o me to be very short term.
Is this an issue in theUK? Punishing investment in long term growth?
P.S. I own a few
Smiths News (LON:SNWS)
A temporary profit hit to invest in growing revenues and opening up the possibilites you mention seems perfectly reasonable. I'll be interesting in what the Stocko experts say assuming they review this one today.
cheers Cayman69 - that makes complete sense as explanation and its kinds good reason for them to have the temporary hit if it comes with the payback over the rest of the contract. so happy days unless there are any hidden downgrades today - hopefully they are well placed to beat next time the dial moves rather than downgrade again.
The market initially reacted very positively to these recent contract wins, driving share price to multi-year highs. I did wonder at the time about the huge costs not to mention operational risks of all this expansion - seems the market was somewhat caught out by the actual costs. Quite a hefty 27% downgrade to EPS next year, so after the recent run-up I can't see much attraction in the shares for the time being. Perhaps one to revisit in a year or so as we start to see the upside from these new contracts?
If they hadn't done the recent deals one could assume that revenue would continue to decline at 3% p.a. and cost cutting would have kept eps at 10.1p
They made it clear over the last 6 months that there would be extra costs involved. Both Edison and Cannacord made it quite clear in their notes over the summer.
So the new numbers from Cannacord has t/o falling by -2% to Aug '276, up from -3%.
For Aug 28 t/o, instead of declining 3% again, the new number is up 20%.
For Aug 29, the new forecast t/o is up 2% to £1,263m Without the deals and the costs involved the t/o might have been around £934m.
As mentioned earlier this year, costs have risen. So yes, there is 27% hit to Aug 27 and 7% to Aug 28 eps numbers. But for Aug 29 we may have expected 10.1p again, instead we are looking at on Cannacord's numbers of 12.1p.
So that investment is turning a declining business struggling to maintain eps to one with turnover growth and significant growth in eps.
After today's fall, on Cannacord's Aug 29 numbers, Smiths News (LON:SNWS) is on a p/e of 5.8x and a yield of 8.8%. (Oh, and a fee cash flow yield of over 15%)
Obviously there are execution risks, but the mkt seems o me to be very short term.
Is this an issue in theUK? Punishing investment in long term growth?
P.S. I own a few
If you could cover Smiths News (LON:SNWS) and Made Tech (LON:MTEC) that would be great.
Smiths News (LON:SNWS)
This is new holding for me as I only bought in at the beginning of the month. I think the attractions here are obvious high stock tabk and reasonably lowly rating and generous divi.
Today’s update seems broadly fine the key here that gave me confidence to buy in is their new contracts that seem to provide great base for them to continue to tick over for the next 5 years - there should be opportunities along the way to pimp out the fact they have vehicles out their delivering stuff daily. - lots of scope to tie in here and their to get stuff regularly to fixed locations on behalf of others.
Share has tendered upwards nicely over the last 30 days - rather annoyingly looks like they downgraded 2027 expectations a tad in stocky for new year like 3 days after my purchase - at sane timing upgrading 2026 - with lowly rating though i will overlook that for now - what is key to know is what 2028 numbers will be - if anyone has any clues I am all ears - to me it’s the one thing with stocky often the next year numbers are “awol” and don’t show up till final year finished numbers are banked and closed off - presuming next year forecasts may be released before ye numbers are banked that’s kinda uber annoying bit having info that may exists ? Not sure what the official position is here ? Not all companies will have next year forecasts yet so perhaps it’s me wishing for data that doesn’t exist.
Hopefully ref new year started there won’t be any further chops - I have hopes they will be upping profits not lowering here next 3 years.
In my view it is an underrated stock , it has clear strategy to realign the business and its distribution network is extensive
I also hold. To me, this is a nice profit warning (if there is such a thing). They surprised the market with their recent wins but have now put some meat on the bone regards the inevitable cost of servicing that new work.
A temporary profit hit to invest in growing revenues and opening up the possibilites you mention seems perfectly reasonable. I'll be interesting in what the Stocko experts say assuming they review this one today.
Smiths News (LON:SNWS)
A temporary profit hit to invest in growing revenues and opening up the possibilites you mention seems perfectly reasonable. I'll be interesting in what the Stocko experts say assuming they review this one today.
cheers Cayman69 - that makes complete sense as explanation and its kinds good reason for them to have the temporary hit if it comes with the payback over the rest of the contract. so happy days unless there are any hidden downgrades today - hopefully they are well placed to beat next time the dial moves rather than downgrade again.
The market initially reacted very positively to these recent contract wins, driving share price to multi-year highs. I did wonder at the time about the huge costs not to mention operational risks of all this expansion - seems the market was somewhat caught out by the actual costs. Quite a hefty 27% downgrade to EPS next year, so after the recent run-up I can't see much attraction in the shares for the time being. Perhaps one to revisit in a year or so as we start to see the upside from these new contracts?
If they hadn't done the recent deals one could assume that revenue would continue to decline at 3% p.a. and cost cutting would have kept eps at 10.1p
They made it clear over the last 6 months that there would be extra costs involved. Both Edison and Cannacord made it quite clear in their notes over the summer.
So the new numbers from Cannacord has t/o falling by -2% to Aug '276, up from -3%.
For Aug 28 t/o, instead of declining 3% again, the new number is up 20%.
For Aug 29, the new forecast t/o is up 2% to £1,263m Without the deals and the costs involved the t/o might have been around £934m.
As mentioned earlier this year, costs have risen. So yes, there is 27% hit to Aug 27 and 7% to Aug 28 eps numbers. But for Aug 29 we may have expected 10.1p again, instead we are looking at on Cannacord's numbers of 12.1p.
So that investment is turning a declining business struggling to maintain eps to one with turnover growth and significant growth in eps.
After today's fall, on Cannacord's Aug 29 numbers, Smiths News (LON:SNWS) is on a p/e of 5.8x and a yield of 8.8%. (Oh, and a fee cash flow yield of over 15%)
Obviously there are execution risks, but the mkt seems o me to be very short term.
Is this an issue in theUK? Punishing investment in long term growth?
P.S. I own a few
What have you been waiting for rmillaree? This is new holding for me as I only bought in at the beginning of the month. I've been holding Smiths News (LON:SNWS) right from 2011, only selling twice in bed and ISA adjustments. Seeing the recent rising share prices means to me a lowering dividend and don't envisage buying any more shares beyond a 70 pence price.
Smiths News (LON:SNWS)
What have you been waiting for rmillaree?
a well run buisness in a declining marketplace doesnt have that much interest to me normally - perhaps i have unfairly tarred it with that brush over the years as they seem to have manged to keep profits up with events over the years - so not sure if core sales have held up long term better than expected or they have manged to fine new avenues to mitigtae decline in newspapers (thats alywas the ricky one if you dont know that replacement profits will turn up if main income source is reducing yoy.
the fact that thney have manged the decline so well and the fact they have these new contracts - that kinda says to me that whatever they are doijg has fully worked so they are a different beast from 10-15 years ago when we knew that newspaper sales would cperhaps drop 50% and they needed a cunning plan - they have kinda delivered the cunning plan. Yes newspaper sales will continue to drop going forward - but i would be semi hopeful volume of drop next 5 years will be nothing like prior 10 years - i think sales for year just done in growth verticals were up 30% plus - so i dont know exactly what splits are between newspapeers and magizines and others but it all looks pretty sweet at present overall
were you aware results were today when you bought? buying immediately before trading updates is best avoided unless you’re a gambler. Exact dates are not always provided although I believe they were in this case.