Metro Bank: target lending up 37%, on track to deliver improved profitability

Analyst’s view:
Metro Bank's shift to a specialist lending model appears to be progressing well and is on track to deliver the expected improvements in profitability. My valuation sums suggest that the shares could still offer some value, even after recent gains. I'm comfortable maintaining our AMBER/GREEN view ahead of this year's results.
Up 16.5% to 178p (£1.16bn) - Third Quarter 2026 Trading Update
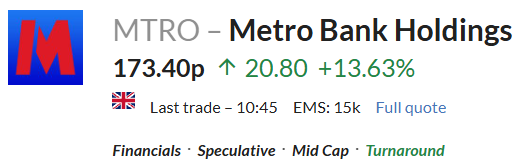
The market has provided a warm welcome for today's Q3 update from this former challenger bank, which our system accurately views as a Turnaround:
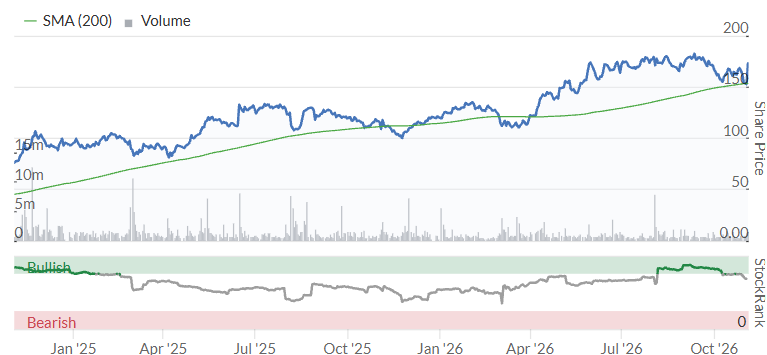
Although the shares remain slightly below recent highs, I think it's fair to suggest that the medium-term uptrend here remains intact:
Q3 update: key points
As Graham has discussed previously, Metro Bank refinanced a few years ago and is evolving into a more specialised lender. As part of this process, the bank is running of some of its loan book while focusing on growth in a number of more profitable target segments, such as commercial lending and specialist mortgages.
Today's statement leads with news that lending in these target growth segments has risen by 37% to £6,619m over the last year.
Checking the numbers, this was partly offset by a 32% decline in run-off lending to £2,806m.
Netting off these two loan books, total net lending has risen by 5% to £9,294m over the last year.
This modest growth rate may mask a larger opportunity. As its legacy loan book declines, Metro should be able to generate more attractive return on equity, potentially with stronger growth too.
I think today's Q3 metrics broadly support this view:
Net interest margin (NIM) up 0.42% to 3.45% - "already within full year guidance range"
"Clear path for further NIM and RoTE expansion across Q4 2026 and 2027"
"Strong credit quality maintained"
Net loan to deposit ratio of 71%, providing "significant capacity for asset growth"
Outlook: importantly, Metro Bank has reaffirmed its profitability guidance today:
Reaffirming all guidance, including RoTE greater than 13% in Q4 2026, greater than 15% in 2027, and greater than 18% in 2028
Roland's view
When I look at banking stocks, I tend to use a combination of price to book value and return on equity (or tangible equity) to gauge how attractive the valuation may be.
Today's share price gain has left Metro Bank trading slightly above its June 2026 tangible net asset value of 166p per share - in other words, a price/tangible book ratio of 1.1x.
I would pair this with the bank's RoTE guidance to gauge whether the shares still offer value.
2027 guidance for RoTE of >15% is quite clear, but I'm not sure what 2026 RoTE is likely to be.
In H1 2026, RoTE was 7.5%, but we're told that Q4 2026 should be over 13%. So perhaps the full-year result will be 10% to 11%?
As a rule of thumb, I want to buy bank shares at a valuation that offers me a return on my cost of equity of at least 10%.
I estimate this by dividing RoTE by the stock's price/tangible book ratio.
For 2026, this gives me a forecast return on cost of equity of just under 10% for Metro Bank. This rises to c.14% in 2027.
On balance, I'd consider this to be a reasonably attractive valuation.
While specialist lenders always carry some risk, Metro Bank has reasonable scale and appears to be in a good place currently.
I don't have the conviction to upgrade our view to be fully positive today, but I'm quite comfortable maintaining our AMBER/GREEN view ahead of this year's results.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Metro Bank Holdings (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?