Weir Group: Q3 orders up 8%, but project delays and market headwinds point to downside risks

Analyst’s view:
Although Weir is very well respected, it's also exposed to the same cyclical and geopolitical pressures as its mining and oil customers. As things stand, I think the valuation is up with events and carries some downside risk if recent trends don't improve. I'm going to open our coverage by taking a neutral view today.
Down 8% to 2,424p (£6.3bn) - Q3 Trading Update
The market appears to be disappointed with today's update from Weir Group, a well-respected provider of mining equipment such as pumps, "wear parts" and equipment attachments.
While today's update is in line with expectations and appears to show positive growth, broker commentary on the Reuters newswire this morning suggests the rate of growth may be disappointing: a Jefferies analysts is quoted as saying that "peers are delivering stronger order intake".
Q3 trading: key points
Group orders +8% including acquisitions, with book-to-bill improving to 1.1x.
Stripping out acquisitions, organic revenue growth was 5% in Q3.
Aftermarket orders +10%, with positive mine activity and particularly good demand from gold, copper and oil sands.
Original Equipment orders +3%, with some project delays and timing effects reported, holding back Q3 performance.
CEO Andrew Neilson flags up a number of sector-specific events that are holding back demand currently, including lower demand from phosphate customers (Middle East) and extreme weather events in Chile.
However, the company has also benefited from higher oil prices through strong oil sands demand.
Overall, I don't get the feeling that Q3 saw any major disruptive or surprise events.
Net debt: Weir says its on track to deliver strong cash generation, before continuing to say that year-end net debt is expected to be slightly above the company's target range of 0.5x - 1.5x EBITDA. These statements do seem slightly contradictory, but I don't see any serious concerns unless leverage rises much further.
Management expects to reduce leverage to within its normal range in 2027.
Outlook
This doesn't sound too bad to me:
We are on track to deliver in line with current market expectations for growth in constant currency revenue and operating profit, with operating margins above 20% for the full year along with strong cash conversion.
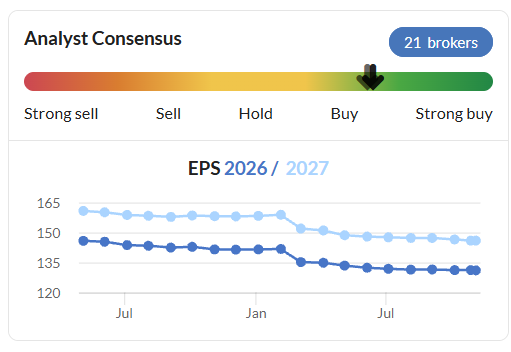
I don't have access to broker forecasts for Weir, but checking the StockReport shows that expectations have trended lower over the last year and were downgraded more significantly following the start of the Middle East conflict:
Roland's view
Our algorithms styled Weir as a High Flyer ahead of today's update, with relatively demanding valuation multiples:
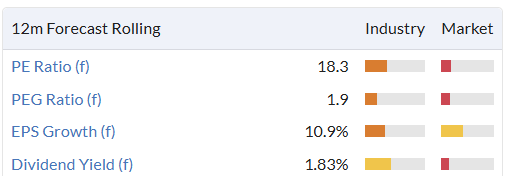
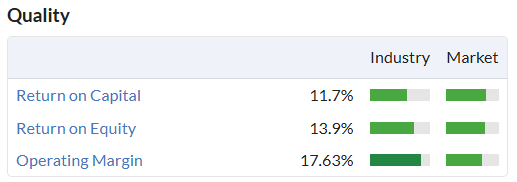
I think this may be at the root of today's share price drop - this valuation seems quite strong to me given the current growth rate and relatively average quality metrics:
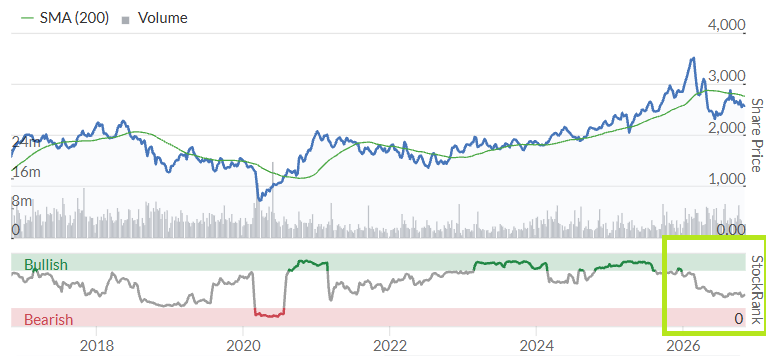
The StockRanks have also turned cautious recently, declining after a long positive run for the stock:
We haven't covered Weir for a long time in the report and this is only a relatively brief review.
However, I can't help feeling that Weir may be at risk of losing its High Flyer status unless the company's performance picks up a little. This could happen if the situation in the Middle East resolves, but I don't think I'd want to bet on that happening very quickly.
Although Weir is very well respected, it's also exposed to the same cyclical and geopolitical pressures as its customers.
As things stand, I think the valuation is up with events and carries some downside risk if recent trends don't improve.
I'm going to open our coverage by taking a neutral view today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Weir (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?