Multibaggers with 10 Bagger Potential - CARD FACTORY (CARD, BYOT, G4M, VEC, CRL, CMCX, CAR, DLAR)

Card Factory - Lowest cost Producer and Vertically integrated Retailer.
15 Jan 2021
Card Factory (LON:CARD) Had a year low of 25p during 2020 having declined 72% by year-end and looks good value at 38p today.
I was encouraged by the sales numbers (£284M FY 21) during the Covid-19 period and cash how cash has been conserved (probably due to government help ).
After 5 years of poor share price performance (Share price moving from 327p to 38p today) valuations look extremely cheap. With Covid-19 vaccines rollouts in the UK, a full recovery seems on the cards by year-end 2021. Add this with the growth engines of online sales and partner sales the future looks bright ex-covid 19. If free cash can return to previous levels this is a very profitable business.
Sales Estimate FY21-FY26

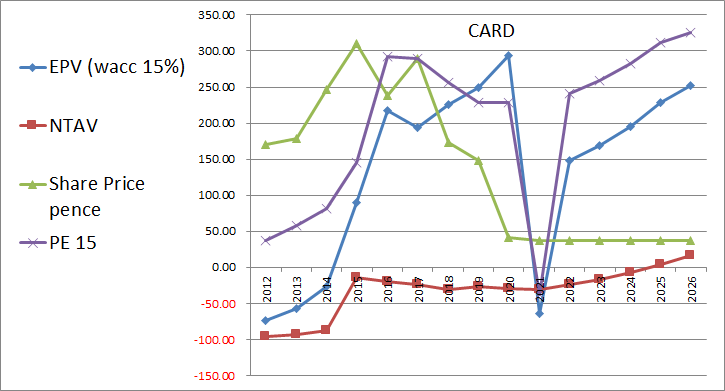
Evaluation model suggests 150p valuation for year-end 2022, (325p upper-end target for 2026). See the graph below
13th Nov 2020
BYOTROL - Byotrol plc is engaged in the development, patenting, licensing, and sale of anti-microbial products and technologies.
Byotrol (LON:BYOT) Had a year low of 1.5p this year and has already multi-bagger at 6.3p today, but this feels like the start of the beginning for this company.
Today's AGM statement was enough to open a new position. Link to statement https://www.stockopedia.com/sh...
( I opened a new long position today, lowest buy price 6.3p).
Byotrol (LON:BYOT) has come of age for a number of reasons including;
- Covid-19 driving the importance of anti-microbial disinfectant for surfaces
- New regulation requiring that disinfectants will be for use in hospitals and will conform with the requirements of the European Biocidal Products Registration and the UK equivalent that will come into force post-Brexit. This is taking many older products out of the market. Even well-established players in the market like Tristel (LON:TSTL) are re-engineering products and finding they need Byotrol (LON:BYOT) IP and products. See attached link, Tristel alliance with Byotrol targets hospitals with the novel product, https://www.businessweekly.co....
- 90% plus sales growth
- 300% plus EPS growth
- Starting to generate positive cash flow and profits.
Sales Estimates FY21-25

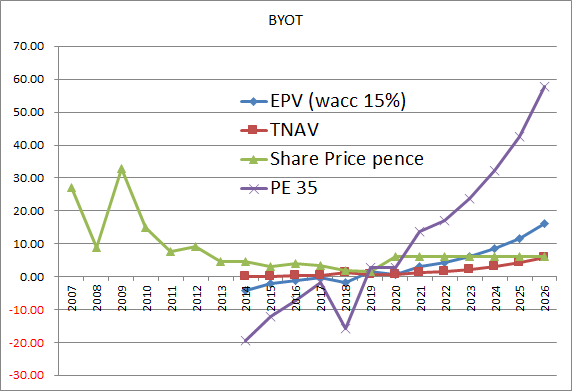
Evaluation model suggests 11p valuation for year-end 2021, (71p upper-end target for 2026). See the graph below
DYOR
BSV
22nd Oct 2020
Gear4Music Holdings - Online Retail
Gear4music Holdings (LON:G4M) hit a new low at 140p in March 2020. (lowest buy price 170p ). ( I hold a long position)
Gear4music Holdings (LON:G4M) half-year report shows continued top-line growth and margin and profit expansion, Sales growth of 42%, profit growth 60%.
With a growing dominant market share in the UK (24%) and growing sales in Europe, the company has overcome its logistics problems reflected in the share price rise. With operations in the UK and Europes, the company is well-positioned for Brexit, and with the continued trending of online retail, there seems like plenty of upside runway.
Sales Estimates FY21-25
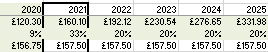
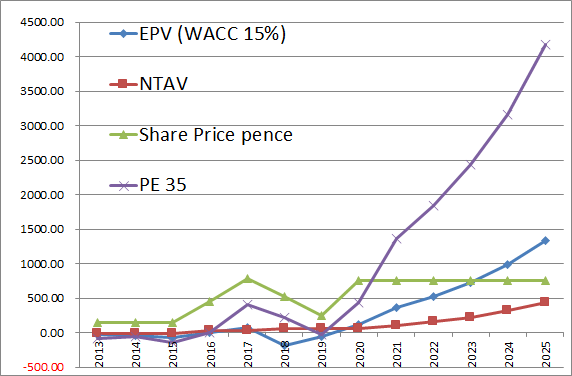
Evaluation model suggests 1100p valuation for year-end 2021, (4000p upper end target for 2025). See the graph below
As always DYOR, don't trust blogs like this one.
CMC Markets - Sustained growth for longer
up-date 8th OCT 2020
Cmc Markets (LON:CMCX) hit a new low at 74p in 2019. (lowest buy price 85p, additional buys at 125p, 175p , 363p ). ( I hold a long position)
Cmc Markets (LON:CMCX) has come out with half-year results today, and make excellent reading;
- CFD net trading revenue of approximately GBP200 million (H1 2020: GBP85 million)
- Group's stockbroking net revenue is expected to increase to approximately GBP26 million for H1 2021 (H1 2020: GBP14 million)
- Following the strong performance in H1 2021, the Board is confident that net operating income will be towards the upper end of the current range of consensus
with the consensus being Profit Before Tax of GBP159.6 million, ranging from GBP149.2 million to GBP175.3 million.
I updated my forecast to reflect the new information.
Year-end sales increase to 52% as client revenues numbers swell, and PBT of approximately £151M.
Some of my build in assumptions include;
- Clients number growth of 30% for FY20/21, 3% thereafter
- Client revenues retention at 80%
- Australia regulation will negatively impact revenues in FY22, -37% (£-17M)
- cost increase by £50M
Anyway, it's enough for me to add to my position at 363p
Sales Estimates FY21-25

Evaluation model suggests 750p valuation for 2021, (1200p upper end target for 2025). See the graph below
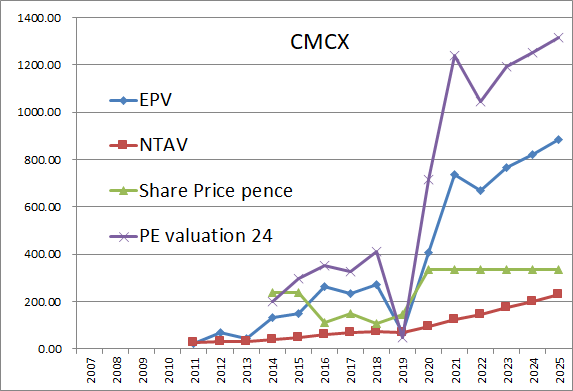
As always DYOR, don't trust blogs like this one.
3rd Sept 2020
Cmc Markets (LON:CMCX) hit a new low at 74p in 2019. (lowest buy price 85p, additional buys at 125p, 175p ). ( I hold a long position)
With £CMC update, what is next for this online financial trading company.
YTD both Cmc Markets (LON:CMCX) has been a useful hedge against turbulent markets, with FY2020 revenue growth of 93% and the share price increasing 125% YTD , is this growth sustainable. with markets still uncertain does Cmc Markets (LON:CMCX) have further to go?
There may reason to like to this share including ;
- improving client revenue conversion
- hedge against client position to reduce risk
- robust client technology (did break down during pandemic trading conditions)
- increasing clients numbers and spend
- Best in class white label technology and market proposition
- 6% plus dividend
I've upgraded my forecast details are provided below.
Sales Estimates

Evaluation model suggests 650p valuation for 2021, (1000p for 2024). See the graph below
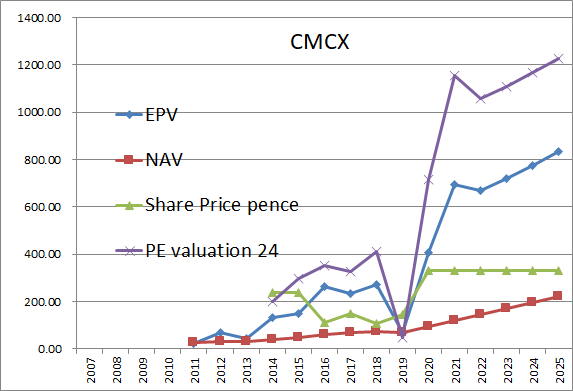
There is a risk of Australia regulating during FY21/22, but this is only 6% of FY2020 revenues if the effect is the same as Europe regulation introduced in 2019.
This is not included in the model shared.
DYOR
BSV
Vectura – IP Growth Portfolio
Posted 15th Sept 2020
Vectura (LON:VEC) hit a new low at 60p on the 17th Mar 2020. (lowest buy price 70p) - (I hold a long position)
Company History
I first became aware of Vectura (LON:VEC) Vectura when it agreed to buy rival SkyePharma £SKP for £441 million pounds in March 2016. The tie-up was intended to create a leading lung disease group with expertise across different inhaler technologies and a combined market value of more than 1 billion pounds. Vectura (LON:VEC) had an extensive IP portfolio but limited cashflow and by contrast, SkypePharma had a limited developing IP but it Flutiform product has started generating significant free cash flow with growing sales.
The combination of SkyePharma with its cashflow and Vectura (LON:VEC) with extensive developing IP looked like a world-beater. (At the time I thought Vectura (LON:VEC) had has been very shrewd have acquired SkyePharma with a growing free cash flow to fund its IP development).
The Company to Today
The company has started to generate significant free cash flow as it has refocused on CMDO (contract manufacturing and development organisation) and reduced R & D costs on its stand-alone IP. (IP without and Biotech/Pharma partner).
Near Term Catalysts for a re-rating
• EXPAREL® – injectable analgesic for post-operative pain relief, sales at $500M will trigger $32M milestone payment (2021)
• GSK Ellipta Vectura (LON:VEC) IP infringement case conclusion would require compensation to the tune of $200M (2021)
• Partnering with Hikma the VR315 Phase III approval for a Advair generic leading to milestone payments and teens % royalties (2H 2020)
A growth development IP portfolio
A growing IP portfolio with a credible partner at various phases of development. Additional 12 agreements signed in 1H 2020.
• BAYER VR876
• Novartis QVM149(Asthma (EU, RoW) (LAMA/LABA/ICS)
• Grifois VR179 (Cystic Fibrosis, Global)
• Ventaleon VR739 (Severe Influenza, global)
• Janssen VR096 (Anti-inflammatory Asthma/COPD, Global)
• Mundipharma VR2076 (Asthma, Global)
• UCB VR942 (Uncontrolled Asthma, Inhaled Biologic Global)
• Ablynx VR465 (FOX device, RSV infection, Global)
• Aerami T. VR325 (FOX device)
Sales estimate FY2020 - 2025
Note : Revenue forecast determined by way of risk-adjusted weight average across all future revenues hence is inherently less stable.

Evaluation model
Fair value estimated at 330p for 2021, and possible 1200p by 2025). See the graph below.
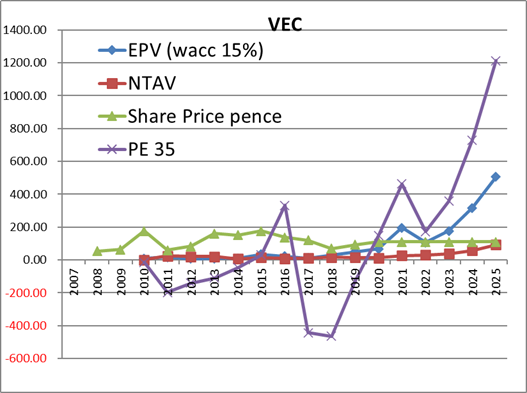
DYOR
Creightons - 10 years of growth at an average of 14% is it time to rerate as a growth stock?
4th Sept 2020
Creightons (LON:CRL) has already been a 10 bagger rising from 2p in 2013. After 10 years of continuous growth (14% Average), the company still appear attractive by a number of metrics.
Creightons (LON:CRL) hit a year low of 29p in Mar 2020 can Creightons (LON:CRL) 10-bag again? (lowest buy 30p, additional buy 57p). (I hold a long position).
After yesterday's results presentation, I am optimistic for growth to continue and the share to re-rate.
The reasons I continue to add to my position;
- I'm a big fan of Global Marketing Director/Deputy MD, Pippa Clark , and her knowledge of the market. She knows how to drive sales growth.
- I'm a big fan of Bernard Johnson and his concern for all stakeholders in the business
- Its a small company with a massive market opportunity
- response to covid-19 was excellent
- 10 years of 14% average growth
- margin expansion
- strong balance sheet
The company's long overdue a re-rating to a growth stock.
10 years of growth
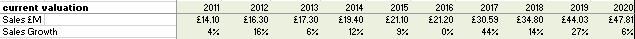
Sales Estimate 2021-2025

With 2021 PE at 10, and PEG of 0.3 my valuation model suggests plenty of upsides. (see below)
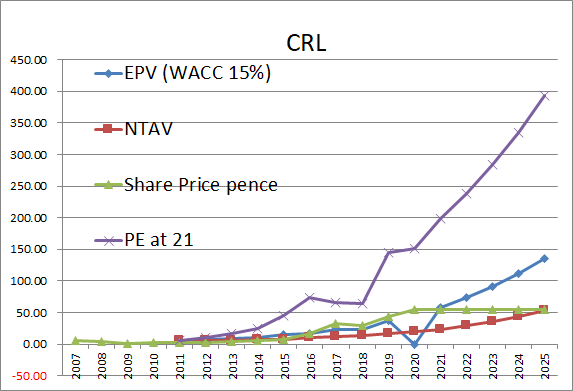
A PE ratio of 21 seems close to fair value for a company achieving consistent growth over 10 years.
My fair valuation for year-end is close to 150p for 2021 and could be as high as 440p by 2025
As always please DYOR. ( Remember I only post these as it benefits me socially and hopefully economically).
BSV
Carlo - Has it turned a corner?
25th Aug 2020
Carclo (LON:CAR) hit a new low of 4p on the 18th of March 2020. ( Lowest buy price 5.1p, additional buys at 11p) - (I hold a long position)
Carclo plc, a global manufacturer, principally of fine tolerance injection moulded plastic parts for the medical, electronics, optics, and automotive safety markets.
With plans in place for cost reduction, debt management, pension payment, and robust sales into medical health markets has this value trap turned a corner?
Having already remove significant cost from the operation and a focus on more stable revenues from the Medical and Aerospace market, this should throw off an additional £10M of free cash flow. The pension contribution is increased by £2M from £1.8M to £3.8M should be comfortable assuming no further deterioration in business. It could take 3 years to repair the balance sheet from free cash flows.
The Net Profits from the Technical Plastics and Aerospace business are better than from the LED Technologies business they just sold (which was loss-making).
Stockpedia suggests Operational Cashflows have actually improved £17M in FY2020 compared to FY19 as a result. See below;
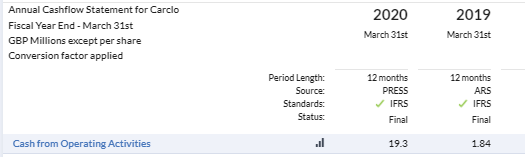
My estimate suggests FY2021 and beyond FCF will be north of £15M, so debt interest payments (£2.5M), and pension payment (£3.7M), are easily covered, and there is plenty of cash to pay down debt or add capacity.
From the market low, any improvement in pension liability will improve the company balance sheet.
The company may decide to raise more cash or improve its position by trading, only time will tell which it chooses. Either way, the investment case should improve as the balance sheet becomes stronger.
Updated with march 2020 results

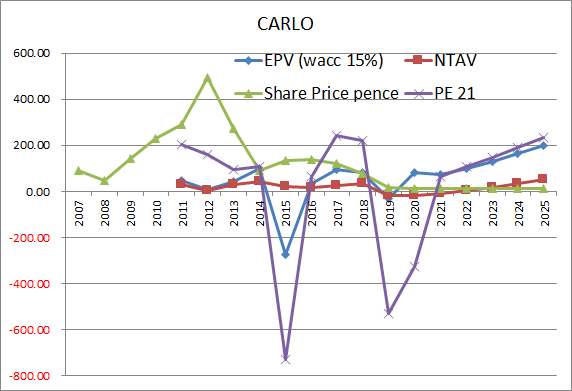
I've updated the model to reflect the 2020 results. Topline revenue is provided above.
Evaluation model suggests 60-70p valuation for 2021, (160-180p for 2024). See the graph below.
DYOR
De La Rue - Accelerating Turnaround
13th Aug 2020
Hit a new low of 41p on the 20th of May 2020. ( Low buy price 48p additional buys at 110p, 120p) - (I hold a long position)
De La Rue plc designs manufacture and delivers banknotes to customers across the world. The Company's segments include Currency, and Product Authentication and Traceability. The Currency segment provides printed banknotes, banknote paper, and polymer substrates and banknote security components
De La Rue (LON:DLAR) looks more attractive every day. Making for an improving business by;
- Cost reduction: The Company is enacting an accelerated cost reduction program with a significant proportion scheduled to complete by August 2020. Targeted savings on an annualized basis from H2 2020/21 will be approximately GBP35 million
- Raising £100M in new equity to sure up the balance sheet
- In Authentication, it has signed a five-year agreement to supply polycarbonate data pages for the new Australian passport. De La Rue's Authentication division has been awarded contracts with total lifetime value exceeding GBP100m
Today announce
'In Currency, De La Rue continues to experience strong demand and has been awarded contracts representing approximately 100% of its available full-year banknote printing capacity for Financial Year 2020/21, an increase on the 80% of capacity announced at its trading update of 1 June 2020.'
Should increase polymer currency sales from £281M to above £320M and provided better margins. Hopefully, they will invest in increasing the capacity with all the money printing going on today.
There's a nice report by Edison if want to know more about the company. (see link below).
https://www.edisongroup.com/wp-content/uploads/2019/01/De-La-Rue-Keeping-it-real.pdf
So what might happen to valuations and the share price?
Based on the following revenue profile ;

The Valuation looks attractive for the next few years. ( see model below)
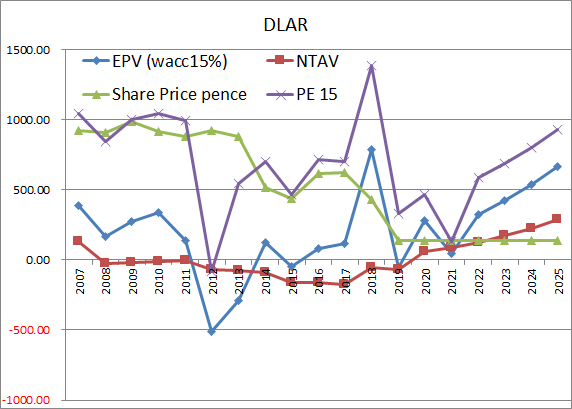
I am hopeful shares will re-rate to £3.00 - £5.00 over the next few years.
.
DYOR
BSV
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
65 comments
Bad luck to holders of CMCX
This was a good one for me as traded in and out in the past couple years.
Not directed at any investor/trader specifically but see regular comments on people not understanding why a share behaves in any specific way and some averaging down, I have been at this for years and to me the shares in a market do what they do rational or not. I think the best thing to do is listen to what the market is telling you and have no feelings to what a share should or not be doing..
For example, to me CMCX was telling me buy (not all the time but often enough) from around late 2019 but in April 2021a downward trend developed - as I sell in to strength whatever I had left of this position in April would have had a stop loss (not a random percentage figure - but for me based on EMA or ATR) as such I would have been stopped out probably mid July. If on the other hand share shows strength and based on my rules after being stopped out I just buy back in.
An anonymous traders point of view - DYOR
Good luck to all traders and investors...
Having held Cmc Markets (LON:CMCX) since summer last year, I got out of CMCX during the middle of July this year for two reasons;
1. A down trend was developing, ie, the share price was trending lower lows and lower highs.
2. More importantly the predicted EPS growth rate for 2022 was negative at -40.6%. Ouch!!
I feel sorry for investors who still hold this share because it isn't a nice experience to suffer a -27% drop in one day.
David.
emphasises the view to set a stop loss and sell if it hits it even if you don’t understand why it has done so!!
I wish I knew GRatnanandan! I am trying to get rid of old habits by not averaging down and cutting losses early but I find that hard to do with CMCX !! I don’t understand present downtrend.
Guess we know now. Profit could be back to 2020 levels or worse given the increased costs - certainly one to ponder.....
Hi dahhad,
I believe the present downtrend is due to the fact that the predicted EPS Growth rate for 2022 is forecast to be negative at -40.6%.
David.
Why are CMCX shares falling in price despite good results being published recently?
Creightons (LON:CRL) released a video on the Emma Hardie acquisition. The link is provided below.
https://bit.ly/CRL_EmmaHardie_acquisition
The main takeaways I took is that,
As always DYOR, watch the video and comes to your own conclusion.
BSV
Well I owe you a beer - LON:CARD has been on an absolute tear over the last few days and whilst I am still nowhere near my in price I am now down less than 50%. Having read some of the chat on LSE there are hints of a short squeeze going on.
Also if Moonpig is worth as much as the market seems to think it is, then CARD need re-evaluating.
Keep up the good work.
Hi Berksbee
All beers welcome.
Let hope the run continues.
£CARD It's only a small position for me. I still expect them to do a cash raise soon and I hope to add more after I can understand the details.
All the best.
BSV
Card Factory (LON:CARD) fundamental look sound. Hopely any new cash raise can be done at a good price.
I see this going all the way to 250p by year-end at this rate.
DYOR
BSV
Hi BSV, just seen you've added LON:CARD. Can I suggest you put a date added at the top of it as it looks at first glance like you added it in August. I have to say a most perplexing add. Background I hold and am well under water with it - and was on the cusp of dumping it - something I am not good at in general - partly because I am a twit and partly because history has richly rewarded me for doing so, keeping LON:AVON @40p and buying an additional chunk of LON:MPAC at 54p spring to mind.
Coming back to CARD, Paul is super nervous about the breach of banking covenant, does this not worry you? Do you have a view? My additional concerns are whether cards are a thing of the past. My counter to that would be people said the same about printed books - and have been proved wrong, but do you have a view?
On a more general note we seem to share quite a few shares in common, BYOT, CRL & more recently DLAR so find this discussion very pertinent.
On the subject of thumbs down, it seems to me that you will be voted down whatever you say. I know it's a point of honour for you but I for one vote you up!
Keep up the good work.
Thanks, Berksbee,
I've added a date.
the bank banking covenant break does not bother me, as its companies already price to go bust and their little danger of a sharp price fall.. The company may need to raise new finance to sure up the balance sheet and this would be a positive step. If they don't they have a robust cash-generating business in normal times, which if my analysis is correct should clean up the balance sheet even after paying good levels of dividends within 3 years.
Again It's a small position for me as there is risk involved and Covid-19 shops need to be open and trading.
As always it important to DYOR and decide what's best for you.
BSV
Just added Card Factory (LON:CARD) to Multibaggers with 10 Bagger Potential - CARD FACTORY.
BSV
Can anybody explain this news?
BYOT
Byotrol plc (AIM: BYOT), the anti-microbial technology company, announces that on 8 December 2020 the High Court issued an order confirming the cancellation of the Company's share premium account and the B shares issued by the Company to capitalise the amount standing to the credit of the merger reserve of the Company ("the Capital Reduction"). Following registration with Companies House, the Capital Reduction became effective on 7 January 2021.
Can anybody explain this news?
It is a way of reorganising the finances so they can pay a dividend in the future.
See the company website here
overall it good news, as the company Byotrol (LON:BYOT) is preparing to pay dividends as it turns profitable.
BSV
CARLO awarded a new framework contract worth £10-15M in 2022 for 10 years.
My models suggested a new fair value of 98p year-end 2021, and 250p year-end 2025.
DYOR
BSV
Vectura (LON:VEC), Advair generic approved. $11M milestone and mid-teen royalties.
Link provided below.
https://www.stockopedia.com/sh...
BSV
Bluesky venture,
i highly appreciate your thread and update, Great work
thanks
Vectura (LON:VEC) wins the court case, potentially wins $200M in damages from £GSK. Link below.
https://www.stockopedia.com/sh...
BSV
Hi Blue Sky - good stuff. I also hold LON:BYOT & LON:CRL - at very similar in prices. The BYOT Results update last month (worth a listen if you have not) talked about multiple imitators with claims of up 99.99% effective - which of course includes 1% effective. Good news that the regulator is cracking down on this. LON:TSTL is my biggest holding and most profitable so inevitably I know a little bit about the market.
Hi Berksbee,
Do have a link to the results update?
BSV
Hi Blue Sky, not the specific link but these are the guys who sent the invite support@investormeetcompany.com.
Byotrol (LON:BYOT) added.
BSV
De La Rue (LON:DLAR) Announce - EXTENSION OF THE BANK OF ENGLAND CONTRACT. This underpins the investment at the ' facilities at Debden which produce some of the most technically complex banknotes in the world'. The link is provided below.
https://www.stockopedia.com/sh...
BSV
Hey BSV, have you looked at Crimson Tide (LON:TIDE) , it's tiny so might be too small for you - but it's got a great recent history of top and bottom lines, has some quality clients and looks set to continue growing with a lot of effort placed on developing the product.
Does not fit my screening criteria.
BSV
I did think that might be the case.
Is it worth putting a note what you screen for or you saving that info for your book :)
Hi IGPJ,
I hold Crimson Tide (LON:TIDE), agree it looks promising. Chart also looks primed for a breakout if next RNS is good!
Or if Helium stop selling!
Thanks, good post. On Creightons (LON:CRL) it is worth noting that they gave an investor presentation recently where they gave a very specific expectation about FY21 which we are now more than half way through. They said they expect sales growth to £55m (from 47.8m) and post tax profit of 7%+. By my calculations this equates to roughly £3.85m or about 5.2p EPS, but I haven't factored in the company's employee share scheme here which dilutes everyone's holdings each year.
Your price targets seem a bit too high for me given the growth rate is reasonable but not stellar and is a bit erratic each year, there is no broker coverage, and for the sector it is operating in. However, I do think a p/e of 13 wouldn't be unreasonable and that still offers decent upside in the current market in both the immediate short-term and the longer-term.
Hi Patrick,
Appreciate the feedback on £CRL. I keener on companies with employee share ownership even if it means some dilution.
The increase from £47.8M to £55M I calculate at 15% Sales growth. My model estimates a £4.14M post-tax profit and EPS increase to 5.66p., even after the dilution. which is a 31% EPS increase. So maybe a little bit more optimistic than your calculation.
I've ready decided to accumulate stock with a personal 20+ PE price tag. I hoping the market will catch up with my view at some point.
Either way, the shares are reasonably priced and I'm happy to accumulate.
BSV
I think that this is a very interesting piece and has a lot of merit. However, with regard to the share price line on the graph, I see that it stays flat on the forecasts. May I suggest that you either, remove the forecast element of the share price from the graph, or take a more difficult, and possibly more rewarding approach, and make an attempt to predict the share price. Of course, if you do this, then it might only be worthwhile to do it for the next couple of years.
I disagree, I think keeping the share price flat show you the delta between what you would've paid when the chart was drawn and the other indicators of value - you can draw your own conclusion about share price expectations :)
The future share price is really not something I can forecast, but useful to see against potential valuations based on NTAV, EPV and PE.
NTAV provides a very conservative value
EPV provided a reasonable valuation without further growth.
PE provides a reasonable valuation with growth priced in.
BSV
Gear4music Holdings (LON:G4M) added
Miles Costello is a multi-award-winning journalist who has been with The Times since 2005. He is an investment editor, in charge of the Tempus column, has written a nice piece on De La Rue (LON:DLAR),'Mark of distinction for De La Rue turnaround'. Well worth a read. link included below. (note it behind a paywall.)
https://www.thetimes.co.uk/art...
BSV
Nice Telegraph report on De La Rue in talks over Covid travel certificates.
https://www.telegraph.co.uk/bu...
BSV
CMCX updated.
It's all going better than expected for the companies highlighted in this blog (see graph below). Good luck to any holders out there.
BSV
Misleading chart, it should start at 1. Vectura (LON:VEC) has gone up 0.4 not 1.4.
Hi Hebie47,
Your interpretation is correct for the gain multiple, i.e;
1.4 x original share price represents a 40% profit
0.5 x original share price represents a 50% loss
Kind regards,
BSV
Vectura (LON:VEC) added
BSV
Carclo (LON:CAR) - looking at their gross profit from the recent results, assuming they remain the same, will a large chunk of those profits not be taken up with pensions deficits and interest payments for some time to come? The pension deficit is massive and with interest rates low, it will take them 30 years to clear the deficit...
Hi Cyber Bub,
Not sure if I can deduce much information from profits at this stage.
The Net Profits from the Technical Plastics and Aerospace business are better than from the LED Technologies business they just sold (which was loss-making).
Stockpedia suggests Operational Cashflows have actually improved £17M in FY2020 compared to FY19 as a result. See below;
My estimate suggests FY2021 and beyond FCF will be north of £15M, so debt interest payments (£2.5M), and pension payment (£3.7M), are easily covered, and there is plenty of cash to pay down debt or add capacity.
From the market low, any improvement in pension liability will improve the company balance sheet.
The company may decide to raise more cash or improve its position by trading, only time will tell which it chooses. Either way, the investment case should improve as the balance sheet becomes stronger.
DYOR
BSV
For a share with ten bagger potential (again), check out Solgold (LON:SOLG), all the value is in the ground for which they have exclusive licences across Ecuador. Check the metallurgical maps for yourself, it’s public data. Just need to buy and hold, future Tier 1 mining company in the making; Gold, Silver. & Copper. Chart looks like it could be showing some consolidation at current level so could be ready to move soon too.
Personally, I can’t see Creightons (LON:CRL) ever getting to a P/E of 20 and I would be amazed if it hit 15.
They’re just a run of the mill consumer defensive making soap and similar, there’s no moat, the brand(s) doesn’t have any value and a big chunk of their revenue is just churning out products for supermarkets.
I held it from the false profit warning a couple of years back and sold recently for 55p. I’ll happily buy it back at 50p but I think it’s valued about right.
I also hate the way they often release news at a random time of day instead of 7am - no excuse for that and just feels like a middle finger to smaller investors.
Hi
A very reasonable view to take. The current share price is fair for the current level of business and assuming no growth, or as I like to think about it the growth is free of charge at this share price. (PE of 9.7 for 2021)
Historically, PE has been over 15 for many years and reached a high of 24 in 2017, with 10 years of EPS growth at 31%, it has always looked cheap.
Going forward I've estimated EPS growth of 21% on 11% of sales growth and would be happy to pay up even if the PE reaches 21. The PE would need to reach 48 before the growth was fully paid for.
See note below-showing compounding growth (10 years) and appropriate PE multiple.
Compounded Growth 0%, PE Multiple 8.5
Compounded Growth 5%, PE Multiple 18.5
Compounded Growth 10%, PE Multiple 28
Compounded Growth 20%, PE Multiple 48.5
etc etc.
I won't sell any stock due to valuations until it reaches at least a PE of 30.
As a consumer defensive, it's come through a recession extremely well and one of the reasons I wanted to invest.
Moats are always difficult to determine, but with a ROCE of 22 and ROE of 26, I suspect their white label customers are quite dependent on Creightons (LON:CRL) expertise and can provide a moat of sorts.
I'd also like to buy more at 50p.
DYOR
BSV
Well, we've got our 50p shot. Looking good for a re-entry.
We did indeed, good call. Added more £CRL last week.
BSV
.
Creightons (LON:CRL) added
£cmcx added.
In this sector I prefer IG Group (LON:IGG) (I hold)
Only in that they have a very good platform and don't take the other side of clients' bets like a bucket shop. I don't know if CMC do this. Appreciate that higher margins can be earned this way but in the long run IGG are more likely to survive the test of time and any tightening of the regulations.
Hi Jwebster
I also like Ig Group (LON:IGG) and have a position in the stock. Cmc Markets (LON:CMCX) also hedge their client positions like £IGG. The level of hedge and costs/exposure are guarded secrets by both companies as this is how they compete. Both companies also keep very strong balance sheets to guard against any unhedged position which might go wrong.
The large positions from high-frequency traders cause the highest risk. Cmc Markets (LON:CMCX) decided to co-locate close to the exchange to reduce the risk of high-frequency trading. By co-locating they hedge as close to real-time as possible. hence reducing the risk.
As always DYOR
BSV
Nice upgrade by Peel Hunt on Cmc Markets (LON:CMCX) on Citywire.
Peel Hunt upgrades ‘cheap’ CMC Markets
Peel Hunt has lifted CMC Markets (CMC) from ‘add’ to ‘buy’ as the spread betting and share-dealing platform continues to benefit from a surge in investor trading.
Analyst Stuart Duncan raised his recommendation and increased his share price target from 340p to 380p after an unscheduled update yesterday. The shares initially advanced 3.7%, or 11.5p, to 323.5p before succumbing to the late afternoon market sell-off to close 1p down at 311p.
‘CMC [continues] to enjoy strong trading levels across both contracts for difference and stockbroking,’ he said. ‘While trading is strong, there are other important points with regards to CMC: the group has a well invested, resilient platform, client recruitment remains positive, and active clients remain at elevated levels.’
He added that the group has ‘huge potential to monetise the technology platform’ and the stock is ‘cheap’ trading on less than eight times forecast earnings.
BSV
As a newbie, where can I find info on forecast earnings mentioned here, and how reliable would those numbers be?
Hi Gareth,
There are a number of places you can get forecasts;
The future numbers always have some uncertainty.
Hope this helps.
BSV
Ig Group (LON:IGG) announced Q1-FY21 revenues then Q1-FY20. Will this continue. Long term revenues are best estimated by the growth and decline of client numbers. With client numbers increasing 50%, this Q1 revenue uplift seems more sustainable.
With my estimated sales for FY21 now £780M (FY-20 £664M), my estimated fair value is FY2021 is 1100p. See model below. The read-across to Cmc Markets (LON:CMCX) bodes well.
(I hold a long position in both Ig Group (LON:IGG) and Cmc Markets (LON:CMCX))
DYOR
BSV
Carclo (LON:CAR) updated with march 2020 results.
BSV
Why the down arrows? (-2 at the time writing). BSV merely telling us he's updating his numbers after results on some already good work on this blog - for free! I just don't understand the rudeness. It's not the Daily Mail comments section.
Anyway, thumbs up from me Mr Blue Sky and thanks for running this blog.
Hi Grendel,
Appreciate the thnk you.
BSV
My choice would be Amur Minerals (LON:AMC)
https://www.stockopedia.com/content/amur-minerals-lon-amc-the-start-of-the-final-rise-nickel-mining-628718?order=createdAt&sort=desc&mode=threaded
Good luck if you decide to invest and with your other choices.
Hi BSV,
I am not sure from where you are taking the implicit forward view Carclo (LON:CAR) ? I would just caution that they have been woeful (to be kind) in predicting the future in the past.
Hi Gromley,
Yes, Carclo (LON:CAR) is speculative. Carclo (LON:CAR) future market is very different from the past. the future view is not dependent on the past.
Best regards,
BSV
£Car added