Multibaggers with 10 Bagger Potential - Gear4Music Holdings (G4M) - Balancing Covid-19 boost to longer-term structural trends

Updated 22nd April 2021
Gear4Music Holdings - Balancing Covid-19 boost to longer-term structural trends
Gear4music Holdings (LON:G4M) hit a new low at 140p in March 2020. (lowest buy price 170p, New buy at 821p ). ( I hold a long position)
$G4M year-end results https://www.stockopedia.com/sh..., show 31% revenue growth and estimated ESP growth at 349% (based on EPS of 55p) as gross margins improved to above 29%. Clearly, Covid lockdown has contributed to this boost and accelerated the structural change to online retail. Brexit seems to have strengthened UK market dominance and warehousing and logistics Investments in Europe has accelerated overseas growth.
My forecast shows a slow down of growth in 2022 before picking up in 2023 as structural changes continue. (see below).
Sales Estimates FY21-25

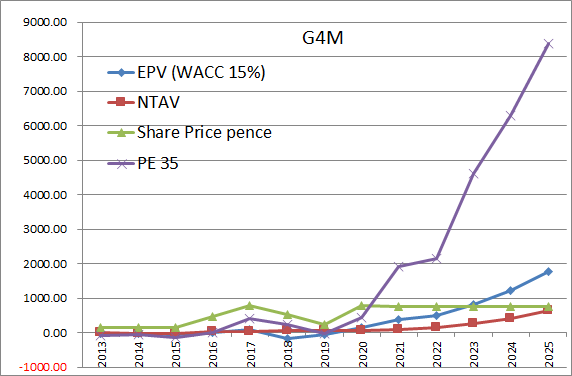
Evaluation model suggests 1280-2000p valuation for year-end 2021, (6800p upper end target for 2025). See the graph below
DYOR
BSV
22nd Oct 2020
Gear4Music Holdings - Online Retail
Gear4music Holdings (LON:G4M) hit a new low at 140p in March 2020. (lowest buy price 170p ). ( I hold a long position)
Gear4music Holdings (LON:G4M) half-year report shows continued top-line growth and margin and profit expansion, Sales growth of 42%, profit growth 60%.
With a growing dominant market share in the UK (24%) and growing sales in Europe, the company has overcome its logistics problems reflected in the share price rise. With operations in the UK and Europes, the company is well-positioned for Brexit, and with the continued trending of online retail, there seems like plenty of upside runway.
Sales Estimates FY21-25
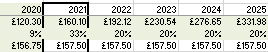
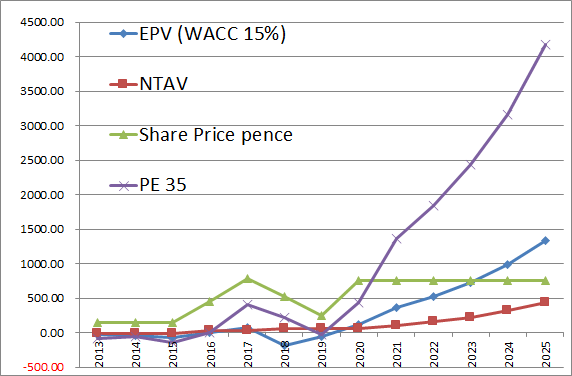
Evaluation model suggests 1100p valuation for year-end 2021, (4000p upper end target for 2025). See the graph below
As always DYOR, don't trust blogs like this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
4 comments
Having grown up in York, I've been aware of Gear4music Holdings (LON:G4M) for a long time now but have never bought at the prices I know I should have. Easy to say with hindsight.
I was looking at it seriously last April (c.200p) and May (c.300p). The margin improvements were well flagged at the time but for one reason or another - just general Covid disruption, I suppose - I didn't buy.
Since then I've toyed with the idea but I've been anchored to those earlier prices. It's clearly just psychological bias at play... So I bit the bullet and bought in after the most recent results. It still looks cheap compared to other ecommerce plays on sales multiples, and there's plenty of growth potential. Plus it looks like management has learned some hard lessons re. expansion, margins, and the rest.
Best of luck. See you in 2025 at 4,000p (!)
It's easy with hindsight, I held in 2019 but shares went down 20% to 206p, so I sold out. Only just bought back in Feb '2021, I also have a problem buying shares that have gone up a lot in price.
One issue with (LON:G4M) is the spread is quite wide and sometimes price quotes are not available on my platform, which means it's fairly illiquid.
Hi BSV
I've done my own modelling and come up with a 3,200p valuation based on conservative assumptions of 2027 EPS of 160p and PE of 20. All quite modest really. I am very interested in the news that they are looking at new 'verticles'; in English this appears to mean new market segments. I wonder what they have in mind?
Re mine and your modelling - what ever the outcome it appears very likely that this is a classic coffee can stock that in a few years will be worth substantially more than now...and quite possibly in a further years will have increased substantially more. The large fragmented markets appear to be a massive opportunity for a pure web play company. Eg the largest company in US Guitar Centre was restructured in Nov 2020 under Chapter 11. It still has 100s of stores around the US...perhaps this is one of G$M's verticles? I know they sell there but they do not appear to have a large presence yet..
Anyway, I'm delighted to hold this share and intend to do so for some time to come.
Best wishes
Martin
Hi Martin,
$G4M. The new verticals could be geographic, although I read they plan to take on the second-hand instruments market at some point, hopefully, we get more information when full-year results are announced.
BSV