My highlights from Mello 2025

Last week’s Mello London 2025 conference provided a welcome opportunity to catch up with my fellow Stockopedia scribes and the wider private investor community.
As always, there was also a well-curated selection of companies presenting and a chance to gain valuable real-world insights from a range of accomplished investors.
Here are two of my highlights from Mello.
Who will buy the shares from you?
One of the more thought-provoking presentations I saw was from fund manager Alyx Wood of Kernow Asset Management. Kernow is a small fund focused on contrarian opportunities, where there’s the prospect of a catalyst to realise fair value.
Wood’s presentation was about Saga (LON:SAGA), which is currently one of the larger positions in his fund. In brief, his thesis was that this was a good business that had been mismanaged and had then had to face the additional complications of Covid.
Now that the company is back under the leadership of the founding De Haan family, Wood believes the grey pound – the outsized purchasing power of the over-50s – will prove sticky and resilient, allowing Saga to rebuild its profits.
In parallel, the company’s decision to sell its underwriting business should reduce capital requirements, improve profitability and aid a continuing reduction in net debt.
My key takeaway: what’s the catalyst?
I think Saga is an interesting investment idea that could be worth further research. But the main takeaway for me was the process Wood described for how and why he expected the re-rating of Saga stock to take place.
When analysing turnaround and value situations, it’s easy to focus on the fundamentals and value proposition without asking what actually needs to happen to trigger a re-rating. In short, we need to ask who the marginal buyer might be.
Share prices only rise when buyers outnumber sellers. While private investors may be the marginal buyers for very small companies, institutional buying is needed to drive larger businesses to significantly higher valuations.
Wood’s focus on catalysts makes this process explicit. Among the factors he highlighted were having line-of-sight to leverage falling below 4.0x EBITDA and Saga’s expected return to profit in FY26.
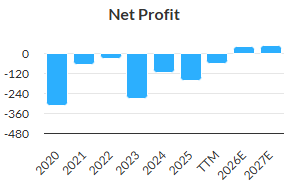
Looking beyond this, he suggested that Saga was likely to resume dividend payouts when possible. At that point, he expects the stock to become eligible for a much wider range of funds, potentially triggering a wave of institutional buying (and a re-rating).
I think there are some interesting analogies here with pub chain Marstons (LON:MARS), whose FY25 results I covered in the DSMR on Tuesday.
Marston’s profitability improved last year, while its leverage fell from 5.3x to 4.6x EBITDA. The company made the following statement in this week’s full-year results:
the Group remains committed to reducing leverage to less than 4.0x and expects to recommence shareholder returns at this point
Marston’s shares closed up by nearly 20% on Tuesday. I would argue that it was this commitment played a role in this sharp rise.
My key takeaway from Alyx Wood’s presentation was that it’s always important to remember how the market works. We can be right on value in an investment, but still be out of the money for a long time if there’s no catalyst in place. I know this is a mistake I’ve often made.
Fortunately, Stockopedia’s MomentumRank can be a very useful way to track changes in market sentiment and trading volumes. When paired with the Value and Quality ranks, it can provide us with a measure of how these different factors are changing.
If we consider the StockRank for Saga, momentum is already strong:
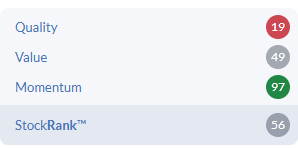
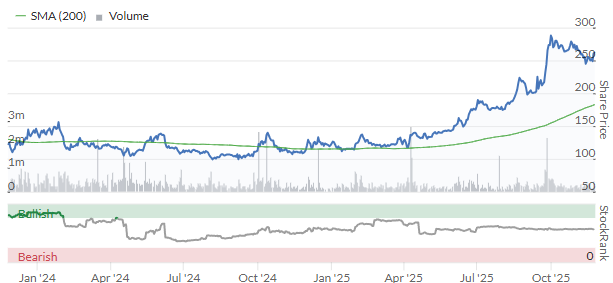
If Saga returns to profitability as expected, I’d expect its QualityRank and StockRank to also improve. In that scenario, I think there could be a nice setup in place for a continued re-rating:
Personal group (LON:PGH)
One of the company presentations I particularly wanted to catch was from workplace benefit and insurance provider Personal Group.
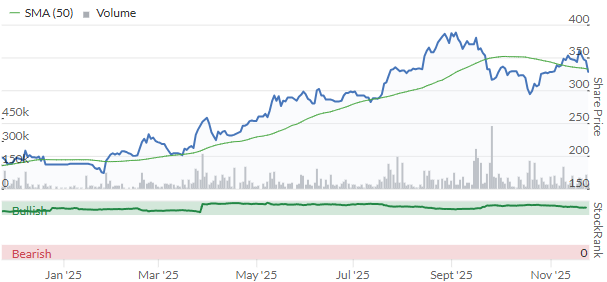
This unusual small-cap financial is a member of my SIF Folio and a personal holding. It’s been trading well over the last year, aided by a steady recovery in profits:
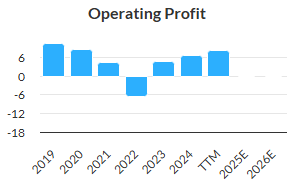
I was interested to learn a little more about the company’s products and business model and was able to chat to CFO Sarah Mace after the presentation to fill out a few gaps in my knowledge.
The insurance side of the business generates around 70% of profit and was my main focus, as I see this as also being the company’s most distinctive asset.
Personal Group offers three types of insurance:
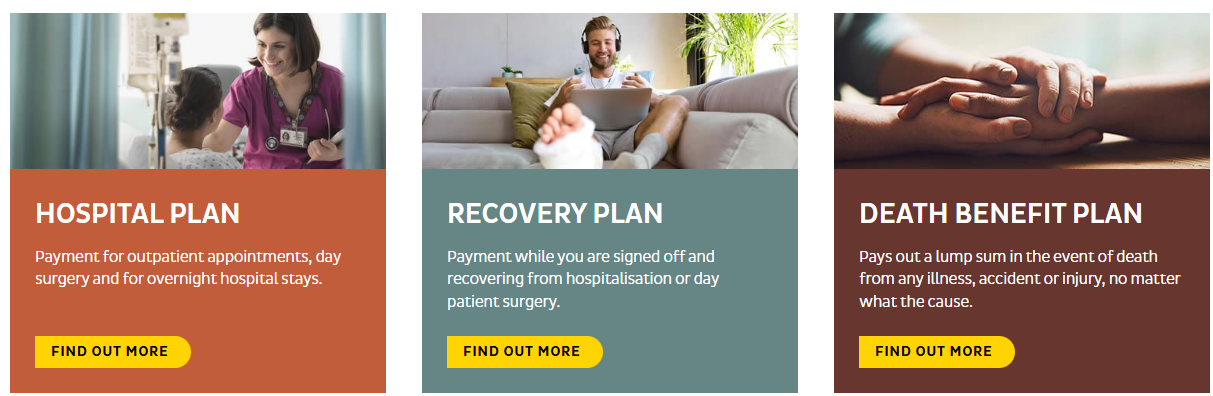
These products are primarily aimed at blue collar workers in sectors such as logistics, where employer benefits may be limited to statutory sick pay and are unlikely to cover the loss of overtime pay.
Pricing is intentionally simple and works on a flat rate, menu basis. Employees can choose the level of payout they would like and will pay a fixed price, without any individual pricing for risk factors or pre-existing conditions.
Personal Group underwrites the insurance itself through dedicated subsidiaries. The company reported “100,000 insurance payers” in its FY24 results. Across such a large population of workers in similar roles, I’d imagine it’s possible to model likely sickness and absence profiles quite accurately – especially as Personal Group has worked with some customers for many years.
Source: Personal Group H1 25 presentation
One distinctive characteristic of the business is that insurance is sold face to face, by dedicated sales teams who visit the site. Management says this approach generates a c.50% conversion rate and 80%+ retention rate.
The company is also keen to emphasise that it’s the “only employee benefit provider delivering in-person face-to-face benefit consultation and insurance advice”.
Competition was a frequent theme in the Q&A at the end of the company’s presentation. Face-to-face selling certainly seems to have some advantages, driving an apparently high conversion rate.
My feeling is that Personal Group may be large enough to make it difficult for a new competitor to gain a foothold in its core markets without incurring big startup losses.
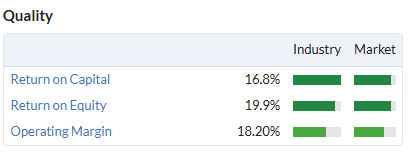
The company’s excellent quality metrics also suggest to me that it could become a little more competitive on pricing if the need arose:
In terms of new products, Personal Group is currently in the process of trialling a digital insurance product and launching a group cash plan on a partnership basis with a benefits provider. Both measures seem likely to expand its market reach, without requiring major investment.
Growth plans: CEO Paula Constant joined the firm in 2023 and launched a strategy update last year aimed at targeting an additional 300,000 eligible employees by 2030. The aim is to do this through a combination of increased penetration and new client wins.
Penetration of existing clients was 13.7% at the end of H1 2025 (FY24: 13.0%), so it seems fair to suggest there’s some room for improvement here.
Similarly, new client wins have provided “line of sight to c.25k new employees”, so progress looks positive in that area, too.
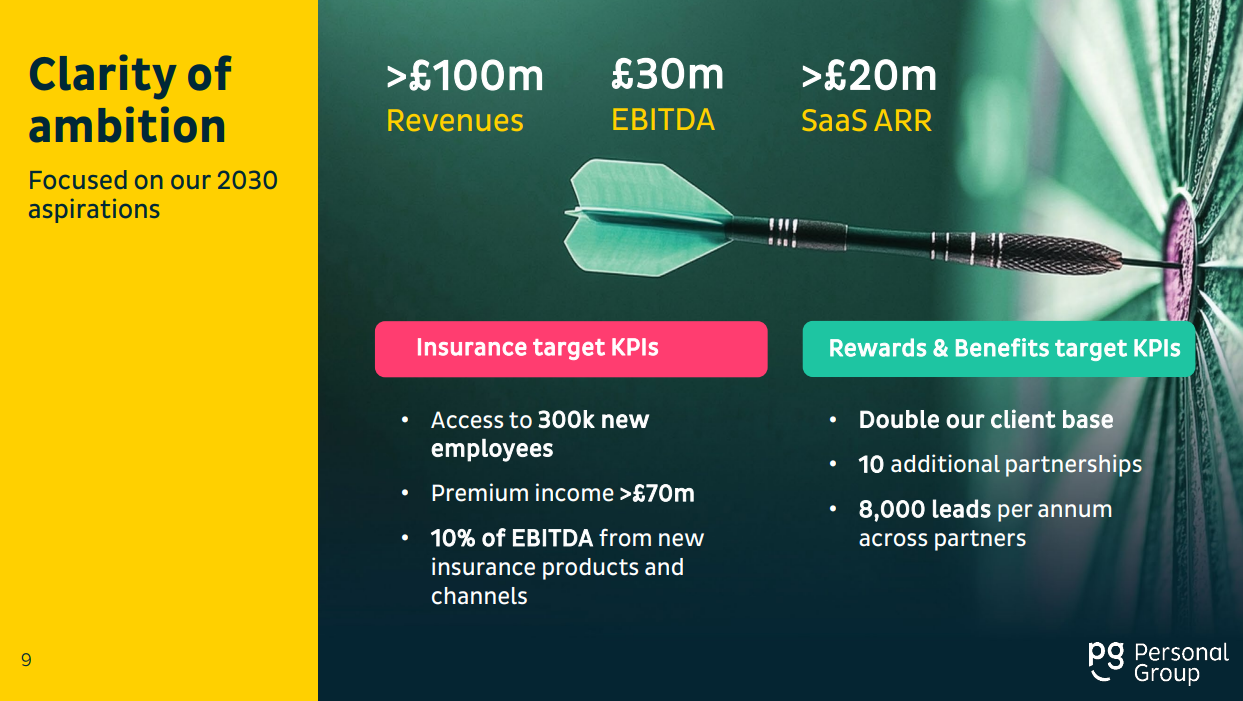
The financial targets attached to this plan are to achieve revenue of >£100m and EBITDA of £30m by 2030:
Source: Personal Group H1 25 presentation
Based on the company’s FY24 results, this implies annualised revenue growth of c.15% and annualised EBITDA growth of 20% over the period from 2024-2030.
Early progress seems encouraging, although revenue growth so far has been slightly behind the revenue growth rate needed. Revenue from continuing operations rose by 13% in 2024, while consensus forecasts on Stockopedia suggest revenue will rise by c.10% in 2025.
If Personal Group does achieve these 2030 targets (or get close), I think it could certainly justify a significantly higher valuation for the stock.
100% dividend payout: this has always been a cash-generative business. Personal Group stock has often sported an attractive dividend yield.
However, the disposal of the more capital-intensive Let’s Connect business last year has freed up some capital from the balance sheet and improved profitability. This was one factor behind the board’s decision to commit to a new dividend policy targeting a c.100% payout of earnings each year from FY25 onwards.
At the end of H1, the balance sheet sported a c.£27m net cash position, of which around £17m is considered to be surplus to requirements – the remainder is needed for insurance regulatory capital and an associated buffer.
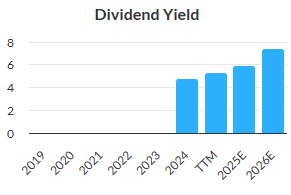
As things stand, recent weakness has left the stock with a near-6% yield for FY25, potentially rising to more than 7% in FY26:
I don't see any reason why the payout shouldn't be affordable, at least in the short-to-medium term.
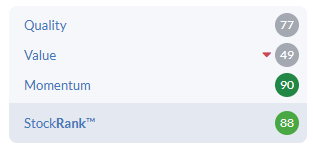
My view: I remain broadly positive on this business, which scores fairly well with our algorithms and seems to have a strong position in a profitable niche market.
Leaving aside the risk of mismanagement (which applies to all businesses), my main concern is the same one I’d flag up with most other niche financials; regulatory risk. We've seen this affect listed companies plenty of times before - PPI, personal injury claims, high cost credit, motor finance and GAP insurance are all examples that come to mind.
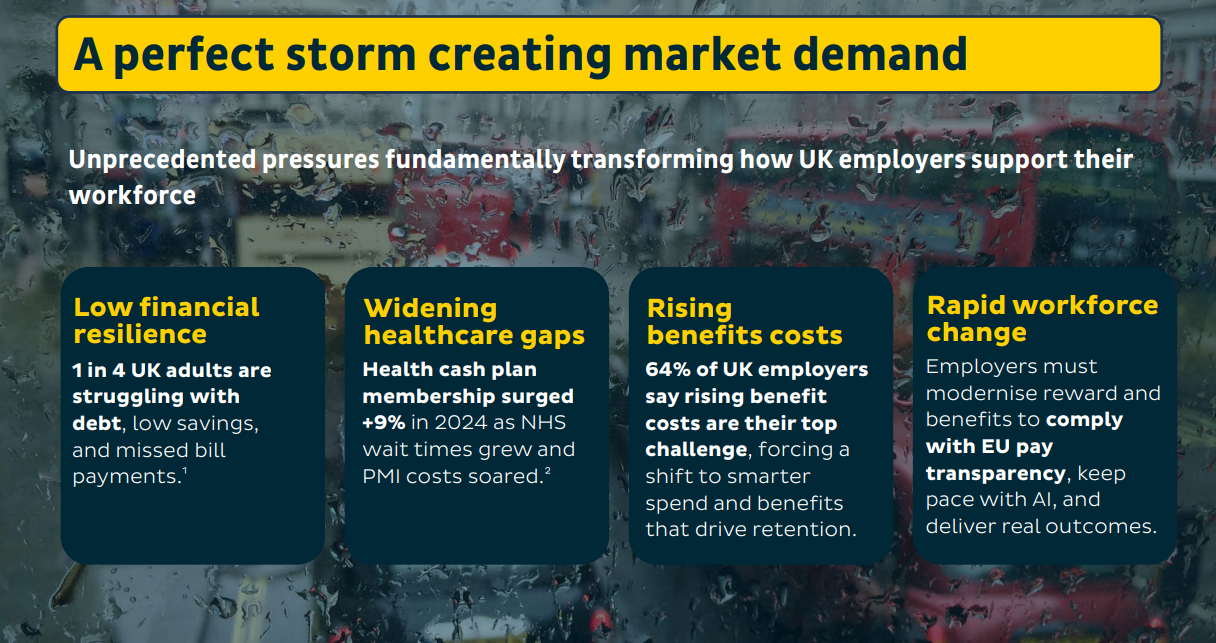
Looking ahead, my impression is that demand for healthcare and income protection products is growing and likely to continue doing so. This is certainly the company’s view on its growth opportunity:
Source: Personal Group H1 25 presentation
Against this backdrop, I’d speculate that it’s possible that at some point in the future, the regulator might turn their attention to this market.
To be clear, I have no reason to suspect any problem at the moment and I note that Personal Group's retention rates are high, at over 80%, suggesting customers are happy with the service and value they receive.
I also remain a shareholder in Personal Group. But this kind of risk is enough of a concern for me that I’d probably not want to make this stock (or any other niche lender/insurance company) an overweight position in my portfolio, despite the tempting cash-backed income and potential growth that may be on offer.
Disclosure: at the time of publication, Roland owned shares in Personal Group.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

4 comments
Saga (LON:SAGA) has jumped today another 8% and is up 60% since 19th August. With a Momentum score of 98 the stock is on a real roll. A very timely purchase of 1.2m Shares by Roger De Haan on 26th Sept was a good example of following major buys by a big Shareholder. He holds close to 40 million shares over 27% of the Company.
Saga (LON:SAGA) The 'grey pound', aka the Bank of Mum and Dad, and its wholly owned subsidiary the Bank of Grandfather and Grandmother, are facing increasing demands from the younger generations, e.g. housing, and HM Government, e.g. inheritance tax on pensions. I remain to be convinced that Saga and other holiday companies are anywhere near the front of the queue.
Thank you for your views on Saga (LON:SAGA) Roland which I have held since 2021 and added in August at 199p.
I think Saga (LON:SAGA) has made significant progress under the new Management and the fact they collect cruisers from their home and take them to the Ship ensures they get a significant amount of repeat business. A strong hold for me.
It was good to see so many of you at MelloLondon and if you missed it and wish you hadn't then please note Mello2026 will almost certainly be on the 2nd and 3rd June next year so book that date in your new diaries