NatWest: Time for a closer look as banking booms

After a lost decade, is it finally time to invest in the UK’s last bailed-out bank?
Recent results from Natwest (LON:NWG) (formerly RBS) suggest to me that there are some clear attractions here, despite the risks posed by rampant inflation and a possible recession.

Stockopedia’s algorithms seem to share this view. NatWest is also a member of Ed’s 2022 NAPS portfolio – you can find his January write-up here.
To find out more I’ve decided to take a deeper look at NatWest in this week’s article.
A good story?
Subscribers who have followed the progress of my rules-based SIF portfolio will know that I am very much a systematic investor. My choices are governed first-and-foremost by the numbers.
However, despite my fondness for data, I’m still keen to understand the story behind a stock. In the case of UK banks, I think the story is unusually simple and compelling right now – although as with all good tales, there is a possible plot twist at the end.
After a decade of ultra-low borrowing costs and abundant money, the Bank of England is raising interest rates as fast as it dares.
For a whole generation of investors, this is a brave new world. Many have never known rising rates. However, for the big banks, I think rising rates could herald a glorious return to form.
Near-zero rates forced banks to cut their net interest margins in order to remain competitive in the UK’s mortgage market. A bank’s net interest margin (NIM) is the difference between the interest it pays on deposits and the rate it earns on lending.
Savings rates couldn’t go below zero, but mortgage rates had to come down. Hence the squeeze. Rising interest rates are now allowing mainstream lenders like NatWest and Lloyds to expand their net interest margins.
NatWest’s NIM rose by 0.24% to 2.59% during the first half of this year, “driven by the impact of base rate rises”. A 0.24% increase is pretty huge, when you consider that the group has net lending of £362bn.
The increase in NIM drove a 20% increase in total income (revenue) to £6.2bn. Although higher costs limited profit growth, adjusted return on tangible equity rose from 12.8% to 14.1%.
The risk, of course, is that rates are rising in a bid to address very high inflation. If this triggers a recession, banks could see a slowdown in new lending and a rise in bad debts.
Cheap, profitable and growing?
The holy grail of equity investment is a business that is cheap, growing and becoming more profitable.
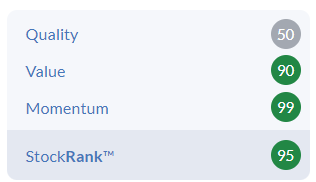
As Ed noted recently, this perfect stock doesn’t exist. But NatWest’s StockRank of 95 suggests it may have many of the attributes I might be looking for.
Value: Despite this year’s share price gains, NatWest shares continue to trade below their tangible book value of 267p per share. The stock also looks modestly valued against recent earnings and dividends:
- TTM PE ratio: 9.1
- TTM dividend yield: 4.3%
Both figures are well below the FTSE 100 averages shown in Stockopedia:

NatWest’s share price discount to book value suggests that the market may still be unsure about the safety or profitability of the bank’s assets (loan book). I’ll look at profitability in a moment, but let’s start with safety.
In its recent half-year results, NatWest reported a regulatory Common Equity Tier One ratio of 14.3%. For contrast, the equivalent figure in 2006 was 7.5%. This tells me that NatWest has expanded its equity base and has much more capital available to absorb future losses than it did before the financial crisis.
I don’t think investors need to be too worried about the strength of NatWest’s balance sheet.
Quality: If NatWest’s balance sheet is strong but the shares are still trading at a discount to book value, then what’s the problem?
The most likely explanation is that the market is still questioning the profitability of the bank’s assets. In recent years, I think this would have been a fair criticism:

NatWest’s return on equity has averaged just 3% since 2016. I think it’s reasonable to assume that this was below the bank’s cost of equity capital. In effect, NatWest has been destroying shareholder value. This is nicely illustrated by the bank’s falling book value per share over the same period:

In my view, NatWest’s low valuation has been justified by poor profitability in recent years. But I think that picture may now be changing.
In 2019 and 2021, NatWest delivered a stable return on equity of around 6.5%. Broker forecasts seem to suggest that this could increase to around 8% for 2022, and perhaps 10% in 2023.
If the bank’s profitability does continue to improve, then I think a stronger valuation could be justified.
Momentum: A MomentumRank of 99 suggests that the outlook remains positive. I can see very little to find fault with here, with one possible exception.
The technical forces driving up NatWest’s share prices certainly look pretty strong.

This graphic shows us that the stock has outperformed the market over the last year (relative strength), is being heavily bought (volume change) and is trading in a strong technical uptrend (price vs…)
However, it’s when we look at NatWest’s earnings estimates that we see the real magic at work.
Just look at how consensus estimates have ramped up since the Bank of England started raising interest rates in January. Earnings forecasts today are 50% higher than they were 12 months ago!

With inflation showing no sign of easing, my guess is that we’ll see further rate rises over the coming months. That could lead to more profit upgrades.
The only risks I can see are the obvious ones.
- At what point will rising rates and the cost-of-living crisis start to affect the ability of NatWest customers to service their debts?
- Will housing prices start to fall, triggering a slowdown in new lending?
The mainstream credit profile of the bank’s lending could mean that its borrowers won’t be affected for a while yet. But with energy prices and mortgage rates set to rise over the coming months, it may not be too long before some homeowners start to struggle.
Conclusions
NatWest’s latest guidance is based on the assumption that the Bank Rate will reach 2% by the end of 2022. As far as I can tell, the bank expects the benefit of higher interest rates to outweigh higher costs from inflation and bad debt.
The board seems confident in this view. They recently surprised investors with a £1.75bn special dividend, in addition to an increased ordinary dividend and share buyback. These returns are intended to reduce NatWest’s CET1 ratio 13-14% in 2023.
My sums suggest NatWest shares offer a dividend yield of 8% this year, possibly more, dependent on the final dividend.
Stripping out the special dividend, I think shareholders can expect a forward yield approaching 5.5%. When paired with improving profitability, rising earnings and a single-digit P/E, I think NatWest shares could be attractive at current levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Hi Roland, the graphic you use within the article showing Momentum, Volume, Price, now shows on the stock report as Volume being in the minus figures and over double negative from what it was on the 9th. ...Is this something that would materially change your reading of Natwest now given volume has radically shifted the other way? I refer to your point about institutional buyers leaving a footprint, and what this maybe reflecting now.
Analysis sounds about right to me but I still have an emotional problem with this company. I remember watching RBS share price drop during the 2008 financial crash. As the price dropped from over £60 to £10 I thought, how much further can it go? So I bought. By the end of the day my £1000 had halved and over the next few weeks halved again. Today £1k punt in 2008 is worth £274. It's such a small amount now, I resolved to hold until I get my money back but now doubt it will ever happen.
Does anyone know if there are any banking ETFs which might allow me to benefit from the trends mentioned in the article without having to attempt to understand an individual bank? (This is not a sector I feel comfortable in understanding).
Looking at Just ETF financial sector there are a number of Europe, World, US bank ETF but can’t see a UK specific one.
The Europe ones seem to have HSBC and Lloyds in top 10 holdings.
https://www.justetf.com/en/fin...
noticed the link isn’t opening the selection just the site. On the left if the page where it says ‘Sector’ change this to ‘Finanacials’
Thanks Roland - great article.
Started thinking along your general lines about a couple of weeks ago - ended up buying a starter stake in £BNC as seemed better value than the British banks and in my experience its a quality operation - and I like a bit of risk re the threatened Spanish windfall tax which has depressed its SP.
However, your article prompted me to look closer at £NWG and I liked what I saw. So I now have a starter stake in that as well.
Time will tell.
Thanks again
Phil
Edit: no idea why the tickers don't work. BNC is Banco Santander and NWG is Nat West.
I wonder what proportion of the Natwest (LON:NWG) mortgage book is on borrower fixed rates and of what average duration? Fixed rates afford some protection to some mortgage borrowers while of course leaving them still to manage other inflationary pressures on their household budget. I'm out of my depth here but would not previously made fixed rate lending of all forms also materially affect (slow) the speed at which the NIM increased to the banks benefit? Although, as Roland highlights, small movements have a marked effect. (I hold).
Roland by coincidence (or karma) I purchased Natwest (LON:NWG) this morning a few hours before I saw your article.
You mentioned the increase in Net Interest Margins as a reason for investment. My view is that these margins still have a long way to go. With the Bank Rate at just 1.75% (a relative historic low) I think more rate rises are required in order for the Bank Rate to effectively contract the economy given the high level of inflation. At this level of inflation my guess is that a neutral Bank Rate would be circa 3% or more and in order to effectively contract the economy it would need to be in the region of 3.5% plus.
I understand that Nat West is more sensitive to the Net Interest Margin than other large British Banks and this is because it doesn't have the exposure to Asset Management and Merchant Banking that the other Banks have.
I take your point about the impact of a possible recession on new mortgages and servicing of existing mortgages but take the view that the returns from existing mortgages and loans should outweigh that problem.
My view is that in these circumstances Banks can serve as a durable inflation hedge; but I would be glad to hear other views.