NEW VERSION - Small Cap Value Report (18 May 2015) - SOM, BLNX, PMR, PLUS

** Apologies, the original version of this report corrupted, so I have reconstituted it from backup**
Good morning! Running late today, as I had to take the car in for repairs & then walk home. Plus I've generally been faffing about on emails & Twitter - two things which I think fully explain the lack of productivity growth in the UK economy in recent years!
A reminder for Mello Beckenham tonight - the new CEO of Crawshaw (LON:CRAW) will be giving a talk, which I'm sure will be very interesting. The shares have roughly ten-bagged (possibly more?!) since Crawshaw last appeared at Mello, so I'm sure the celebratory drinks will be flowing! This stock is expensive currently, but it's a potentially exciting store roll-out - therefore I can see how, in several years time, the growth may well have caught up with & overtaken the current high valuation.
Somero Enterprises Inc (LON:SOM)
Share price: 136p (down 4% today)
No. shares: 56.2m
Market Cap: £76.4m
(at the time of
writing, I have a long position in this company's shares)
AGM trading update - Somero has taken the unusual step of issuing its AGM statement a day early (the AGM is tomorrow - hopefully a friend is going, so he'll be able to let me know what management are like - I haven't met them yet).
It sounds positive,
saying that, "Strong momentum has
continued into 2015 with
solid, broad-based growth across N.America, Europe, M.East, SE Asia, and Latin
America with sales from the majority of our product lines".
Further positive commentary is given. The only fly in the ointment is that China has been sluggish in 2015 to date;
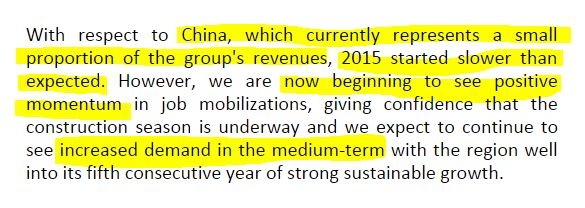
I think it's disingenuous of the company to play down the importance of China, since they did exactly the opposite in their final results, published only six weeks ago - when emphasis was put on growth in China, and what a huge market opportunity this represented.
Furthermore, China was 16% of 2014 revenues, so if
it "currently represents a small proportion of the
group's revenues", then that suggests there's been a big drop in
sales into China.
Outlook - they've clearly made up the China shortfall elsewhere, as the all-important in line with expectations statement is delivered in the final paragraph;
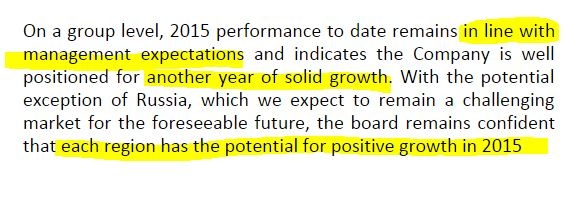
Hmmm, I'm confused now. They're saying that Russia is the only region expected to be challenging, with all other regions having the potential for growth in 2015. So that sounds as if they're expecting sales in China to improve later this year, which is hinted at in the earlier comments, although "medium term" suggested to me beyond this year.
Not the most clearly worded statement, it seems a bit contradictory with respect to sales & outlook in China. Never mind, the key thing is that they're in line with expectations, and the outlook sounds promising.
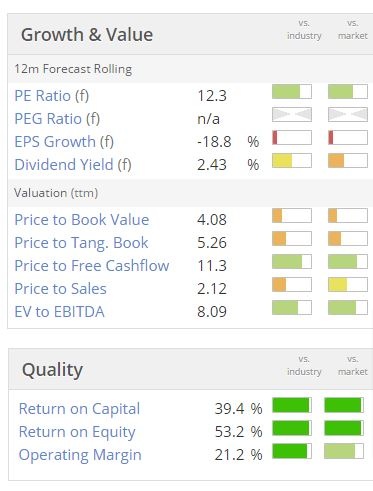 Valuation - this company looks very reasonably priced to me. The
growth has been fantastic in recent years, and I can't see any reason to
suggest that growth is likely to reverse any time soon, quite the opposite
actually - with Western economies now growing again, the cycle should be
strongly in their favour for now.
Note also that all three quality scores are excellent - this company clearly has pricing power, and seems to dominate its sector globally - the company claims 99% market share for laser-guided concrete screeding machines.
My opinion - this is one of my favourite shares at the moment. It seems a reasonably-priced growth company, is soundly financed too, with net cash, and pays divis.
Set against that, as we know, this is a highly cyclical company, making specialised, high value equipment for the construction sector, so when economies go into recession, demand drops off a cliff - as you can see from the Stockopedia graphical history;
Therefore it's definitely not the sort of share I want to be holding when Western economies slam into a major recession. The US market is key for Somero, and the comments today are positive about that. Therefore, considering the modest valuation, I think it looks a very appealing share, with the caveat that the downbeat comments about China are somewhat disappointing. I don't think that undermines the current valuation, but it perhaps chips away at the big upside that was looking possible six weeks ago.
Blinkx (LON:BLNX)
Share price: 35p (down
10% today)
No. shares: 402.3m
Market Cap: £140.8m
Final results - for the year ended 31 Mar 2015 are out, for this company, which seems to mainly operate in the USA, doing internet video search & related advertising, if that's an adequate description?
At the risk of sending ShareSoc's Roger Lawson into another apoplectic rage, I am going to comment on the results. The company has had well known problems, and it stated on 8 Apr 2015 that it was in line with (downwardly revised) expectations, telling us to expect the following key figures;
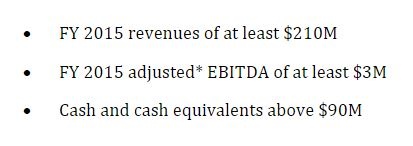
As myself & other commentators pointed out at the time, due to the way the company capitalises a lot of its costs, the EBITDA figure is meaningless. It would actually report a hefty loss overall, if it generated EBITDA of $3m.
Adjusted EBITDA has actually come in slightly ahead, at $3.5m, revenue is ahead, at $215.0m, and cash is ahead at $95.7m. So it's been nicely set up to make it appear that the company has done better than expected, but this is all nonsense really.
If you look at a proper profit figure, it's actually gone from a $17.6m profit before tax last year, to a $24.8m loss this year. So a disastrous performance, and no amount of spin in the commentary can disguise reality, despite them trying very hard.
However, the $24.8m loss does include amortisation charges of $12.4m relating to previously capitalised costs (R&D, S&M, and admin), and $4.7m in acquisition & exceptional costs. Therefore a case could be argued for focusing on the $7.8m loss which the company highlights with a box around it, on the P&L, as being a reasonable measure of performance. Bad, but not dire, might be the best description, if you are happy to focus on this particular performance measure.
Cashflow statement - this is usually of far more use than the P&L with software companies, to understand the true nature of the business's performance, in cash terms. I note from the cashflow statement that operating cashflow after tax was -$3.0m, which is hardly a disaster, although it compares extremely unfavourably with a $39.2m positive in the prior year.
The cash burn of $30.9m in the year was mainly spent on acquisitions, at $21.7m. So it looks as if the company is trying to buy in growth, given that the existing business is now struggling.
Outlook - reading the narrative, I don't think the company has really given a credible explanation for why the profitability of business model has basically collapsed. They refer to structural changes in the industry, and that Blinkx has "deliberately realigned the business to focus on Mobile, Video and Programmatic advertising channels..."
It strikes me that the original business model, whatever it was (and there are differing views on that !), doesn't work any more, so they're trying other things, and making acquisitions, using the cash pile.
This paragraph is quite revealing;
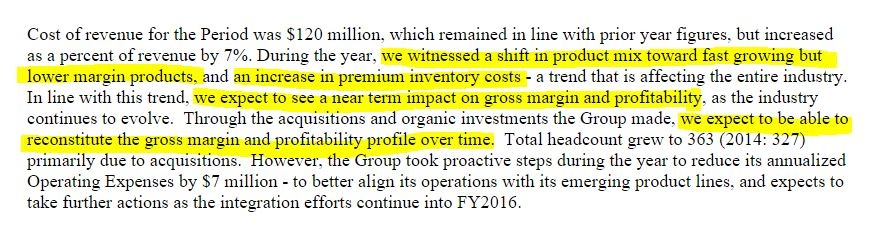
In a nutshell then, the company is currently loss-making, but hopes to be able to improve things in future.
Outlook - this sounds pretty grim to me, but they're doing their best to polish the proverbial ...
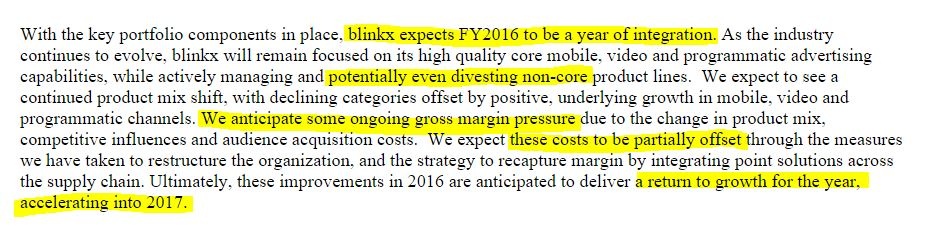
My opinion - for whatever reason, Blinkx's original profitable services are not profitable any more, so they're moving on to different, lower margin services.
So how on earth can the company be valued? It's loss-making now, therefore we can't use a PER, and forward estimates of profit are surely little more than guesses at this stage?
On the other hand, it has a strong balance sheet, with net cash of $95.7m, about £61.0m. Although cash is reducing quite rapidly, partly from trading losses & capex, but mainly from acquisitions.
Overall I just think it's impossible to value. If you think they can pull something out of the hat, and become profitable again, then that's the only reason I can see for wanting to hold shares in a loss-making group which has a bit of a whiff about it. It doesn't interest me, as I can't see where the profits are going to come from, and today's statement doesn't give a lot of clues either.
Panmure Gordon & Co (LON:PMR)
Share price: 129.5p
No. shares: 15.5m
Market Cap: £20.1m
(at the time of writing, I hold a long position in this share)
AGM Statement - this sounds generally upbeat, but is light on specifics. Key points;
- "Robust performance" in 2014
- Dividend payments are to re-start after 7 years' absence
- Stockbroking commission rates remain under pressure
- Corporate finance activity key to profitability
- Healthy pipeline of transactions
- Acquisition of Charles Stanley Securities should be completed by end May 2015
My opinion - this sounds alright to me. It will be good to start receiving divis.
Plus500 (LON:PLUS)
Share price: 524p at 15:18 (down 30% today)
No. shares: 114.9m
Market Cap: £602.1m
Breaking news - FT Alphaville have run a story today saying that Plus500 has suspended some UK accounts pending customer verification measures related to money laundering regulations.
Customer accounts are being frozen, with them unable to with draw funds, until proof of ID & address documentation is supplied.
My opinion - I've never liked this share - the figures looked too good to be true, or at least too good to be sustainable. It looks as if the company might have been playing fast & loose with the regulations. If you're an optimist, then you might see this as a buying opportunity, as business may return to normal once customers have sent in the required documentation.
On the other hand, if this closes the door to easy acquisition of mug punters, to lose money on their trading platform, then it could mean a permanent & serious drop in profits. Who knows?
No doubt the company will imminently issue a reassuring statement saying that everything is fine, and it will be business as usual very soon, and that might trigger a bounce in the shares.
Personally I try to avoid all overseas companies listed on AIM, as there's usually something wrong with them. I also avoid catching a falling knife where there is some serious problem with the business model, which I think there might be here.
Who knows what will happen next, but personally it looks to me like the company is in chaos, and hence it's not a share I would want to be holding.
Company announcement - this has just been issued. Key points;
- Confirms that final & special divis have been paid, contrary to rumours
- PLUS has $88m in cash reserves (in addition to client funds)
- Clients affected by new documentation checks - 50% (UK) * 55% affected = 27.5% of all customers
Will be interesting to see how this pans out! I'm wondering whether having to provide proper ID when opening accounts might reduce business somewhat, but is it going to destroy the business completely? I very much doubt it.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
TMFMayn: I'll consider whether it's possible to do that.
Paul
Thanks for you report on Somero Enterprises Inc (LON:SOM). However, I cannot share your enthusiasm when the figures that they have put out on 07/04/2015, (and are still showing on their clunky website) in their annual report showing EPS progression as follows:
2012A 2013A 2014E 2015E 2016E 2017E 2018E 2019E
EPS (c) (basic) 1.77 9.75 25.76 16.45 17.63 20.13 22.72 24.9
EPS (p) Adj dil 3.76 8.07 12.17 11.38 12.18 13.62 15.10 16.81
If I have made a mistake here then please could you put me right? But to me the above figures do not look at all like an attractive investment.
Roger, I'm afraid you're completely wrong on Blinkx. They are neither a software company nor an early stage company (in the sense of valuation approaches that you allude to). They are a market platform for video advertising and are a complete disaster.
I bought a year ago following the Ben Adelman report, feeling that his comments were exaggerated (and could typically be applied to any media advertising). and the share price fall overdone. Since then turnover from legacy business is down about 40%, margins are down and under pressure as they seem to lose contract revenue for more competitive bid ('programmatic') revenue.
This has been one of my worst investments ever. Pauls analysis is spot on, probably generous. If you can find anything positive in their results or presentation I would be very pleased to hear it!
Grindertrader: regret I do not have the time to provide an education on that subject - but there are plenty of articles on the internet about valuing technology companies and early stage companies (and before anyone says Blinkx has been around for years, the product offerings and the market in which it operates have been so rapidly changing that it's a fairly new business in many ways).
Hi roger,
Perhaps you could devote part of the next sharesoc newsletter to educating us on valuing GBO and BLNX etc - it would make a bit of a change to reporting on those VCTs.
Mayn
Paul, thanks for the invite to value Blinkx, but I'll decline. That would really be a hostage to fortune. I am not in the business of giving public prognostications like you are.
I think it is a shame to publicly state that software companies can be valued by other means than for instance profit figures, but yet refuse to share your opinion what that may be.
The Stockopedia discussion boards are wonderful for sharing ideas and to enhance the knoweldge of all without the possibility of ridicule often seen in other forums.
I agree Grindertrader. It is refreshing to have a forum for coherent adult discussion. It does seem that some people make a real emotional attachment to their stocks. A shame, and I guess why discussions of shorts on stocks which you hold a position in have had to be banned on this forum.
Hi Paul, wrt SOM how do you reconcile your positive comments on continued future growth with the -18.8% EPS growth in the accompanying table?
Cheers
Hi Sutters,
"wrt SOM how do you reconcile your positive comments on continued future growth with the -18.8% EPS growth in the accompanying table?"
Somero had a large tax credit in 2014, so the 2014 EPS figure is artificially high.
I explained this in my SCVR of 7 Apr 2015 - scroll down to the subsection "Taxation" in the £SOM section.
Also, there is a new commissioned research note out today here, which gives more flavour to how the business is performing.
Regards, Paul.
Thanks Paul (and Deucetoace), I hadn't spotted the tax credit.
Regards
SOM in the year just gone had a large exceptional tax credit. I imagine that is why it shows a notional fall in EPS.
Wow, I have been kicking myself for a while for selling Plus500 (LON:PLUS), but today I am quite happy.
When you watch a share going up and up, it does make you question whether you were wise to sell.
My concerns were always around their account practices, there were rumblings that they were refusing to pay out on some accounts. My feeling was that they were exploiting the losers and cutting off anyone that "won".
Re Blinkx, it is of course possible to value a software company on other things than profits. I know because I sold one that did not have any and then retired on the proceeds twenty years ago. But one thing I did learn from my time in the software business: never use an accountant to value a software business because they are usually looking at the wrong metrics.
As regards Plus 500, I agree with Ed having once held the stock. Just read the AIM prospectus if you really want to get informed. Look at customer churn. And "breakage" of dormant accounts (or where folks don't provide identity info upon request) is another thing to look at. Incidentally ShareSoc did publish an AIM "Scorecard" a couple of years ago to enable you to weed out the duff companies. It's on our web site. It might take a bit of time to go through it, but it weeds out the questionable companies quite well.
Roger,
I'm fully aware that businesses can be valued on things other than profit, but thank you for pointing it out anyway.
So how are you valuing Blinkx (LON:BLNX) currently then? Please do enlighten us!
To my mind, its legacy business seems to have gone badly wrong, and they warn of more margin pressure. So they can either cut costs, or exit problem areas - both of which are hinted at today.
With a complete lack of visibility, personally I wouldn't value Blinkx at anything above its current net cash. Or you could do a sum of the parts valuation on the bits which might have good future potential perhaps?
Blinkx isn't really a software business anyway. It's an advertising company.
Re AIM Prospectuses - very good point. Hardly anyone bothers reading them, but there are often considerable warning signs buried in the detail.
Re ShareSoc's AIM scorecard - yup, it was pretty good, I used it a few times when researching companies.
Paul.
Plus500 (LON:PLUS) I wouldn't be buying.
Just my impression, of the FCA and other govt authorities is that if they suspect you are helping money launderers, then, rather than a raised eye brow, they will nail a certain part of your anatomy to the office floor.
Just my impression, of the FCA and other govt authorities is that if they suspect you are helping money launderers, then, rather than a raised eye brow, they will nail a certain part of your anatomy to the office floor.
I don't think that Plus500 (LON:PLUS) have fallen purely on the risk that they will get a fine from the FCA for not being tight enough on the Money Laundering Reg's. It is the risk that they have implemented this policy themselves to make it intentionally much harder for customers to remove their money than deposit money with them and the implication of the type of business they are if they would do this. Having had no direct experience of the business I have no idea if this is the case or not but the impression of risk is probably not helped by the FT blog questioning the sustainability of their margins etc.
A couple of weeks ago I had the idea of joining Plus500 (LON:PLUS) depositing a small amount to get any introductory bonus and seeing how easy it would be to trade that through and withdraw, purely to see how easy it was - the idea being that you could earn more by learning the real business model of Plus500 (LON:PLUS) and trading that than you could lose on their platform. Never really got round to it though and obviously it's too late now.
Given how easy it would have been to do for anyone financially experienced enough to be taking a position in the Plus500 (LON:PLUS) equity to do likewise to check them out I'm surprised there aren't more people with direct experience reporting back on here.
Francis Bacon on PLUS 500, Globo, RCG et al... 1432.
PLUS 500 In September 2014 anybody could pick these up at under £4 per share (I did). With the progress made by the company since then, today looks like another opportunity for the brave and possibly foolish. I fear that the FCA will go totally over the top (it usually does - while turning a blind eye to real market abuse).
However, any business that throws cash dividends at its shareholders like this one, must be doing a few things right.
Too late to sell so have bought a few more.
Disclosure: Long PLUS 500.
Bonitabeach
plus has just crashed again to 437, think i will give this a miss.
Any views on why Pressure Technologies (LON:PRES) are up so much today Paul?
Re. PLUS. As mentioned at the Peterborough ShareSoc masterclass, I sold my holding in PLUS, against my own rules & the StockRanks, due to a bad feeling about it.
Maybe I got lucky today, but like Paul I've learnt not to trust foreign listed AIM stocks. I got badly burned in some Chinese AIM Shares back in 2008 ... once bitten twice shy as they say.
So - is today's fall a buying opportunity or is everyone still steering well clear?
Plus sp has just fallen again to 470p, maybe one to watch.
Hi Ed,
Is it worth tweaking the StockRanks so that they exclude all overseas AIM stocks? Since there is such a high incidence of them going badly wrong? Or maybe run both systems side by side, and see which out-performs!
Regards, Paul.
Possibly. We don't have the data though. It would have to be a manual exclusion process and require judgement. There's a lot of companies that are foreign domiciled.
What about bootstrapping it with some heuristics on HQ address etc, and crowd source corrections?
Hi Ed
Your comment about the Plus stock rank being a "false positive" struck a chord with me a while back and with all the noise on the bulletin boards (advfn) decided to sell a few weeks ago. I was intrigued by your comment and from your narrative above gather your comment was borne out of a gut feeling rather than anything concrete. The old saying "if it seems to be good to be true...." I suppose. BTW I did the same with Globo!
Have found the Stockopedia site a revelation and thought provoking education for my stockpicking.
Thanks.
Sigh. Decisions, decisions. I had long been calling Plus500 (LON:PLUS) uninvestable. Still, we are talking about a 40% drop on what seems to be no real news at all. As we've seen with Quindell (LON:QPP), even garbage can make you money at the right price.
My feeling is that Plus500 (LON:PLUS) still has a "viable story" attached to it (for now, at any rate); unlike Spaceandpeople (LON:SAL), say, where the perception went from a growth stock to value stock. I'm not sure where the local bottom is - it is probably sometime this week. The bottom may already be in.
I think that that the odds favour a technical bounce. I think the trick is to let it fall, and buy when it looks like it is making a recovery. I may be tempted for a SMALL punt.
No holding.
Ed,
If you do not have the data regarding foreign status of stocks, could you add an upvote/downvote counter to each stock? I'm sure using the power of the crowd we could very quickly end up with a list which would enable us to screen for UK stocks only. It would only be a guide, but it would save a lot of time repeatedly looking at dross.
Don’t forget the fraudulent activities Blinkx continues to carry out – as proven by Ben Edelman
Somero is an American company?
herbie47,
Yes Somero Enterprises Inc (LON:SOM) is an American company, which listed in the UK in 2006. I have queried why it listed in the UK, and it's because the previous owner, PE or VC, wanted to maximise the valuation (as anyone would), and at the time, AIM was more receptive to this type of company than the US market.
The UK listing has worked well, so they are happy to remain listed in the UK.
Regards, Paul.
I see, I only asked because HL say I have to complete a USA 'W-8BEN' form in order to buy, if they are listed on the Aim this should not apply?
Place of incorporation rather than place of listing is what's likely to matter here.
Hi Paul,
I love reading your report and value your opinion, so please don't think I'm being picky, but just trying to understand how your comment on PLUS500 - "Personally I try to avoid all overseas companies listed on AIM, as there's usually something wrong with them." relates to your holding in Somero, which you agree is an American company?
Thanks.
Hi joe91,
You're right, it's an inconsistency. After doing my research on Somero Enterprises Inc (LON:SOM) I'm happy to invest in it, because I don't see any funnies in the accounts, I understand its business model, which seems sustainable, it pays divis, and has a track record of about 9 years as a UK listed company.
So I wouldn't completely rule out investing in overseas companies on AIM, but the bar is set very high indeed before I'm comfortable investing in one.
As I've consistently said in my reports here, I always felt there was something not quite right with Plus500 (LON:PLUS). The accounts looked unfeasibly good, but they're paying fabulous divis, so that led me to believe that their accounts were probably true, but the profits were maybe not sustainable - as it looks like they were bending the rules on money laundering rules, and sooner or later they will run out of mug punters to exploit. There again, bookies are still going, and they exploit mug punters too, so who knows?
Regards, Paul.
Re Blinkx (LON:BLNX): "It strikes me that the original business model, whatever it was (and there are differing views on that !), doesn't work any more, so they're trying other things, and making acquisitions, using the cash pile. "
That's my suspicion, too. It seems to be a problem with a lot of AIM companies (Globo (LON:GBO) springs to mind, although I haven't looked at it for a long time). The business, for whatever reason, is not really viable long-term, so they have to make acquisitions to make up for the parts that are dying.
The company raises cash to buy the businesses. Unless the managers are genii, which they're not, all the money is poured into what basically amounts to a fool's errand.
Despite all the hype of being the next Youtube, Google, Facebook or whatever, investors stand very little chance of making money out of this in the long term.