New Year Naps - Top Stocks for 2025 with a segue to the QVM Portfolio

Happy New Year to all subscribers! While Santa has not brought his usual rally to UK markets over recent weeks, I do find myself optimistic for 2025. Everyone is miserable about the prospects for the UK economy, but all the doom and gloom seems priced in. The UK is cheap, and the smart money has been picking up bargains with one in twenty UK stocks receiving takeover bids through the year, and international investors circling. Good quality, value stocks have been appreciating and, aside from the dismal AIM, all the major FTSE indices rose in 2024. The NAPS Portfolio ended 2024 up almost 20% over the year, significantly beating its benchmark, the FTSE All Share, which managed 6%.
We’ve now completed a full decade of the NAPS Portfolio. It’s been a wonderful journey of rather lazy, but extremely effective investing. Ten years of applying this disciplined investment process have generated 13% annualised returns, beating even the S&P 500 by only investing in UK stocks. I wrote an extensive review with lots of data visualisation from this decade of outstanding returns, which you can catch up on here.

Looking to the QVM Portfolio of the future
I’d mentioned that we might stop the NAPS Portfolio, as we are aiming to develop a more complete suite of model portfolios for subscribers. Many of you were rather dismayed, and encouraged me to continue and publish another portfolio for 2025. Your wish is my command, but let’s just say that this is under review.
We’ve learnt so much over the last ten years. Our data research projects have validated many core ideas in stock market investing, and a continued reading of third-party research has even more so. Just to illustrate the point, we know that we should sell immediately on a profit warning, that there are certain traits of stocks that make them more likely to be multibaggers, and that stocks ahead of expectations are more likely to continue in the same direction. These are all ideas I use in my own personal investing.
Should we be satisfied with the NAPS Portfolio results, when the rules are only applied once annually at a rebalance date? Can’t we develop and apply a more disciplined rule-set that can enhance returns and lower drawdowns, by consistent management on a month-to-month and week-to-week basis?
It will be interesting to see if we can. Ultimately, the NAPS Portfolio sets an annual benchmark. It’s a solid, dependable, cost and time-effective way to run a high StockRank portfolio. James Montier once said in a paper titled “An Ode to Quant” that models set a ceiling from which we detract performance, rather than a floor to which we add. So we may find that we can’t beat the NAPS, but that shouldn’t stop us trying.
The 2025 NAPS Portfolio is likely to seed a new model portfolio with a working title of “The QVM Portfolio”. The rules will be developed over the coming months. So watch this space.
Synthesising the “perfect stock” with the 2025 NAPS
This year’s NAPS portfolio is based on similar rules to last year, marginally adapted from the original. There are no frills here, and a more dynamic approach may perform better - so riff as you wish if you are using these as a basis for your own rules. These rules are not meant to be prescriptive. Many try sorting on different ratios, with different numbers of stocks, different markets, different cutoffs, and different filters - there are a few ideas in the “StockRank Strategies for Systematic Investors” chapter of my ebook “Investing with the StockRanks” which is well worth a read.
This year’s rules are:
- Sort by StockRank descending.
- 20 stock portfolio.
- 2 from each sector, but just one from Telecoms and Utilities.
- Top up with the next highest-ranked stock from 2 of the other 8 sectors.
- Minimum market cap of £20m, and max bid-ask spread of 7.5% (750 basis points).
- No investment trusts or funds.
The bid-ask spread is the difference between the sell price and buy price for each stock - and is the biggest cost of trading. 7.5% appears way too high, but in reality I’ve set this cut-off to keep the average spread of the positions reasonable (at 1.3% ). This cuts out one or two high ranked stocks that are hard to trade, but does still let in a couple above a 5% spread. Just beware that if you have a large portfolio size, it can be hard to trade illiquid stocks.
The average StockRank of the resulting portfolio is 97, with high Quality, Value and Momentum across the board, as you’d imagine given the rules. I like to think of the NAPS as a high quality, “Value and Momentum” portfolio.
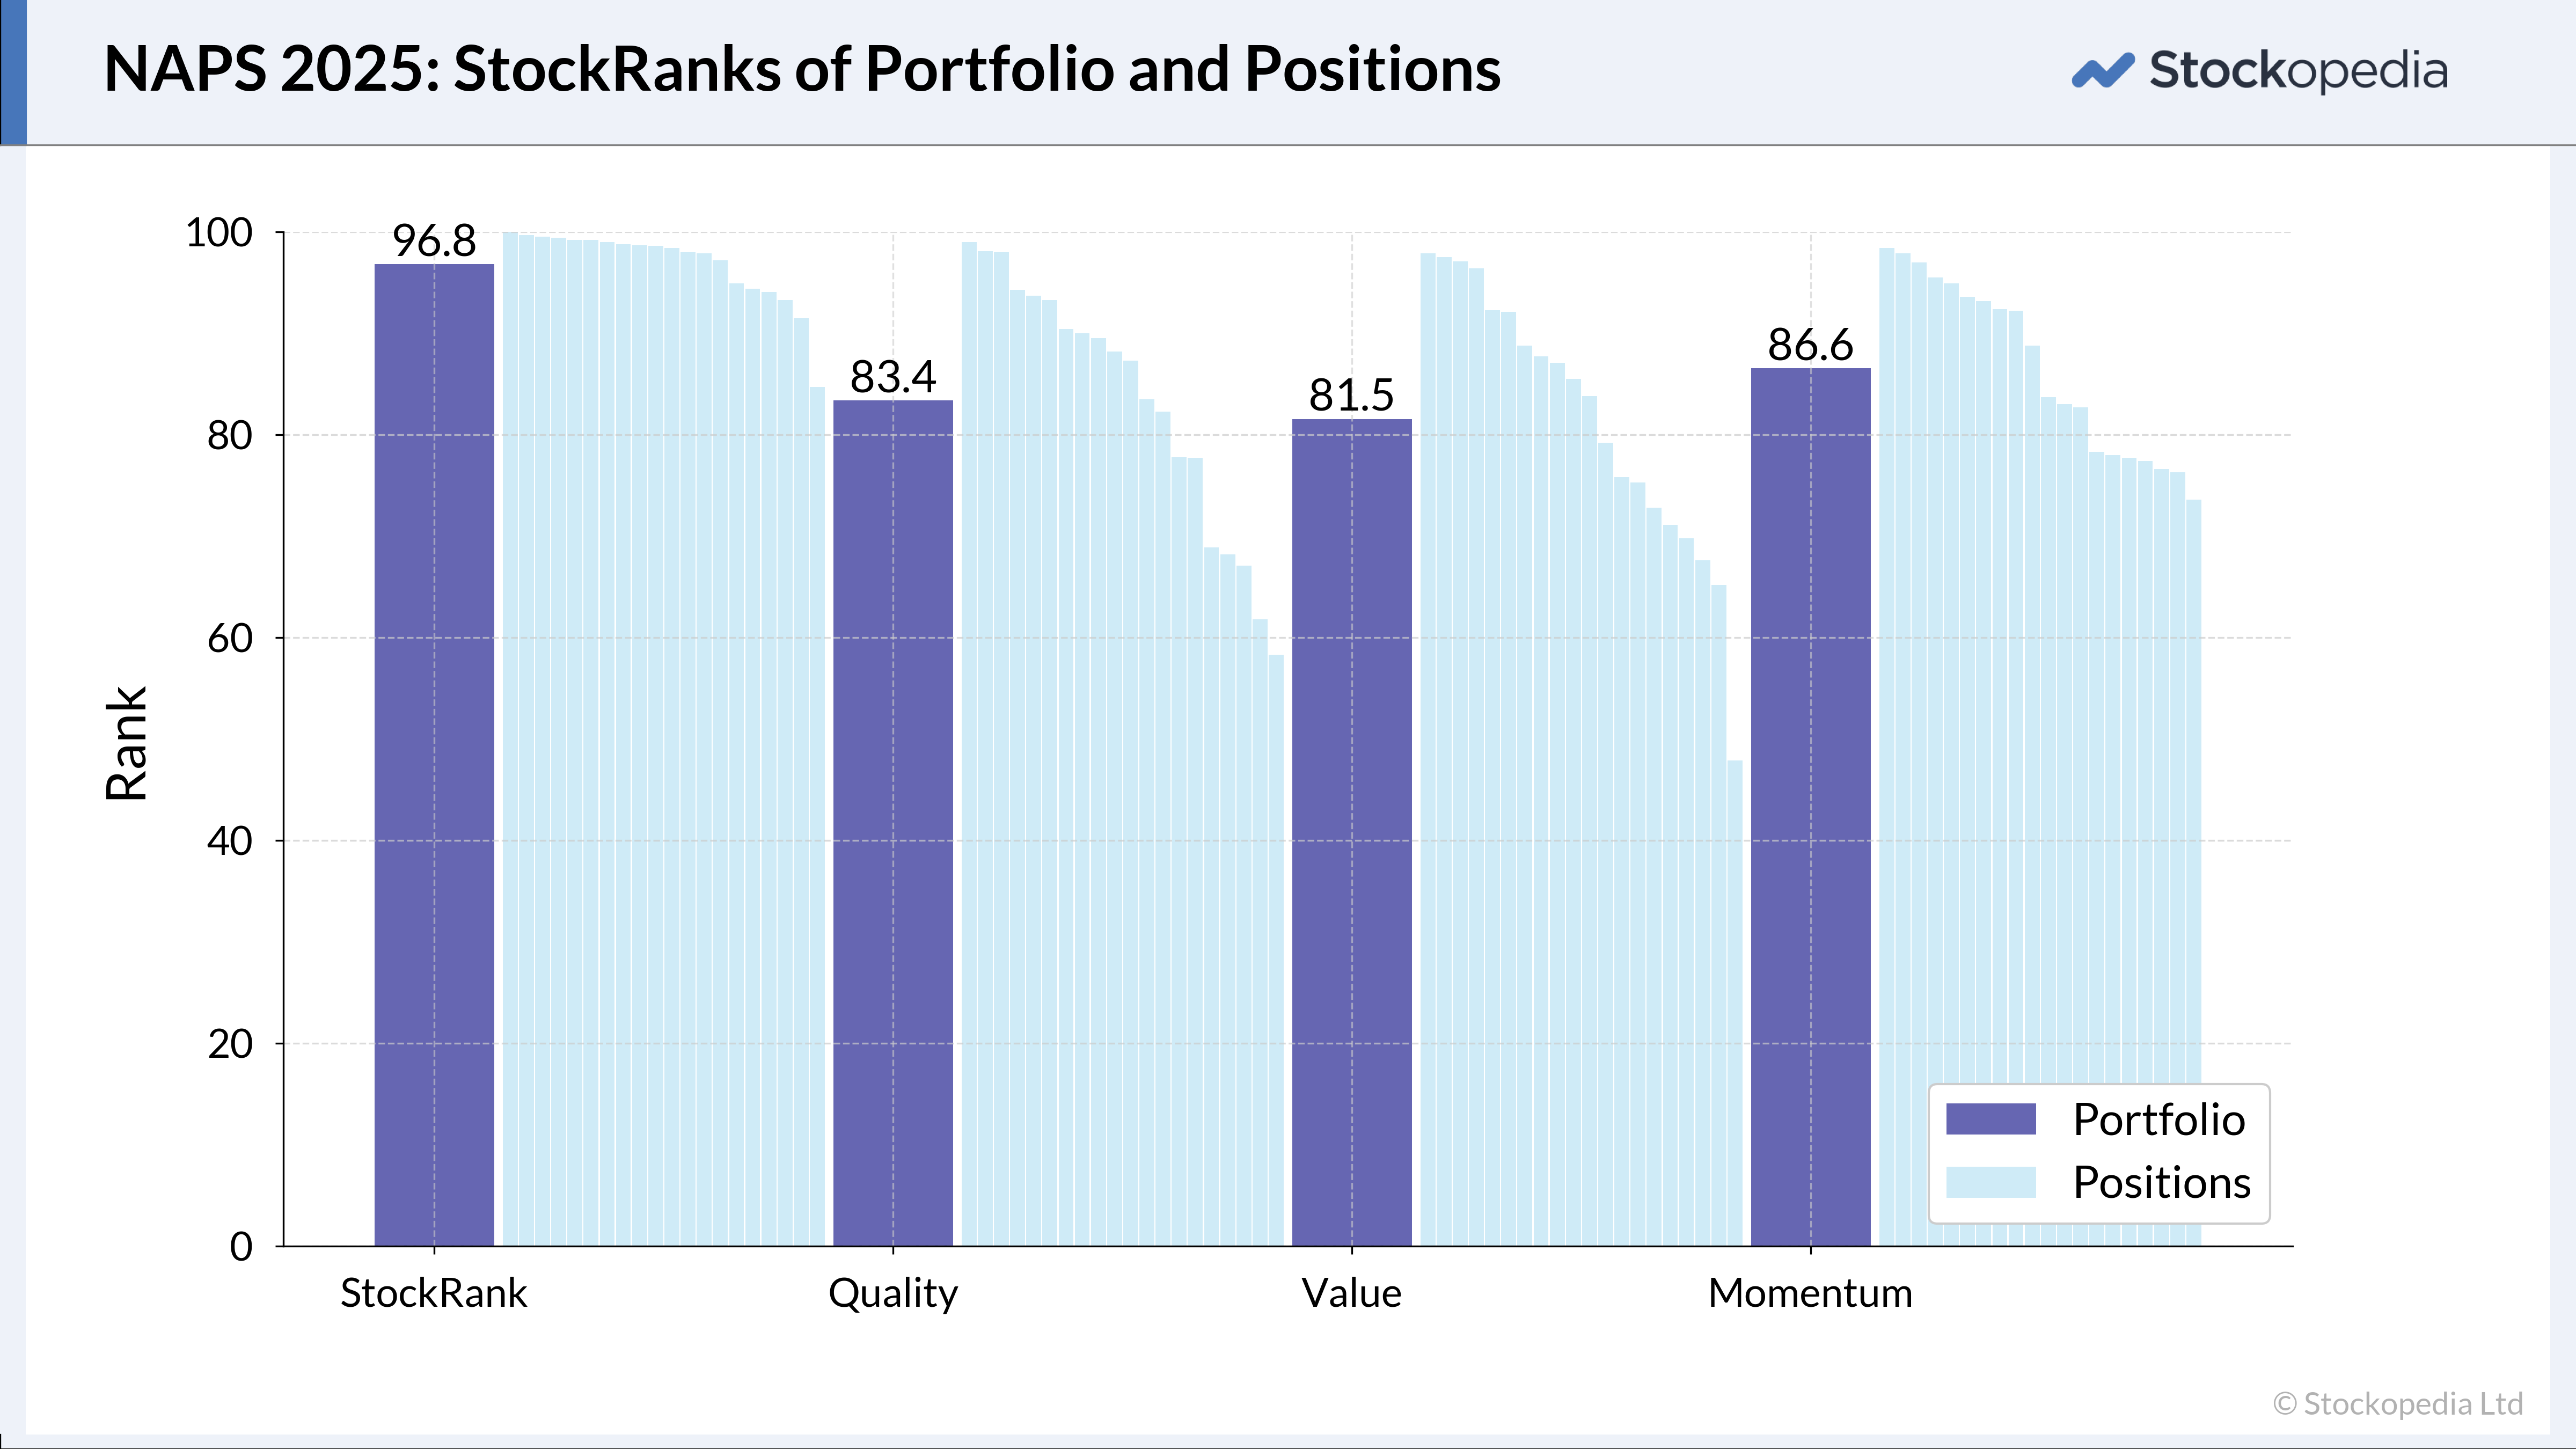
The underlying portfolio statistics are really remarkable. On average, each stock has grown earnings by 42%, has a P/E ratio of 8.7, a return on capital of 16%, margins of 14%, has beaten the market by 19% over 12 months and yields 4% in dividends. If I could offer you an individual stock with all these traits you might bite my hand off, but I’ve tried screening for it and it doesn’t exist - have a look here. You can’t find the perfect stock, but you seem to be able to synthesise its characteristics as a portfolio. I’ve written before about this portfolio construction alchemy - and it still amazes me today.
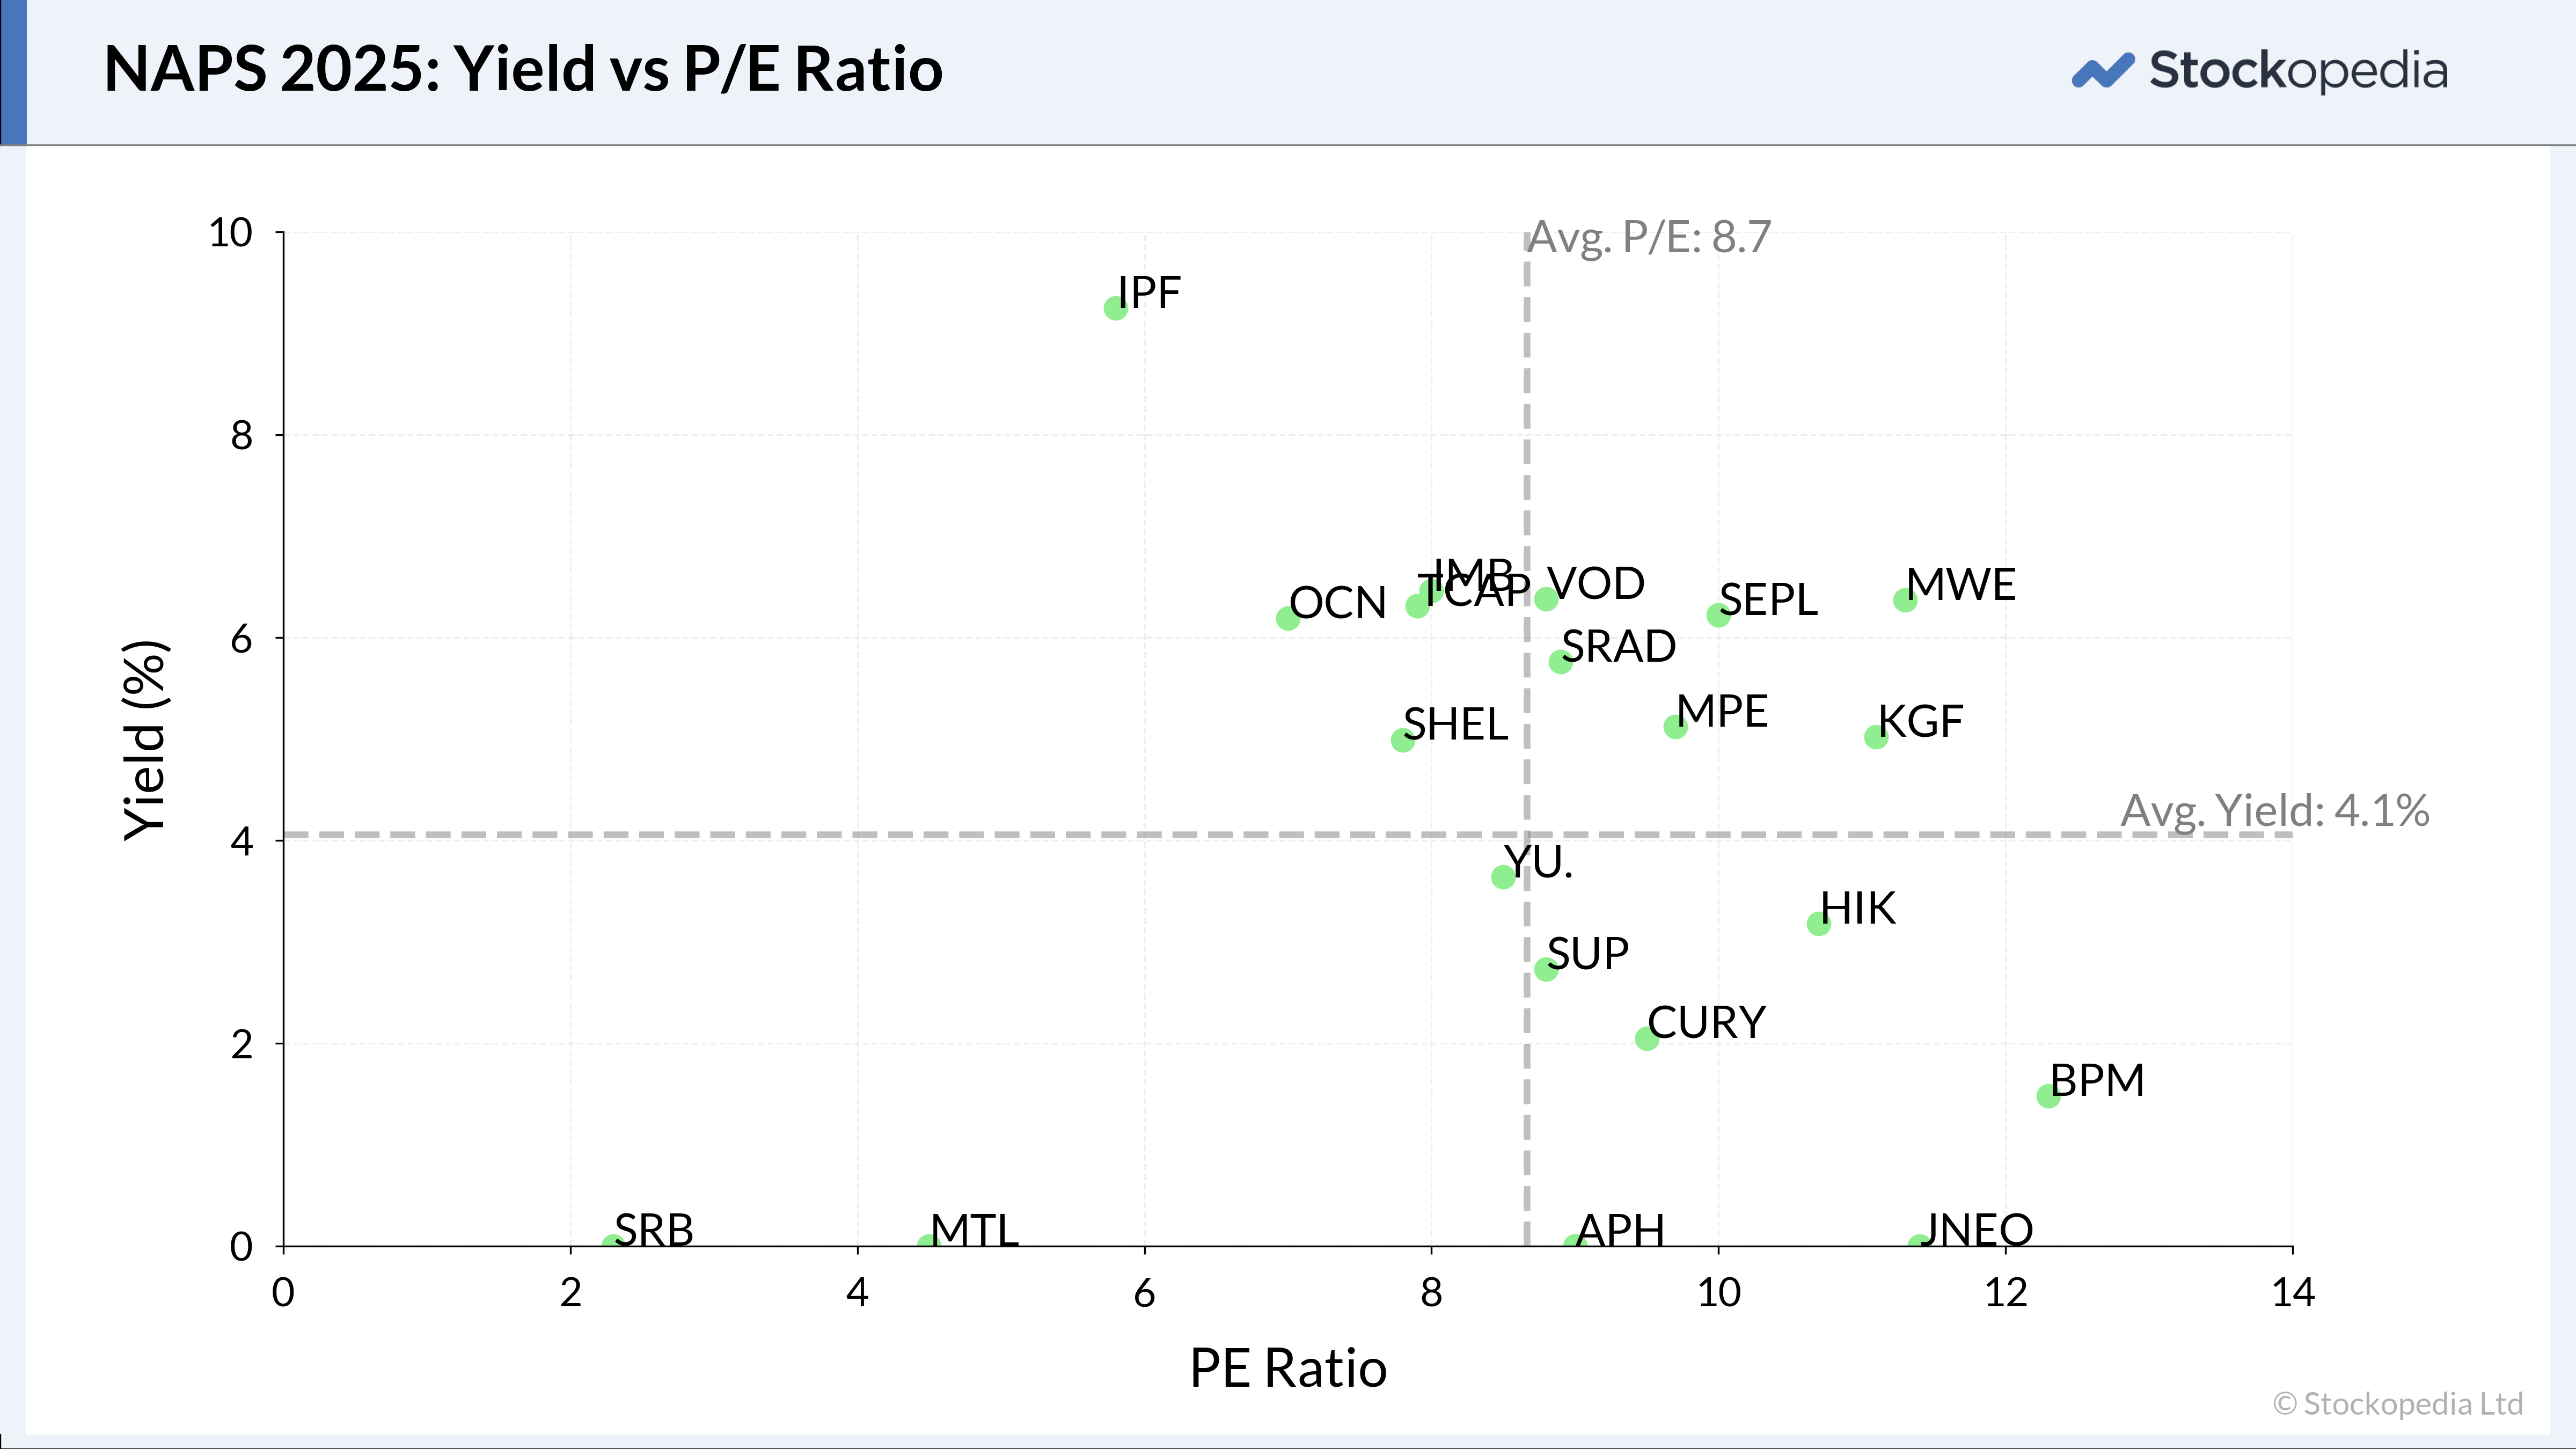
The portfolio would have to rise by 40% to reach the average valuation of stocks in the UK market (from a P/E of 8.7 to a P/E of 12.2). We just have to have faith that the invisible hand of Mr Market will do its work. Over the years, he’s always seemed to.
The Stocks
I’ve been generating this portfolio on numerous occasions over the last week, and some stocks do slip in and out depending on the daily process. If you are interested, the stocks that just missed the cut on today’s numbers include: PayPoint (LON:PAY) , Altyngold (LON:ALTN) and Enwell Energy (LON:ENW) , and for all I know one of those might be a massive winner in 2025. So DYOR!
Ticker |
Mkt Cap (m GBP) |
Stock Rank™ |
Sector |
Metals Exploration (LON:MTL) |
92 |
98 |
Basic Materials |
Serabi Gold (LON:SRB) |
82 |
100 |
Basic Materials |
Currys (LON:CURY) |
1076 |
98 |
Consumer Cyclicals |
Kingfisher (LON:KGF) |
4508 |
98 |
Consumer Cyclicals |
M P Evans (LON:MPE) |
519 |
99 |
Consumer Defensives |
Imperial Brands (LON:IMB) |
21373 |
99 |
Consumer Defensives |
Seplat Energy (LON:SEPL) |
1147 |
97 |
Energy |
Shell (LON:SHEL) |
151429 |
94 |
Energy |
International Personal Finance (LON:IPF) |
283 |
99 |
Financials |
B.P. Marsh & Partners (LON:BPM) |
269 |
99 |
Financials |
TP Icap (LON:TCAP) |
1953 |
99 |
Financials |
Hikma Pharmaceuticals (LON:HIK) |
4406 |
93 |
Healthcare |
Alliance Pharma (LON:APH) |
247 |
84 |
Healthcare |
Supreme (LON:SUP) |
204 |
99 |
Industrials |
Ocean Wilsons Holdings (LON:OCN) |
460 |
98 |
Industrials |
Stelrad (LON:SRAD) |
173 |
98 |
Industrials |
Journeo (LON:JNEO) |
47 |
93 |
Technology |
MTI Wireless Edge (LON:MWE) |
37 |
91 |
Technology |
Vodafone (LON:VOD) |
17429 |
96 |
Telecoms |
Yu (LON:YU.) . |
304 |
97 |
Utilities |
I’m biased to a few stocks of course, as I love a good story too, so I’m glad to see the portfolio include Yu Group, Journeo and the Gold miners. Nonetheless, I’m not expecting fireworks from this portfolio, though I rarely do. It’s full of buy-backy, dividend payers, rather than growth stock stars.
There are a few sin stocks in here that ESG investors may wish to avoid, but the beauty of the NAPS is there’s nothing stopping you from adding a moral overlay. It’s just another rule. Maybe the oil sector is doomed, and will always trade on low valuations, and the two businesses exposed to smoking products - Imperial Brands and Supreme - may not be for everyone.
I’ve done my best to provide a brief note on all the businesses below, but I don’t pretend to be an expert on any of them. It would be great if the community can fill in the gaps. If I’ve made any errors, please do correct me and I’ll edit in improvements!
Basic Materials
Two gold miners, illustrating the strength in the gold price and the great profits being generated.
Metals Exploration (LON:MTL)
StockRank: 99, Market Cap: £92m, P/E: 4.4x, Yield: 0%
Metals Exploration mines gold in the Phillipines from its Runruno mine. It was an absolute star in the 2024 NAPS rocketing 104% through the year, and returns again for 2025. The company has been spitting off cashflow with the rising gold price, recently becoming debt-free, and buying in the rest of the Runruno mine. It’s also been expanding its portfolio acquiring YMC which has further exploration licences. In early December they announced a takeover bid for Condor Gold which has been recommended by Condor’s board.
Serabi Gold (LON:SRB)
StockRank: 100, Market Cap: £85m, P/E: 2.4x, Yield: 0%
Serabi Gold is a Brazilian-focused gold miner, which had an even stronger run in 2024 than Metals Exploration. In its 9 months results to September 2024 it reported revenues up 47% year on year and an 280% improvement in post-tax profits. These are the kinds of growth numbers we’re getting used to in the gold sector, but still these businesses languish on extremely low P/E ratios. Cash stayed level year on year at $11.5m, which reflects the ongoing investment Serabi is making in the development and ramp up of the mines and plants at its Coringa and Palito mines. Serabi is also one of our 12 stocks for Christmas 2024, and you can read up Mark's review here.
Consumer Cyclical
A couple of big retailers, which worries me given the doom loop of Rachel Reeve’s national insurance hits. Or does that create the opportunity?
Currys (LON:CURY)
StockRank: 99, Market Cap: £1056m, P/E: 9.4x, Yield: 1.88%
We all know Currys well as a mature, ominchannel retailer of tech products, operating online and through 719 stores across the UK, Ireland and Nordics. It disposed of its Greek business earlier in 2024 to concentrate on these larger markets. It reported “strengthening performance” in its half year results in December, and still believes it will hit its profit targets despite the national insurance rises. Graham reported on the latest results in the Daily Stock Market Report here, with an Amber/Green rating. Dividends look to be coming back in 2025 and the market may be warming to the business again.
Kingfisher (LON:KGF)
StockRank: 98, Market Cap: £4484m, P/E: 11.2x, Yield: 4.99%
Kingfisher has over 2,000 stores across Europe, and you may know it best through its ownership of B&Q and Screwfix. Kingfisher does talk a good game of £120m cost reductions and a restructuring of its French operations to support future growth, but this is another retailer hit by the UK national insurance rises and increasing wage costs. Nonetheless, the company has strong cash generation, a solid dividend yield of almost 5% and a £300m buyback program. Roland wrote up the recent November results in the Daily Stock Market Report here with an Amber/Green rating. He noted that owning shares in Kingfisher might be better suited for cyclical trading rather than long-term holding. Well that’s what the NAPS does well.
Consumer Non-Cyclical
Palm oil and nicotine products may not be for everyone of course.
M P Evans (LON:MPE)
StockRank: 100, Market Cap: £501m, P/E: 9.4x, Yield: 5.28%
MP Evans produces palm oil in Indonesia with estates in Sumatra and Kalimantan. In the first half of 2024 they reported revenues up 22% and an 81% increase in earnings per share driven by higher production volumes and palm oil prices and lower costs. Strategic expansions have added over 10,000 hectares to its plantations as it continues its growth strategy. Palm oil has its detractors, so MPE does publicly commit to sustainability, mill certifications and so on. Overall, the company is performing well and has more than quintupled its dividend since 2015. At interims it further boosted dividends by 20%. Graham last rated it as Amber/Green at the June trading statement, and there's an extensive write up by a subscriber, Mahad, here.
Imperial Brands (LON:IMB)
StockRank: 100, Market Cap: £21477m, P/E: 8x, Yield: 6.43%
Imperial Brands, formerly Imperial Tobacco, grew operating profits by 4.6% in 2024 ahead of forecasts, with strong 26% revenue growth and reduced losses in its new lines of nicotine products (vapes and nicotine pouches). Traditional tobacco products do seem in decline, and regulatory pressures continue, but the growth in vaping and alternatives is plain to see and the business is adapting. The company continues to grow dividends (up 4.5% this year) and announced a £1.25 billion share buyback for 2025 (+14% on 2024). Apparently the business is unveiling a new 5 year strategy in a March Capital Markets day - so that’s well worth watching out for.
Energy
A pair of oil and gas companies at rather different sizes.
Seplat Energy (LON:SEPL)
StockRank: 97, Market Cap: £1129m, P/E: 10.1x, Yield: 6.21%
Seplat Energy is a Nigeria based oil and gas exploration and production company. It’s been a big winner for the 2024 NAPS with a 56% gain and appears again for 2025. It’s also one of the clearest trending mid-caps in the UK market at the moment, which shows the business has momentum and investor sentiment is improving. The first nine months of 2024 have seen two new oil fields brought on stream, including most recently Abiala, and the near completion of the Sapele gas plant. Free cashflow has been strong, with debt significantly paid down (from $366m in June to $270m in September) and the confidence to increase the dividend by 20%. The CEO is confident in the growth opportunities.
Shell (LON:SHEL)
StockRank: 94, Market Cap: £149327m, P/E: 7.8x, Yield: 4.98%
Shell plc is one of the world's largest energy companies, best known for oil and gas. It’s an absolute giant compared to the rest of the stocks in the portfolio and returns again to the NAPS after a 3.7% drop in the 2024 portfolio. The company significantly beat targets in its latest quarterly results, with adjusted earnings of $6bn vs estimates of $5.4bn. CEO, Wael Sawan, has been streamlining management, cutting costs and simplifying its low carbon program. Another $3.5bn quarterly share buyback was announced. Compare BP whose profits dropped and buyback program is under review. With a 5% yield and low valuation there’s plenty to like for investors if you aren’t concerned by fossil fuels.
Financials
Three financials may be a first in the NAPS. A consumer credit company, interbroker dealer and early stage insurance investor provide diversity.
International Personal Finance (LON:IPF)
StockRank: 100, Market Cap: £288m, P/E: 5.8x, Yield: 9.18%
International Personal Finance is one of our 12 stocks of Christmas and has been written up by Graham here. I recommend reading his coverage as he’s the expert. Nonetheless, IPF serves higher-risk credit customers who are underserved by mainstream banks - think home credit, credit cards, and online loans across markets including Poland, Czech Republic and Mexico. IPF targets a 15-20% return on equity and has fairly robust financials. While it does have significant debt, the company is confident enough to have launched a £15m share buyback. CEO Gerard Ryan holds nearly 2 million shares and is well aligned with shareholders.
TP Icap (LON:TCAP)
StockRank: 99, Market Cap: £1950m, P/E: 7.9x, Yield: 6.3%
TP ICAP is a financial intermediary connecting buyers and sellers across financial, energy, and commodity products, with a network of over 63 offices in 28 countries. The company has been considering strategic options for its Parameta Solutions (like spinning off as a US IPO), which some were saying a year ago could be worth as much as the whole business. Ironically just the knowledge of this created increased demand for the shares. For the nine months ending September 30, 2024, ICAP reported a 5% increase in revenue, with growth driven by Liquidnet (14%) and Parameta (10%). ICAP is a real gem of a success story in the UK financial industry. It recently launched a £30m share buyback program, aims to sustain a 50% dividend payout ratio, and is paying down debt. After a 32% gain for the 2024 NAPS, it returns for 2025.
B.P. Marsh & Partners (LON:BPM)
StockRank: 99, Market Cap: £267m, P/E: 12.3x, Yield: 1.48%
B.P. Marsh & Partners is a specialist investor in small and early-stage insurance businesses. It recently sold a 44% stake in Paladin Holdings for £42 million, and continues to make new investments, most recently in a pair of underwriting agencies. The company reported in its July half year results that NAV had increased by 10% to £253 million (690p per share) while group funds rose to £80m. This is strong liquidity to execute on the growth strategy. It’s cash generative with a commitment to shareholder returns, with a buyback program and a dividend payout now promised to grow to £4m annually. It’s also one of the “clearest trending small caps” in the UK.
Healthcare
A couple of branded and generic medicines and healthcare product providers.
Hikma Pharmaceuticals (LON:HIK)
StockRank: 93, Market Cap: £4381m, P/E: 10.7x, Yield: 3.18%
Hikma Pharma sells branded and non-branded generic medicines across across EMEA and North America. It reported a 10% increase in revenues in the first half of the year to June, and upgraded its full-year revenue growth guidance to 6%-8%, with momentum in North America and MENA. They recently acquired Xellia to strengthen their injectables business which is expected to boost earnings after the first year. The business is seeking to expand in Europe and continues to invest in R&D. It has a reasonable track record of revenue growth in recent years, but margins haven’t been sustained. Could that now be turning around?
Alliance Pharma (LON:APH)
StockRank: 85, Market Cap: £247m, P/E: 9.2x, Yield: 0%
Alliance Pharma has been in and out of the NAPS over the years. It’s a UK-based, but international, healthcare group focused on consumer healthcare. I don’t know if Nigel Wray still has a holding, but Slater Investments who I do respect have a 13% position. The business has an asset-light model and tries to maximise its brand values across Europe, North America, and Asia Pacific. Recently, the company reported strong revenue growth, notably from its Kelo-Cote (anti-scar silica gel) franchise, despite challenges like destocking in Nizoral. They have a new CEO since May, Nick Sedgwick, and they’ve recently had a successful appeal against the UK’s CMA which has relieved a £7.9m provision. Trading is unexciting with only a 2.8% revenue increase in H1 2024, but good cash flow and reduced debt. The shares have had a big knock since 2022, but have started to show signs of a “bowl” formation. Perhaps value and momentum will recover here?
Industrials
A range of businesses, some of which do seem rather oddly classified. From radiators to sports drinks to maritime services.
Supreme (LON:SUP)
StockRank: 99, Market Cap: £204m, P/E: 8.8x, Yield: 2.73%
Supreme plc distributes and manufactures a wide range of consumer brands to shops in the UK. From soft drinks to batteries to lighting to sports nutrition to vapes, the business covers a lot of ground. Supreme's financial performance has been strong, with half year revenues up 8% in September and pre-tax profits up 25%. It also announced it’s ahead of expectations for the full year - which we like. The company is debt-free (excluding leases) is growing dividends quickly and has a small buyback program. It’s acquisitive and seems very well run, and we have to give it some kudos for saving Typhoo tea. The black spot is the vapes exposure, which depresses the valuation, though the business has plans to shift into rechargeables.
Ocean Wilsons Holdings (LON:OCN)
StockRank: 99, Market Cap: £465m, P/E: 7.1x, Yield: 6.14%
Ocean Wilsons is Bermuda based and operates a couple of subsidiaries - Ocean Wilsons (Investments), which manages a global investment portfolio, and Wilson Sons which is a maritime services business in Brazil. The company is planning to divest its majority stake in Wilson Sons for 4bn BRL in 2025 which will focus the business on its investments portfolio. At that stage it will likely be excluded from the NAPS as I don’t include Collective Investment vehicles, but it sneaks in this year. In Q3 2024, it reported a 12% increase in Wilson Sons' net revenues and a 6% rise in the investment portfolio. Of note is the fact that Roland recently sold OCN out of the SIF Portfolio.
Stelrad (LON:SRAD)
StockRank: 99, Market Cap: £175m, P/E: 9.1x, Yield: 5.65%
Stelrad makes and distributes a range of radiator products across the UK and Europe. Despite a revenue decline of 9% in the first half of the year due to challenging markets across Europe and Turkey, it still managed to increase operating profits by more than 13% - quite an achievement. The management are focused on cutting costs and improving margins and have stated they will meet full year expectations. While their markets are depressed there are positive noises from management that when the market recovers they should see a sustained period of profitable growth.
Technology
A couple of tiny tech sector bets make the cut from a very underpopulated tech sector on LSE. Some may be wary of MTI Wireless Edge.
Journeo (LON:JNEO)
StockRank: 92, Market Cap: £42m, P/E: 10.7x, Yield: 0%
Journeo has been prominent among private investors after exhibiting at Mello conferences. It’s a leading provider products like CCTV surveillance, telematics, and passenger information displays to the transport sector (bus and rail). Recently, Journeo has expanded its reach by acquiring Infotec, which was a real coup of a deal, and MultiQ in Denmark. The company brought in a record order intake of £24 million in the first half of 2024 and secured more contracts. In October, they reported a 17% increase in revenue, pretax profits up 65% and a strengthening in its cash position by another £1.8m to £12.9 million. It’s talking a good game over developing SaaS-based solutions for recurring revenue but most of this business is in hardware. It does have a real tailwind behind it as it could be a beneficiary of green government spending to improve transport efficiency in rail and bus networks.
MTI Wireless Edge (LON:MWE)
StockRank: 91, Market Cap: £36m, P/E: 11.4x, Yield: 6.36%
MTI Wireless Edge is not a business I know well - and to be honest, I don’t like foreign businesses that list in the UK. Nonetheless it’s an Israeli tech group, specialising in communication and radio frequency solutions mostly in Antennae, especially to military and commercial applications. Despite the conflicts, MTI appears to be operationally stable with revenues of $34 million and a 10% rise in net profit to $3.1 million for the 9 months to September 2024, backed by a strong net cash position of $4.9 million. There are growth prospects in 5G and defense markets, and it pays a dividend of 6.4% and has share buyback initiatives. It appears to have had moderate operating leverage over time, with 5% revenue growth over the last 6 years generating almost double the profit growth.
Telecoms
Not a sector I love, but one I use daily. A big stalwart makes the cut.
Vodafone (LON:VOD)
StockRank: 95, Market Cap: £17207m, P/E: 8.9x, Yield: 6.37%
One of the great growth stock winners of the 90s, but now lacking much excitement at all. Vodafone provides mobile and fixed services to over 330 million customers in 15 countries, and is develoing a lead in financial technology services in Africa. Vodafone has been strategically streamlining, recently selling its Italian operations to Swisscom for €8 billion and its Spanish business for €4 billion, while merging in the UK with Three. Despite a 2.5% decline in Group revenue to €36.7 billion due to these disposals, service revenue grew by more than 6% in 2024. Vodafone met its financial targets in 2024 and should continue this stability through 2025. Other than all the net zero corporate greenwashing in every announcement, there’s a lovely 6.4% dividend to pick up while you wonder if it’s worth more than 9x earnings.
Utilities
One of the best growth stock stories in the UK market in recent years that trades on a very low P/E.
Yu Group (LON:YU.)
StockRank: 98, Market Cap: £302m, P/E: 8.5x, Yield: 3.62%
Yü Group PLC is an up and coming supplier of gas and electricity to businesses, while also providing smart meters and other solutions. The company has been generating some of the best growth figures in the UK market but still trades as a value stock - it’s our only utility in the portfolio. In the first half of 2024, revenues increased 60% to £313 million and a 52% rise in eps. They reported a 125% boost in smart meter installations at the mid year point. Yü Group maintains a strong net cash position of £87 million and is on track to meet its year end targets. It has impressive growth and a commitment to shareholder returns through a progressive dividend policy. It’s targeting market share in a £50bn+ market - so plenty to play for.
As usual, one of these stocks will probably double and one will halve. If you know which one is which, please let us all know in advance!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
85 comments
Got my timing completely wrong on Yu. Down 20% :-/ overall doing quite nicely though.
My portfolio is a mix of naps and some other shares I’m interested in.
In the article you repeated that the criteria for NAPS 2025 are:
What I cannot find is what the 'tie break' criteria are. So if, in a sector there are, say, 4 stocks all with a StockRank of, say, 99, how do you decide which 2 stocks are picked for NAPS?
If you look at Browse then top Stocksranks then top Stockrank, they are in order, they maybe 99.4 or 99.2 or 98.9, but it only shows 99 on the screen. That is what l go by. It is shame the double sorting, was lost with the new system, that was so useful for this exercise. You could sort by sector and it was sorted by ranking order as well.
Yes it might be ideal if on download we gave the decimal places... but the ordering is accurate I believe.
They haven't built a reservoir for decades and have diversity hires in charge of the fire department. There is a greater and faster risk to civilisation than climate change.
In my haste to reinvest my wife's ISA to follow the 2025 NAPS, I did not notice that Alliance Pharmaceuticals had received a takeover bid and bought them at Friday's price. So rather than getting a nice lift, I have taken a hit on spread and transaction costs. It might be prudent to put a note in the table above to say don't buy these now ED.
It does say on the Stockreport "This security is involved in a takeover situation".
Always worth checking the charts, before buying any shares, it usually fairly obvious from that.
Even if not a take over, l would rarely buy any shares, that have a spike up.
I've re-modelled most of my portfolio over the last couple of weeks based on Ed's NAP articles with a few personal selections e.g. Marks and Spencer (LON:MKS) replacing a sin stock; Imperial Brands (LON:IMB) . 10% down on that one currently for my troubles - more profitable perhaps to be a sinner! Luckily short term losses offset by Alliance Pharma (LON:APH) yesterday - also I need to get out of s-t term mentality! Will have a look at Ed's comment re possible replacement. I'm used to using stop losses but veering away from these for NAPS. May just use for the speculative stocks with level matched to volatility - e.g. Serabi Gold (LON:SRB) - a sector in which I have no previous experience.
The more the pious ESG-ers avoid the sin stocks, the greater the return for the sinners.
But don't tell 'em...
Los Angeles just the latest climate related disaster ... ? Something needs to change...
It is going to get worse, with Trump in charge.
Although not a climate change denier they think the fires were started deliberately, my house nearly burnt down when a wheat field behind me was set alight by idiots throwing away a disposable bbq in 2022, two of my neighbours houses were burnt down completely my entire garden was destroyed but house was 99% okay although all rear window facias were melted.
We needed ten fire engines to get it under control, we all had to evacuate for six hours to the local community centre I went back later to see if the house was still standing thankfully it was. I thanked a fireman and got chatting and he said 90% of these types of fires they dealt with as a result of dry wheat/grass were started deliberately in UK.
The frightening thing is the speed these things move at I live in an old house with a long garden when I saw what was happening I ran in to tell my son we have to leave now this took 2-3 minutes when I came back outside the fire was another 10-15 metres up my garden it was like what you are seeing in LA I had a hedge of mature confiers about 20 meters long these were utterly ablaze in about three minutes, proper scary stuff.
The other thing was even after the fire brigade had got it under control we were having to go round the garden with a hose for another 3-4 hours afterwards as small fires kept braking out again.
The field behind us had firemen checking it for a week as even though they put the fire they told us they knew fire was still burning under the soil which I imagine for the poor people of LA will be a huge challenge given the area to cover that might still have fires burning beneath the earth.
We were fortunate it happened in the daytime not 2am in the morning when we were asleep as given the speed it all happened it would probably have been curtains for us.
If they find that someone has started those fires near LA deliberately it should be life imprisonment.
Wow scary stuff Phoenix... glad that you all emerged unscathed...
Agreed re imprisonment, but I'm struggling to believe that they were all deliberate... and even if there were, sadly the fires have been exacerbated by the extreme weather conditions...
That's it Cancun the summer we had that year was bone dry and as we all had a lot fencing panels it ate through them at speed , I can remember it raining ash down on me and was difficult to see due to the smoke obviously compared to the poor people of LA it was small beer.
I agree not all will have been started deliberately and its a problem you can only see getting worse/happening more often moving forward.
Off topic of the thread but thought I should mention it. Friends lost their house and all their possessions to a fire last year. Recalling a list of all their possessions and proving they had them was almost impossible. As a result can I advise everyone to open all their cupboard doors and walk round the whole house videoing each and every room so you have evidence of your belongings should the worse happen.
Spot on take photos of valuable stuff thankfully our insurer was really good only chipped us down on garden plants the value lost of plants to replace was near 5k but we were only covered for 1k.
Same as outside furniture only 1k which is the cost of a decent outside pine table and four chairs alone, but other than that they were brilliant just credited the bank account and we could choose our own trusted tradesmen for repairs.
Great start to the year for the NAPS with Alliance Pharma (LON:APH) bid today, and the gold stocks flying. Already a 5% gain. I'm going to comment more broadly on this next week for the "QVM Portfolio" - as the APH bid illustrates that we shouldn't just sit with a position in cash when this closes !
Also - the NAPS is now at an all time high again...
Guess, I should have paid more attention to Edward's selection of Alliance Pharma in the Naps and not substituted my own choice of Beximo Pharmaceuticals, but I have managed to overcome my reluctance for "sin stocks" and am thoroughly enjoying all advice and successful starts to the year of Supreme, MWE, IMB and Shell, none of which I had ever previously considered. many thanks
I did not pick Alliance Pharma (LON:APH) does not make a profit for one thing. Debt is quite high.
The underlying portfolio statistics are really remarkable. On average, each stock has grown earnings by 42%, has a P/E ratio of 8.7, a return on capital of 16%, margins of 14%, has beaten the market by 19% over 12 months and yields 4% in dividends.
Is it possible to get these statistics easily on stockopedia portfolios?
" Simplicity beats complexity in my experience." - Well said Ed, if you mean the Stock Rank algorthym. I put it to the test today, looking at a virtual portfoio I constructed last April from 61 rewarding companies over the year 2023. Run with the winners as per the adage. Of these, 31 gained over the ensuing 9 months, 29 were losers and one with no change. Just on the Stock Rank the winners averaged 82.3, the losers 64.2, so there we are, a proven case. All these companies had (have) potential but volatility plays its part and the Stock Rank may change. By the way, Serabi Gold (LON:SRB) rose 92.5% and Shoe Zone (LON:SHOE) lost 61.7% in the best and worst scenarios. Separately , another virtual portfolio, My NAPS 2024, fractionally beat the FTSE All Share Index and gained 5.8%, not great but shamed my real portfolios. A new NAPS for 2025, the Silver, has been in being for 5 days now, is leading the FTSE All Share by a nose and is made up of 34 compamies which are a mix of Sector choices and some of my own. If I had nerves of steel I would sell everything in our portfolios and make a new start today with what I have learned from yourself Ed and Stocko.
Great article to supplement and advance the selection and your previous explanation for the 2024 naps list. I especially liked your reasoning notes and am keen to adjust my own holdings accordingly, but would like to confirm that the idea is to share investment capital equally between the 20 stocks selected rather than give equal weight to those such as mining which are having such a good run at present? Thanks for your efforts.
Robert,
I've always tried to maintain that the NAPS is more an illustrative set of principles, which can be personally adapted, rather than a set of recommendations to be copied.
We all have our own constraints, portfolio sizes, biases and goals after all.
Nonetheless, I do believe equal weighting is a sound approach and it has been used since the start of the NAPS. Simplicity beats complexity in my experience.
What's interesting about the stocks above is that they are not highly correlated, quite a few negatively so. The original NAPS below the first list similarly so. If you have an uncorrelated portfolio then it's a good thing. Perhaps that's why NAPS is so successful in part
Thought it would be fun to put together a NAPs porfolio based on VM and GM stocks > 70 but select on best trend over average of 90 and 180 days using adjusted slope >20. Check where its at in 12 months time!
OK have found how to get the GM scores.
Quilter (LON:QLT) seems to have the best GM/VM scores, trend is not bad. I have bought some recently.
Think there are few typos on your column headed 3/1/2025? Is that meant to be 3/1/2024? The first few figures seem to be incorrect.
Amended. Thx for the spot
Thought it would be fun to put together a NAPs porfolio based on VM and GM stocks > 70 but select on best trend over average of 90 and 180 days using adjusted slope >20. Check where its at in 12 months time!
Replace GM with M and see where you get.
Stockopedia abandoned active use of the Growth Rank years ago because it wasn't predictive of future market returns. Growth is some kind of function of the other ranks, probably mostly momentum. So most likely the GM ranks would closely track the M ranks.
timarr
Not quite. Some GM are similar to the M scores but not all. Synectics (LON:SNX) has GM 84 and M 99. There are quite a few others as well. AJ Bell (LON:AJB) GM 95, M79.
"The Stockopedia Growth Rank is based on a blended composite of forecast and historic growth rates."
"Originally we had provided subscribers with a composite GrowthRank which was blended with the other Quality, Value and Momentum rankings into what we call the composite QVGM rank. Our backtests proved, in line with research by other third parties, that growth is not a very predictive factor of future stock returns. Also Value is such a strong factor that its impact was diluted by the addition of Growth Rank. It should be noted that both Quality and Momentum are highly correlated with future growth, and in fact may be predictive of growth. We still maintain the GrowthRank for legacy reasons, and provide the QVGM rank for interested subscribers in both the screener and in tables."
https://www.stockopedia.com/le...
timarr
I can generate the performance histories of the GM and G Ranks. They just aren't available in the product at the mo.
Might be good for a blog at some point... but very briefly:
(All quarterly rebalancied - which perhaps isn't ideal).
I personally don't love how we constructed the Growth Rank. It was quite in line with what S&P and some index providers do, but Growth is quite a mean-reverting series - so ranking for the top 3 year growth companies isn't ideal.
Also the "long term growth" forecast from IBES is possibly quite a mean reverting series too... there's some great research on this which I want to write about too - too much to do.
---
Important to note though @Paul Walton that blending GM and VM might well have merit - as you will be removing most of the highest rated glamour stocks from the pool - and perhaps find growing value stocks.
Sorry wrong screenshot
Alliance Pharma (LON:APH) replaced with Good Energy (LON:GOOD, now have 1 utility zero before. Energy stocks may have a good year with Trump coming into office
I hold Good Energy (LON:GOOD) and Yu (LON:YU.), why Good, it is only has SR 82? Could be taken over, that is why the share went up.
Sorry I didnt think I had any utility stocks but Yu (LON:YU.) is in there already, I wasnt looking at the current portfolio. Decided to have 2 utils rather than 4 energy stocks. There are no other Healthcare stocks to pick from to replace APH
I see. No, Healthcare are difficult to find that qualify, l have Hikma Pharmaceuticals (LON:HIK).
Yes that's the best one but im selecting stocks with AS>20. No technology stocks either
I think VM and GM are the way forward
I believe the VM figures on here are wrong. 4th July, 2024, see big spike up, about 12%. This has been reported several times, to Stockopedia but not been fixed or any response from them.
Interesting statistics. My hunch is that GM outperforms even more with US stocks, but I would be keen to know if anyone else has the empirical evidence to confirm.
Combining 2 factors you tend to get better results
Momentum on it's own is the top performing Stockrank.
Momentum is the best performing indeed. It also has a little magic in it as it's based on both Price and Earnings Momentum. I believe that Earnings Momentum is more predictive of growth, than ranking on growth alone.
I did put together a US version of Naps, it performed 60%+ but one stock looked a bit odd which skewed the results
Paul, was that originally posted up in the discussion threads and, if so, do you kindly have a link/reference?
Without the top one (not sure what happened there) the return was worse at just under 15%. If i was to do it again id probably go for stocks in the SP500 rather than the whole universe. There's too many small caps otherwise.
Thanks!
How do you get the GM figures?
Growth has been the worst performing, stockrank. But combined with momentum could have merit. The top growth stocks do have decent quality ones among them. I will have a look at some charts.
Problem is you don't when they got into the top 25 growth stocks. Some decent ones thefe, 3i (LON:III) Cairn Homes (LON:CRN) but also Vistry (LON:VTY) Travis Perkins (LON:TPK)
The NAPS portfolio I put together around the same time. Biggest winner Serabi Gold (LON:SRB) , biggest loser Ingenta (LON:ING) . Overall a 22%+ return
Mine was similar but l had YouGov (LON:YOU) which was down 64%. Also Redrow which got taken over. My download is not all good. Think it was +20%.
NAPS
Thanks Ed for publishing this much anticipated list in good time before the weekend.
I enjoy reading the list but equally I really like the comments by other subscribers, my great thanks to these mostly unknown heroes!
Ed,
A surprise miss is the absent of housebuilers! Not a single one made the cut?
For contrarians, the choice have been made easier!
Galliford Try Holdings (LON:GFRD) is close but it in the Industrial sector. Difficult to compare they are spread over 3 different sectors.
Yes - many of the large house builders have seen a share price correction recently, so their momentum is low. On a QVM basis, they missed the cut.
Hi Ed,
You say above "Just to illustrate the point, we know that we should sell immediately on a profit warning". Are there any plans to introduce alerts for profit warnings? Ideally I would like to enable profit warning alerts by folio i.e. not have to set alerts stock by stock.
The link to "sell immediately on a profit warning" results in a 404 warning.
Sorry, I put the wrong profit warning link in the article. It's here - https://www.stockopedia.com/ac...
Looking at Metals Exploration (LON:MTL), always thought the spread was wide but Stocko have it as 187bps but in fact it is around 700bps.
A lot seem to be incorrect Yu (LON:YU.) is 110bps on Stocko but is actual around 300bps.
Spreads can be volatile at this time of year when trading volumes are low. We compute daily with the end of day bid/ask.
May be I'm nitpicking but.. as a NAPS fan..
You say "let’s just say that this [yearly NAPS] is under review" Then you say "So we may find that we can’t beat the NAPS, but that shouldn’t stop us trying."
Agreed. BUT how will you know if you stop running the yearly NAPS?
Only after several years will we know if greater turnover, costs, implementation will work.
Agree that an active NAPS like portfolio will be fascinating to watch in real time. But even if you backtest such a model (using past Stockopedia data) it will probably not Forward Test as well as you expect. The act of observation (and front running by other market participants) often changes results more than you might expect. Low frequency trading is most likely to be more robust.
I look forward to the experiment!
Well keep tracking it. We want to overhaul the GuruScreens and integrate a range of model portfolios and stock picking lists. I'm sure there will be a permanent space for annually rebalanced StockRank strategies there.
Be very interesting next year end. Some of these need more belief than that in Santa Claus. Currys (LON:CURY) margin was a no-no but he-ho, delivering all those bricks and presents is a compounder at work.
Phew!! Thanks for another year of unadulterated NAPS. I hold only 5 of them and will consider at least 5 of the others. Vodafone (LON:VOD) made me laugh. So useless and hated a stock it must be its turn in 2025!!
Happy New Year to Ed, the team and fellow subscribers!
Congratulations on beating the S&P500 over 10 years. That is very impressive. I've been following this from the beginning but sadly my own returns haven't matched these levels. Behavioural biases can be tough to overcome even when we know about them, e.g. after Brexit I sold and didn't get back into the market quickly enough. Still I've no doubt my returns were better with Stockopedia than without. Glad to see that NAPS is still going for another year and that you are working on similar ideas in model portfolios readers can track.
A Happy & Rewarding 2025 to You Ed and ALL the team, thanks for continuing The NAPS and all your other in depth articles on the navigation & use of Stockopedia along with the Art of investing.
Re evaluating regularly certainly helped me this last year and interesting to see that something similar may be introduced in the new QVM . I just compared the Naps history to the SR Performance history, balanced quarterly, the fall of the top rank was down to only 200 not 150%, certainly food for thought.
I select my stocks using Stocko' but with a different system ,nice to see it includes some of your selection.
Looking forward with confidence to the coming months & lots more informative articles.
Wishing you All and The readers a Prosperous Year.; from one not having been immersed in Square mile Culture, Thanks.
Ed, Pan African Resources (LON:PAF) did appear, on your perfect stock screen, for quite a while in 2024.
Serabi Gold (LON:SRB) is close, only fails on the dividend rule, which l don't agree with anyway. The big multi baggers would fail on that rule, such as Yu (LON:YU.).
FWIW I thought I'd keep an eye on the "perfect stock" screen linked to in Ed's piece above to see if anything popped onto it. I notice this morning one stock has i.e. CMC Markets. link: https://www.stockopedia.com/sc...
Peter, thanks. That is interesting, it is one of my larger holdings.
This screen does seem different, from Ed's previous screen, that l copied over.
I will have to find Ed's previous screen to check.
CMC Markets (LON:CMCX) fails on the EPS Growth Rolling 1y > 15% rule, on that screen.
Interesting. I have a similar screen which has CMC Markets (LON:CMCX) Impax Asset Management (LON:IPX) RWS Holdings (LON:RWS) and M P Evans (LON:MPE) as its only constituents.
The issue with CMC Markets (LON:CMCX) at the moment seems to be that the market is against it. It's in a determined downtrend. I've got out and sitting on the sidelines for now....
Hi Ed, I'm discombobulated and wondering if you could please help me. When I look at your chart I see Drax (LON:DRX) appears on it but Drax (LON:DRX) doesn't appear on your list below. However, when I look at your list I can see Yu (LON:YU.) appears on it but Yu (LON:YU.) doesn't appear on your chart above.
FYI, I have kept the vast majority of the shares which I held in my 2024 portfolio and I'm hoping they continue to perform well in 2025. 2024 was an exceptional year because the bounce came off the lows of autumn 2023 so 2025 might be more challenging.
The shares I hold for 2025 can be viewed by clicking on my avatar.
Wishing a Happy New Year to you, all the editorial team and to all subscribers at Stocko.
David.
@Logical David - apologies, I'd published the wrong chart. Amended.
Hi Ed / Logical David - Pleased to see £YU on the list as Ive been considering this fora little while. For me it ticks a number of boxes - profitable/has cash in the bank and pays a sensible divi - and a little bonus is AIM and so qualifies, I reckon for IHT relief. I'm trustee of a local small charity and will get a quote from YU. (Annoyingly, charities are classified as businesses and cannot go onto domestic tariffs) Will be interesting to see how they compare.
BTW - wouldn't touch DRAX with a bargepole - importing timber from Canada on gov subsidies - its been a sham for the past few years.
Drax (LON:DRX) is also by far, the largest producer of CO2, in the UK, 2.9%.
l completely agree. Cutting down ancient forests, in America, to burn in the UK, with all the pollution and transport, is just crazy.
Even worse than Palm oil.
A lot of stocks on the list this year, l would not touch. Tobacco, vaping, home credit, Israel, wide spreads etc.
Hi Ed,
Happy New. year to you and all the team - the NAPs portfolio interesting as always. However, you seem to have dropped the criteria of only one stock from each industry sector (e.g. 2 gold miners, 2 speciality retailers, 2 investment banking and investment services, 2 pharmaceuticals). Are you concerned about this apparent lack of diversification if there is a downturn in one or more of the sectors?
ACounsell - I have in the past at times selected a maximum of one from each industry group. It's certainly a constraint that is reasonable. As with all additional constraints, each will drop the average StockRank. So there is a tradeoff between risk and return. I didn't use this additional constraint last year.
Hi Ed
Happy New Year to you and the team
I have recently started running virtual NAPS portfolios on a monthly basis. I am using the the basic criteria very similar to that you are applying this year.
I haven't, however excluded funds. So both Jupeter Fund Management and Blackstone Loan Financing have made the January cut for me.
What is you rationale for leaving funds out?
Iron
I remove any stocks in the industry group "collective investments" - after all, we are building our own "fund" by doing a NAPS, not investing in someone else's!
Jupiter is a reasonable selection as it's an operator of funds - it's not a collective investment. It was ranked too low to make the grade yesterday.
Hi as an FYI Blackstone Loan Financing (LON:BGLF) - (I hold) is in the process of closing down the fund (in Jan) and wouldn’t be a good investment just now as the upsides have been paid out recently.
Impressive returns. Is there supposed to an xmas stock today, as one hasn't appeared on the front page?
Thank you once again Ed. I assume dividends not reinvested.
Yes - I've normally taken the assumption that dividends cover transaction costs, so have excluded a total returns calculation. Net dividends are not reinvested in these calculations - and they ought to be.
It's worth pointing out that the yield this year is 4.1%, but the spread only 1.3%. Even if we add in stamp duty of 0.5% and a generous 0.25% for commissions, there's still almost a 2% dividend yield net of costs.
Some years though in the past have had wider spreads and lower yields. And larger portfolios in small caps can see slippage and market impact costs... so I've felt it conservative to exclude the divis.
Thank you and HNY
Thanks Ed for keeping this going. May I ask why Enwell Energy (LON:ENW) missed the cut off. According to my screen it's No 1 in the energy sector, so assume it's spread. If so, are we able to check the spread via the STOCKO page
HNY.
Yes - Enwell missed the cut due to the spread which is 9.09% according to our data. There's no doubt you can probably buy stocks like this at a lower spread.
You can add the bid/ask spread to tables, and see it in the "full quote" popup on StockReports.
Serica Energy SQZ is ranking above Shell and has right spread. Any reason why it was omitted? And yes, thanks for keeping this going.
Serica was below Shell yesterday when I created the portfolio. Today vice versa.