Next trading well internationally; still not buying back its own stock at this share price

Analyst’s view:
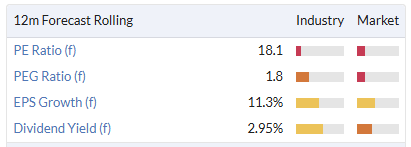
I'm staying moderately positive on this share, purely on valuation grounds. If the company itself doesn't view its shares as a bargain, then I shouldn't, either. And honestly, paying an earnings multiple of 18x for any retailer, even the one that's best-in-class, is an aggressive bet. Therefore, while I remain a fan of this business, as I have been over the long-term, I wouldn't be tempted to open a new position in the stock at the current level.
Up 2.1% at £159.35 (£19.1bn) - Trading Statement
[At the time of publication, Graham has a long position in NXT.]
I usually have nothing bad to say about Next plc. But I must dock them a few points today for putting their trading statement in an PDF file on their website.
They aren't the only company to do this. It's very much a trend these days, particularly among larger companies.
It's a simple solution for companies, but it's not investor-friendly, so I'd like to see this trend reversed.
Thankfully, Next remains investor-friendly in the ways that matter most: by generating profits and meeting or exceeding expectations.
Full-year guidance is maintained, for pre-tax profit of £1,255m (up 8.4%).
Key points:
Quarterly sales up 8.1% year-on-year. Guidance was for H2 sales up 5.8%.
Sales outperformance has come entirely from international business, with the additional £5m of gross profit being offset by increased international operational costs.
One of Next's big wins in recent quarters has been the success of its international business, where marketing has turned out to be more effective than it expected.
So it's no surprise to read that the international business is driving sales outperformance, even if it's not immediately converting into profit upgrades.
Sales by division
UK Online is up 4.4%, while UK Retail is down 1.7%.
The company's ability to plan for and adapt to a weak environment for retail stores is one of its defining characteristics, so I'm not concerned by the decline in UK Retail.
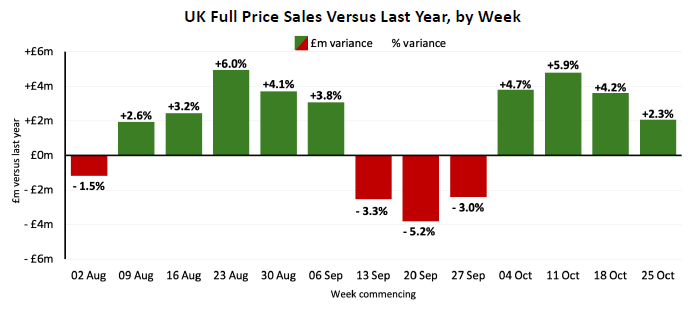
Even if we include the more resilient online operations, UK performance is not invulnerable to macro conditions. Full price sales were negative some weeks during this quarter (which the company says was due to unseasonably warm weather in September):
Online International is up by a remarkable 32.2% in the quarter, faster than the total year-to-date growth rate of 26.8% (i.e. there's been an acceleration in this quarter).
To give a sense of their respective sizes, UK product sales were £2.3 billion in H1, vs. International sales of £774m.
So while most of Next's sales are still firmly rooted in the UK, International sales are already of major importance - and growing rapidly.
The internaional marketing spend in the quarter rose by a remarkable 67% year-on-year, for the simple reason that it's working!
Guidance: guidance looks conservative to me, as usual. Next tends to pitch its guidance at a level that it can beat.
For Q4, it's guiding for UK full price sales up 2%, the same as Q3. And it seems to me that Q3 was a little unlucky, due to the weather.
Internationally, it's guiding for Q4 full price sales up 20.5%. That's materially lower than both the Q3 result (+32.2%) and the expected full-year result (25.1%). They say: "International growth is expected to moderate as we trade against stronger aggregator growth in Q4 last year."
New guidance is for EPS of 820.6p (previous guidance was 820.8p, so I'm recording this as unchanged expectations).
Buybacks: they are guiding for £815m of net debt at year end (unchanged), and have £136m available for buybacks or acquisitions. However, their requirement of an 8% pre-tax return on buybacks creates a ceiling of £136.50. With the share price currently above that level, they may instead return surplus cash through a special dividend. That's extremely logical capital allocation, in my view.
Graham's view
I'm staying moderately positive on this share, purely on valuation grounds.
I'm as much a fan of Next as I've ever been. However, I'm reserving my "GREEN" (fully positive) positioning for when the company itself is buying back its own shares. That rule has served me well in the past. The logic is simple: if the company itself doesn't view its shares as a bargain, then I shouldn't, either.
And honestly, paying a multiple like this for any retailer, even the one that's best-in-class, is an aggressive bet:
Therefore, while I remain a fan of this business, as I have been over the long-term, I wouldn't be tempted to open a new position in the stock at the current level.
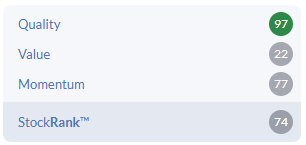
The StockReport agrees with me, awarding it a below-average ValueRank of only 22:
At the time of publication, Graham has a long position in NXT.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Next (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?