NWL: A platform of growth

Last month I wrote an article about a stock that is a quality compounder, PWR Holdings (ASX:PWH). (Read here). Another Australasian stock that meets the criteria for a quality compounder is Netwealth (ASX:NWL). The concept is based on an article written by Stockopedia contributor Roland Head, where he built a screen to find quality stocks that are strong compounders. (Building a screen to find Compounding Quality stocks) I took this screen and applied it in the Australasian context. 14 stocks currently meet all of the criteria.
Netwealth is one of the fastest growing financial services companies in Australia. Founded in 1999, in 2023 they are forecast to have generated $214 million in revenue. Revenue has been growing at a compound annual growth of 23% over the last five years and ten years ago was only $43 million.
Netwealth provides a digital platform that supports how financial products are delivered to the market. They service both financial advisors and personal investors. They provide clients with access to financial products including superannuation, investor directed portfolio services, managed accounts, managed funds, SMSF administration and aggregated reporting services.
Growth in Funds under Administration (FUA) and Funds under Management (FUM) are the principal drivers of revenue growth. This is determined by inflows from new and existing clients as well as the performance of investment markets. The graph below shows the growth in funds as well as accounts over the last three years.
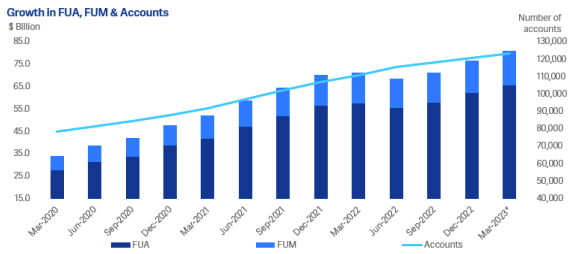
Source: Netwealth, March 2023 quarterly business update and outlook, 3/4/2023
Revenue growth has included picking up customers at the expense of the banks, AMP and Insignia. The chart below shows that Netwealth was the fastest growing platform in the year to September 2022. Despite this growth, they still only have 6.3% market share, suggesting that there remains a strong runway for growth.

Source: Netwealth, March 2023 quarterly business update and outlook, 3/4/2023
The financial advice/funds management industries have come under a lot of fee pressure in recent years. As Netwealth is a part of that ecosystem, and their fees form a component of the overall fee charged to investors by advisers/fund managers, their margins will continue to come under pressure. EBITDA margin for the first half of FY23 declined from 50.7% in the prior corresponding period to 46.1%. NWL’s net margin averaged 33.6% over the last five years but declined to 31.66% over the last 12 months. Of course, that is still a very impressive margin, but there is evidence of continued margin pressure.
Returning to the original premise of Netwealth being a Quality compounder, we see that NWL has a Quality Score of 97, placing it in the top 3%.
Digging down further we focus on profitability. We have already covered the high margins being generated. Next we look at return on capital employed (ROCE). In the long term, a company’s growth rate will be limited by the returns it can generate on its capital. The screener uses a threshold of 18% for Long-term ROCE. NWL is in another league at 61.2%. The most recent trailing twelve month (TTM) ROCE also needs to be above 15%. NWL is 64.8%.
Turning to cash flow we use two rules to test for cash conversion. Operating cash flow per share can be compared with EPS to ensure that accounting profits are backed up with cash. A cut-off of 0.8 gives some margin. NWL’s ratio is 1.1.
The cash yield also indicates the cash return being generated by the company’s assets. Netwealth’s cash yield is 36.6%, well above the screener threshold of 8% and the official cash rate of 4.1%.
Of course the screener is not just focused on quality, but also on compounding. To generate compounding returns growth is required. Given that we have already established that the business has high profit margins, we can focus here on revenue growth. As already noted, revenue has been growing very strongly with a 5 year CAGR of 23%, however it has tapered off to 10% over the last 12 months.
The final check is to make sure that the growth is not being fuelled by excessive debt thereby introducing a high level of balance sheet risk. With a Debt to Assets ratio at 9.6% it is easily under the 50% requirement.
The table below summarises all of the factors for the compounding quality screen, comparing NWL with the thresholds. As can be seen, they compare very favourably on all measures.
Criteria | Threshold | NWL |
QualityRank | 80 | 97 |
Long-term ROCE | 18% | 61.2% |
TTM ROCE | 15% | 64.8% |
Operating margin 5 yr avg | 10% | 46.3% |
Operating margin TTM | 10% | 43.7% |
Net margin 5 yr avg | 8% | 33.6% |
Net margin TTM | 8% | 31.6% |
OCF / EPS | 0.8 | 1.1 |
Avg FCF (long term) / Assets | 8% | 36.6% |
Sales CAGR 5 yr | 0% | 22.8% |
Sales TTM / Sales Prior TTM | 5% | 10.0% |
Debt to assets | <50% | 9.6% |
Interest cover | 10x | 100x |
So far the discussion has focused on quality and growth with no mention of value. These types of stocks are rarely cheap as the market recognises their strengths and bids the price up. Warren Buffett says his favourite holding period is forever. With that investment horizon the idea is that paying up in the short term will be compensated for by the long-term growth.
However for many of us we need to remain cognizant of the price we pay. A high quality business can still provide a low investment return if you pay too much for it. A premium is justified, but the question is, how much of a premium.
NWL peaked at $18 in late 2020. It bounced off that level again at the end of 2021. It then retreated and has been bouncing between $12 and $14 for the last year. At the present level of $13.49 the value score is a fairly dismal 7. The forecast PE ratio is 38.5, which places it at the upper end of the market, but when compared to NWL’s past is actually relatively low.

There is no doubt that Netwealth is a great business that has been run really well. Growth and profitability are likely to get tougher moving forward, but there is still a lot of opportunity if they can maintain the excellent execution of their strategy as witnessed so far. For investors with a value bent, the question is how much should they be prepared to pay.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?