Plus500 reverts to positive form with an update and an upgrade

Analyst’s view:
I cooled our stance on Plus500 in July but am happy to go back to a fully positive stance on the company today. That July update included a miss against H1 expectations, which was an important reason for my caution then. However, zoom out a little and the overall trend in forecasts remains positive. The market cap for Plus500 today is also noticeably lower than it was in July, and the earnings multiple is back at modest levels, without making any adjustment for the company's enormous cash balance.
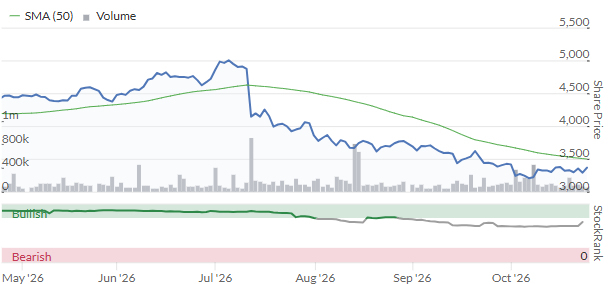
Up 2.2% at £33.64 (£2.4bn) - Q3 2026 Trading Update
This is an excellent update. The highlights:
Q3 revenue +11%, year-to-date revenue also +11%
Q3 customer income +9%, year-to-date customer income +19% to $641m
Q3 EBITDA +7%, year-to-date EBITDA +3% to $275.9m
Operationally, the number of new customers recruited rose by 27% compared to Q3 last year, enabling modest year-on-year growth in the number of active customers (4%).
On top of all that, average revenue per user was up 7% while average user acquisition cost was down 14%.
Bear in mind that the company has been actively expanding geographically, so it wouldn't really be right to call the growth "organic".
But with cash of over $775m, Plus500 is able to fund its own growth while paying dividends and buying back its own shares.
CEO comment:
"Plus500 has delivered significant strategic and operational progress in Q3 and throughout 2026, underpinning strong financial results. We expanded our global reach and product suite, which continued to attract increasing numbers of higher-value customers.... Customer segregated funds surpassed $1bn at period end, reflecting the ongoing trust customers place in us and strengthening the foundation for future revenue generation...
Two acquisitions were announced recently: "Guru", a broker-dealer in Brazil and "Hedge", a US broker-dealer. The price for each of these was undisclosed, implying that they are small, but together they indicate a continued ambition at Plus500 to expand into more regulated activities.
In the US market, in particular, Plus500 is planning the launch of a "super-app" that will consolidate futures, prediction markets, stocks, options, ETFs, etc.
The company already offers 24/5 trading on stocks and ETFs, and 24/7 trading on various commodities.
Outlook: "Reflecting the strong financial performance and meaningful strategic progress in the first nine months of 2026, the Board expects that FY 2026 revenue and EBITDA will be ahead of current market expectations."
Market expectations for 2026 are helpfully provided: Revenue and EBITDA of $837.6m and $358.0m, respectively.
Based on the numbers in today's update, the company had already achieved 77% of full-year expectations for EBITDA by the end of Q3, and nearly 80% of full-year expected revenue.
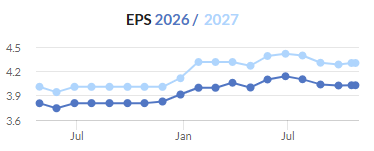
Estimates: thanks to Panmure Liberum for publishing on Plus500 today. They raise their 2026 EPS forecast by 3% to $4.12, but leave future years unchanged.
Graham's view
I cooled our stance on Plus500 in July but am happy to go back to a fully positive stance on the company today.
That July update included a miss against H1 expectations, which was an important reason for my caution then.
However, zoom out a little and the overall trend in forecasts remains positive. The chart below is prior to today's upgrade:
The market cap for Plus500 today is also noticeably lower than it was in July:
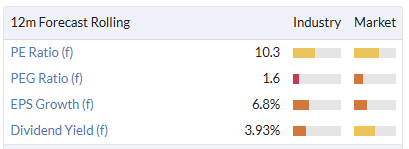
The earnings multiple is back at modest levels, without making any adjustment for the company's enormous cash balance:
For these reasons, I'm reverting to a fully positive stance here. That's a stance I've often taken when it comes to PLUS in recent years.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Plus500 (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?