QVM Portfolio +31% YTD - a bid and a drama triggers a new position

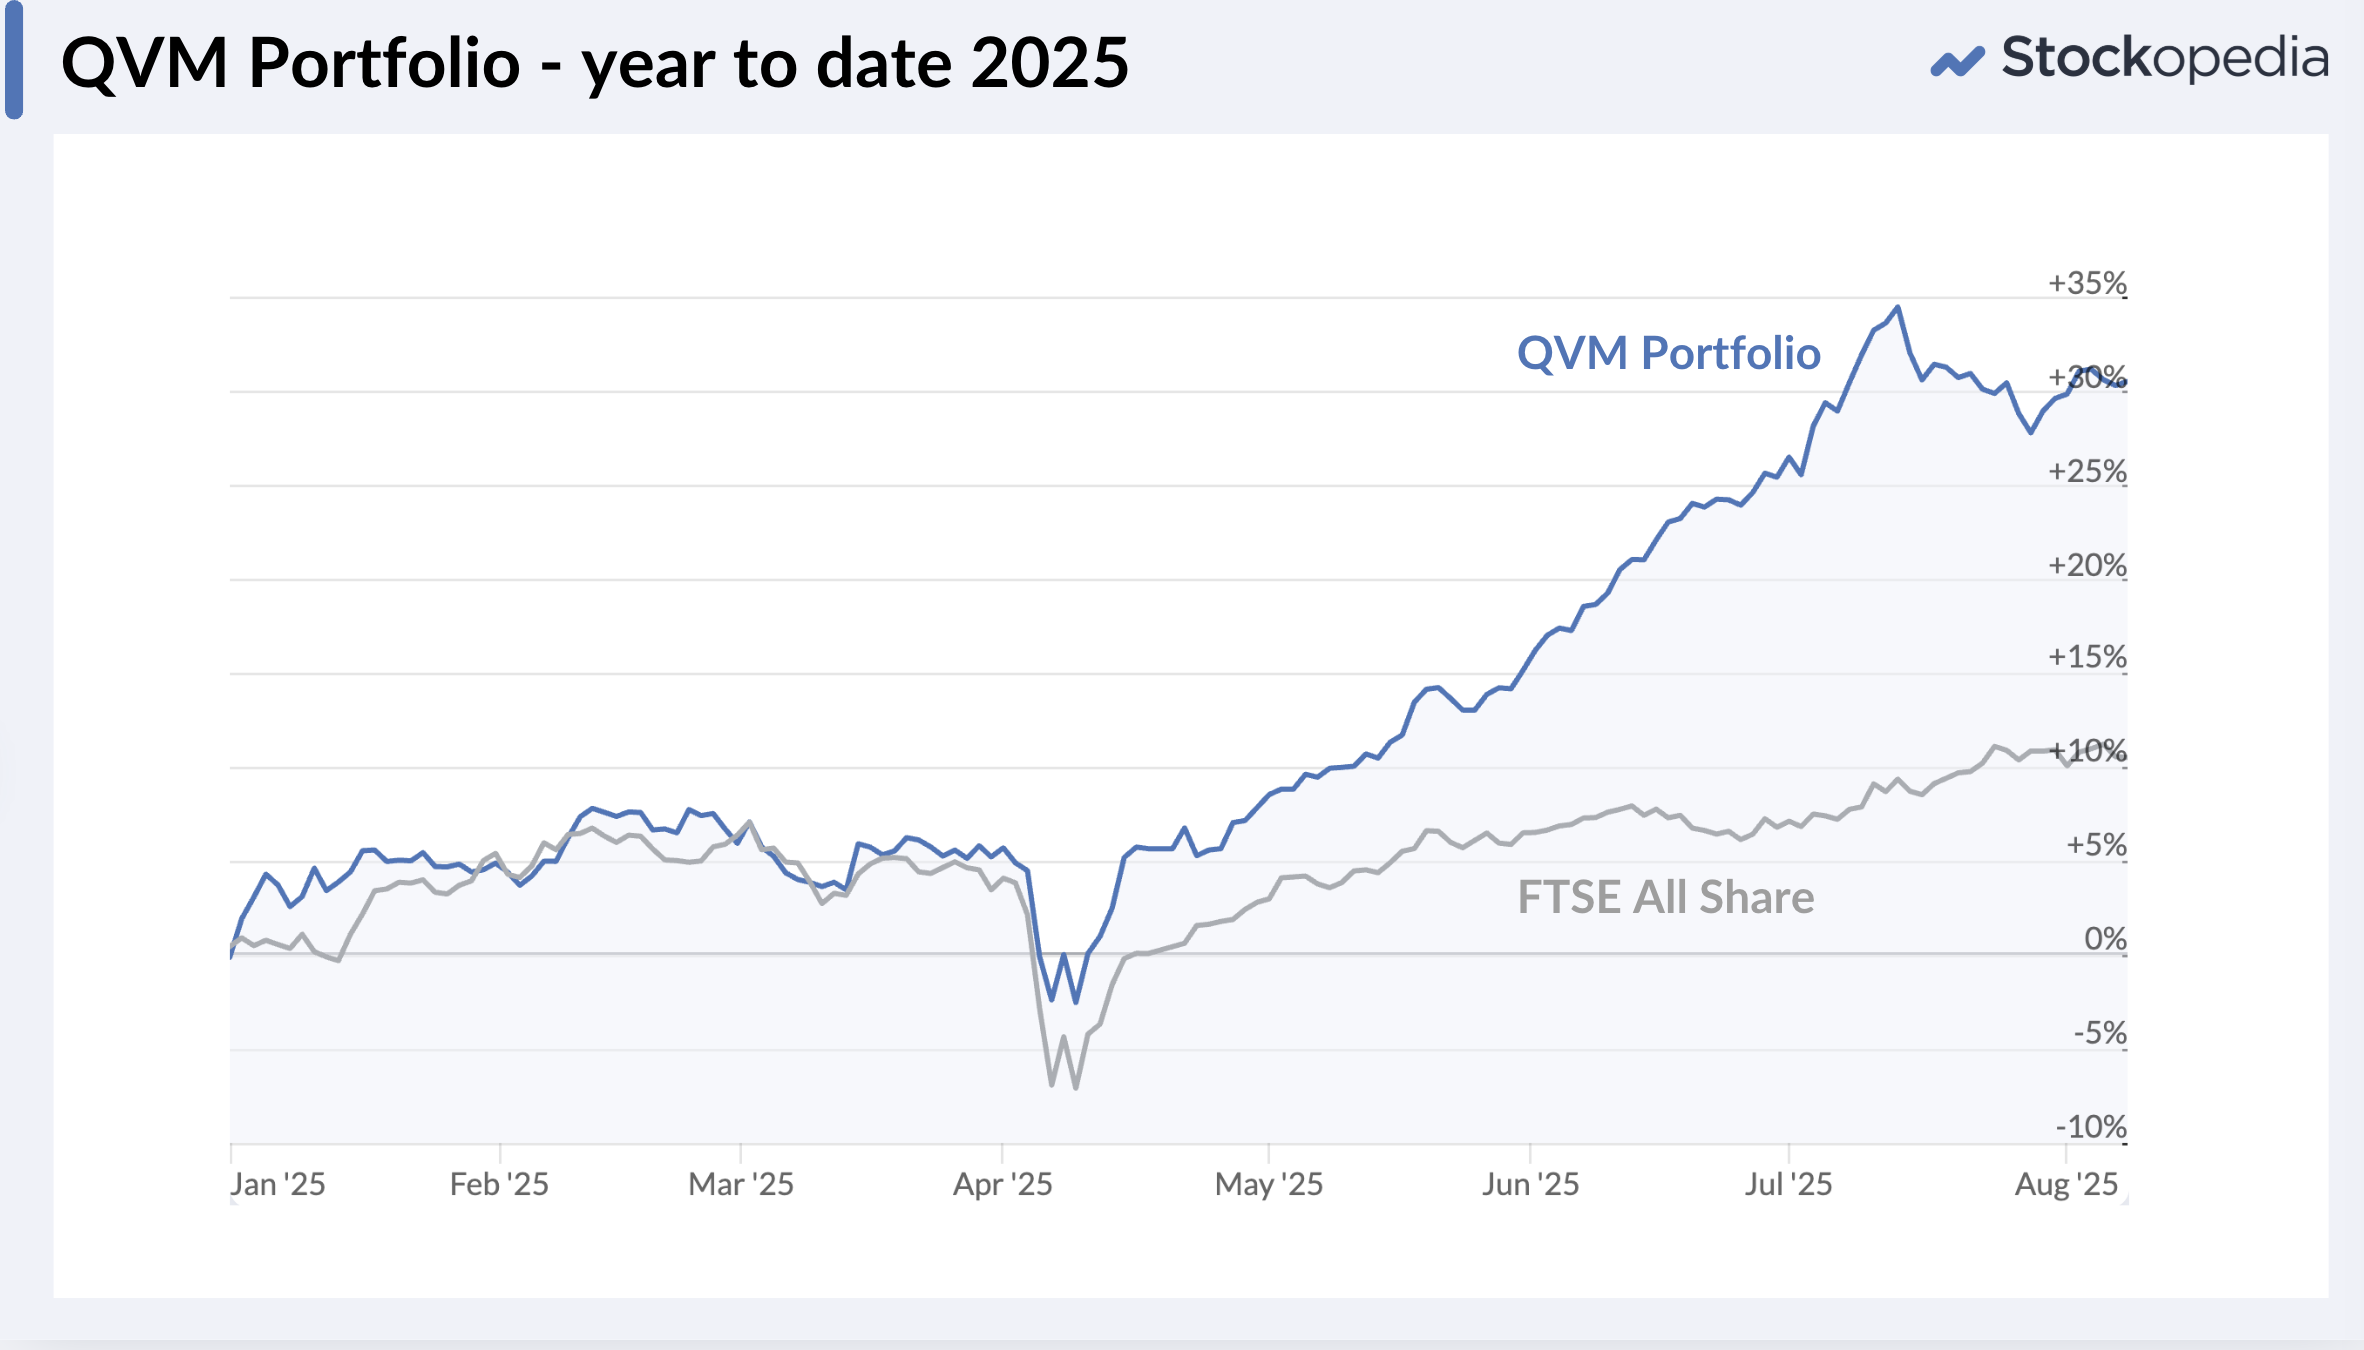
It’s been a stunning year so far for the QVM Portfolio, which has returned 31% before dividends. It's even tracking 4% ahead of the NAPS Portfolio, which began with the same holdings.
The only difference between them is that when Alliance Pharma received a takeover bid, the QVM Portfolio reinvested it in the next highest-ranked Healthcare stock - SDI (LON:SDI) - while the NAPS sat on the cash.
That turned out to be a fortuitous decision.
Since January 15th, SDI (LON:SDI) has gained 64%. But it's position size was larger than usual as I'd rolled Alliance Pharma's 33% gain into the position. So, this hybrid Healthcare holding has combined to return a 118% gain on the original stake.
Beyond this, the junior gold mining positions of Metals Exploration (LON:MTL) and Serabi Gold (LON:SRB) have contributed +160% and +89%, while Seplat Energy (LON:SEPL), Journeo (LON:JNEO) and M P Evans (LON:MPE) have all added 30-40%. It’s shaping up to be a strong year.
Another bid - should we rinse and repeat?
We can’t expect every reinvestment to work out as well as SDI, but on the 30th July, International Personal Finance (LON:IPF) received a ”possible recommended cash offer”.
The share price popped up 18% on the news. The bid is mooted at 220p per share should it go ahead - which is 4.7% above the current share price.
Now, this creates a bit of a quandary. It’s not officially a recommended offer. It’s “possible”. Could another suitor come out from the wings? Could the deal fall through? If it does, the shares might pull back, but the company is trading well and there's good momentum. It’s also one of Graham’s most bullish ideas - he owns it himself and thinks the bid is too low.
Nonetheless, one of my rules for the QVM is to sell on a recommended takeover bid.
But it’s not recommended yet. According to the takeover rules, the bidder has until the 27th August to confirm its intention.
If the bid goes through, it will probably complete October or November. There’s a 4.7% gain baked in if we wait, plus another 3% from a dividend if we hold past the 28th August ex-dividend date.
So while fortune favours the brave, patience is a virtue.
We wait. If it’s recommended, and we have pocketed the dividend, we’ll reinvest elsewhere.
A drop in the Ocean breaks the rules
The QVM Portfolio may have started from the NAPS Portfolio base, but it’s a more active approach. Things do happen - bids, profit warnings, weird corporate actions. That’s when we have to act - and my “rules of thumb” kick in.
Ocean Wilsons Holdings (LON:OCN) has thrown a few curveballs recently:
- It was bought as one of three high-ranked Industrials in January.
- In June, they sold their stake in Brazilian shipping giant, Wilson Sons, for $594m in cash.
- This divestment left the rest of Ocean Wilson as an Investment Company, with no industrial operations.
- They then announced a £123m tender offer to return some capital to shareholders.
- Then an all-share merger with the Hansa Investment Company (LON:HAN) was announced.
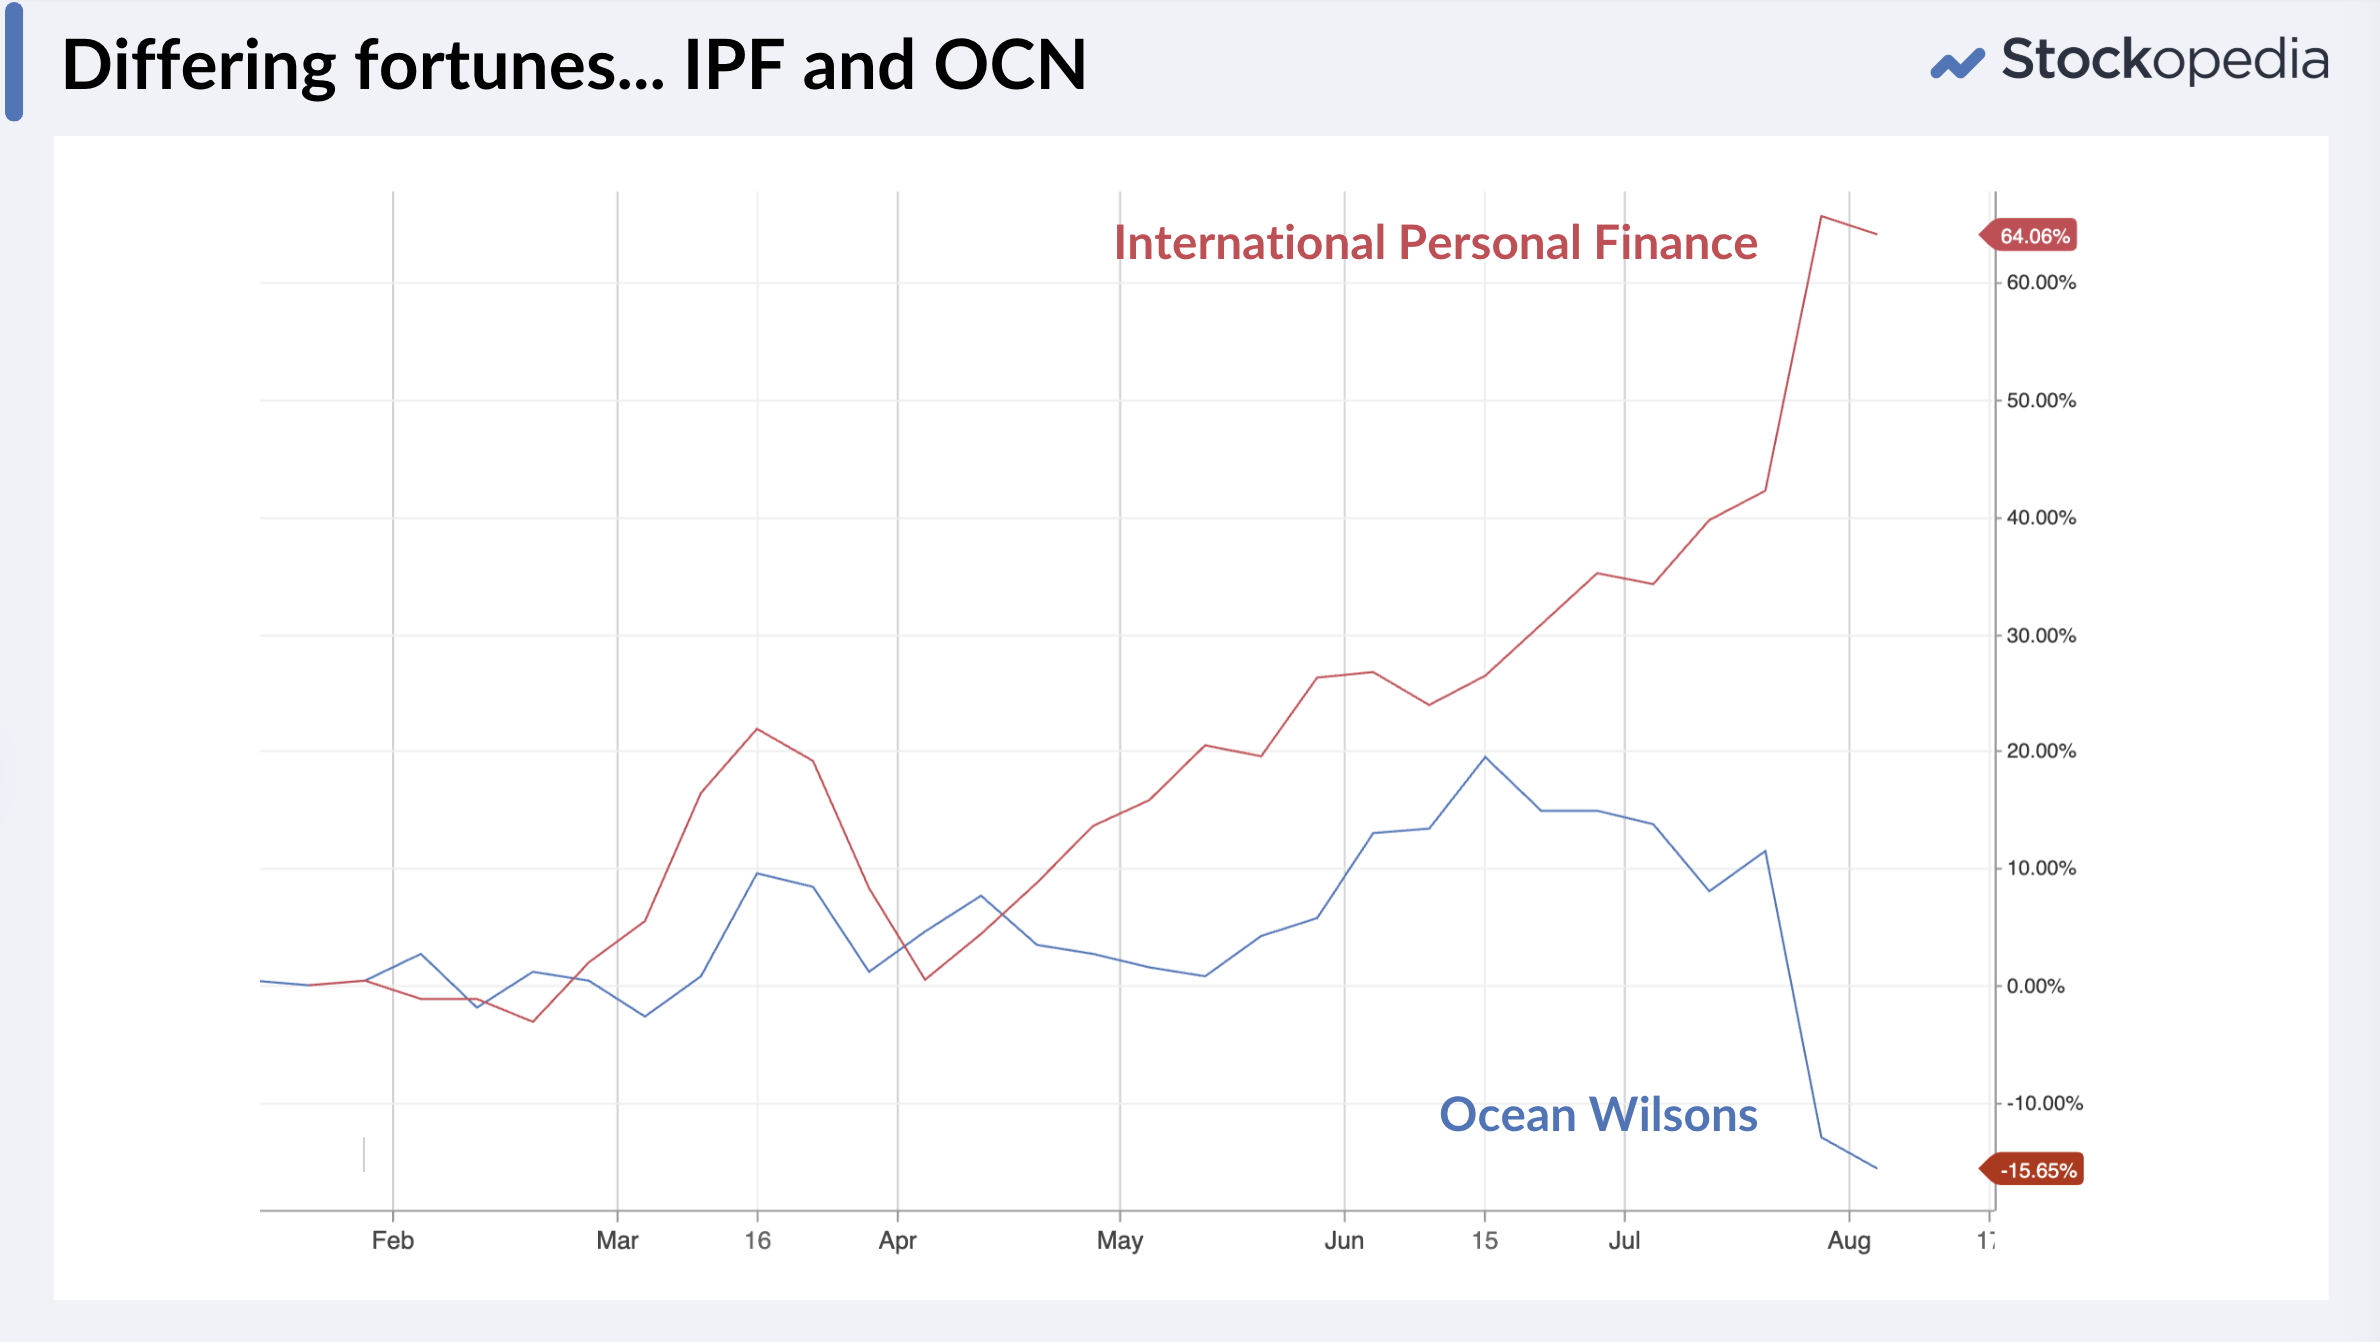
As soon as this news was announced, the share price fell off a cliff.
Why?
Well it wasn’t fear - someone had done the maths on the relative levels of the discounts to Net Asset Value (NAV) of the two investment companies. OCN shares will convert into HAN shares, which trade at a much deeper discount to NAV (37%). So the OCN shares dropped. Ouch.
You get a slice of the merged trust, but at a wider discount to underlying NAV.
What to do?
For the QVM Portfolio, OCN is now breaking three of my portfolio rules:
- Diversification - OCN has been reclassified from an Industrial to a Financial. The portfolio now has 4 Financials. That’s 20% of the portfolio’s positions in one sector. I can’t allow that.
- No collective investments - I specifically exclude funds and investment trusts from the NAPS and QVM screening lists. After all, I’m the investment manager of the portfolio and I don’t want to outsource decisions to a fund manager for single positions, even if there is a big discount to NAV.
- Soft stop-loss trigger - As of the close Friday, OCN is down 15% year to date. OCN has a “Balanced” Risk Rating, and 15% is my “soft” stop loss trigger rule.
So that's a decision. Ocean Wilson is SOLD today.
I’m immediately reinvesting in the next highest-ranked stock in my stock screen (as long as it complies with my diversification rules and isn’t already owned).
- Jupiter Fund Management (LON:JUP) is next in the list, but it’s another Financial, so it’s skipped.
- That brings us to Virgin Wines UK (LON:VINO) .
I can’t say I adore the idea of VINO. But I often don't like high-ranked stocks. There’s usually something “wrong” with them. In VINO’s case I believe that Mark went Amber/Red on it in the DSMR, it also has a wide bid/ask spread at 4%, and it’s only a £34m market cap.
But… rules are rules. VINO qualifies. So VINO in. OCN out.
Meanwhile, we will wait until the 28th on IPF. If the bid is recommended, another slot in the Financials sector may come free, so Jupiter could still be on the radar.
Current holdings
Here are the holdings and gains year to date before the OCN/VINO swap.
| Name | Total Gain % | MktCap £m | StockRank | Sector |
| Metals Exploration (LON:MTL) | 160 | 409 | 95 | Basic Materials |
| Serabi Gold (LON:SRB) | 89 | 154 | 100 | Basic Materials |
| SDI (LON:SDI) | 64 | 92 | 87 | Healthcare |
| International Personal Finance (LON:IPF) | 63 | 460 | 98 | Financials |
| M P Evans (LON:MPE) | 36 | 698 | 98 | Consumer Defensives |
| Seplat Energy (LON:SEPL) | 35 | 1617 | 95 | Energy |
| Journeo (LON:JNEO) | 34 | 64 | 93 | Technology |
| Vodafone (LON:VOD) | 24 | 20487 | 96 | Telecoms |
| Currys (LON:CURY) | 20 | 1288 | 94 | Consumer Cyclicals |
| Stelrad (LON:SRAD) | 19 | 204 | 93 | Industrials |
| Imperial Brands (LON:IMB) | 18 | 24387 | 93 | Consumer Defensives |
| MTI Wireless Edge (LON:MWE) | 12 | 42 | 72 | Technology |
| Kingfisher (LON:KGF) | 12 | 4835 | 99 | Consumer Cyclicals |
| TP Icap (LON:TCAP) | 10 | 2124 | 96 | Financials |
| Supreme (LON:SUP) | 8 | 221 | 91 | Industrials |
| Shell (AMS:SHELL) | 7 | 155622 | 54 | Energy |
| B.P. Marsh & Partners (LON:BPM) | -6 | 251 | 97 | Financials |
| Hikma Pharmaceuticals (LON:HIK) | -12 | 3861 | 79 | Healthcare |
| Ocean Wilsons Holdings (LON:OCN) | -15 | 313 | 64 | Financials |
| Yu (LON:YU.) | -19 | 248 | 94 | Utilities |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
30 comments
Hi Ed, can you clarify? On the QVM portfolio is it your intention to be resetting (most of) the portfolio in the New Year, keeping the more recent acquisitions until they have been held for 12 months, or take an altogether more discretionary approach?
Ed, thanks for an excellent report. As to the Rules you are making up as you go I think some time ago you mentioned that you would preclude any stock where there is a dual listing. This made me wonder what your vie w would be on Vodafone which I understand is dual listed being listed in he USA and on the LSE. I believe I have seen Vodafone as an investment in the NAPS portfolio .
Vodafone has its primary listing in the UK, but also trades abroad — for example, it has an ADR (American Depositary Receipt) in the US.
In the NAPS screen, we include all companies with a UK primary listing (like VOD). But we exclude those where the primary listing is abroad and the UK listing is secondary (dual).
Over many years, we’ve found that UK dual-listed shares where the main listing is overseas often face one or more of these problems:
Yes — there are exceptions, and some high-quality overseas companies maintain strong secondary UK listings. But in the small and mid-cap space, “no dual lists” has been a pretty reliable rule of thumb. You might miss the odd gem, but you’ll more often sidestep some very dicey listings.
After years of mucking around I've switched to a largely VM method and am up this year 25% so far. Seems the algorithms are much smarter than I am. Great work Ed.
Hi Ed, do you have a link to a page that outlines what the rules are for working with the QVM? Thanks
Andy - I said in a previous piece that I'm making the rules up as I go along - only part in jest.
Essentially, it's started from the NAPS Portfolio base... but market events come along and jiggle the pack, so the portfolio will end up very different over time. But it will take time to get there.
But here is a rough set of rules being applied:
I will review at year-end whether to continue this experiment editorially. It's really a more active illustration of many of the rules-of-thumb we've researched over the years.
Hi Ed
Just running some screens along those criteria - are you including dual lists or no?
Many thanks
I generally exclude dual listed shares. I prefer primary lists in the UK.
Many thanks for the quick response Ed!
Just one further thought, I am assuming that once you have settled on the list of companies to buy then all position sizes should be equal?
Well - the NAPS has always been equal weighted. There are alternatives, but equal weighting is simple, proven and effective.
In most academic studies too - E/W tends to beat other weighting schemes.
Thanks again Ed, that's pretty much what I am planning to do
Many thanks Ed
There's been significant buying by Brian Marsh at B.P. Marsh & Partners (LON:BPM, taking his concert party over 39%. What are the rules aboyrt the price that PIs would have to be offered if they decide to take it private?
There's been significant buying by Brian Marsh at B.P. Marsh & Partners (LON:BPM, taking his concert party over 39%. What are the rules aboyrt the price that PIs would have to be offered if they decide to take it private?
It's rule 9. A bidder holding over 30% can't bid less than the highest price paid by them in the last twelve months. Which would apply to the concert party in this case.
This can be waived by the Takeover Panel.
timarr
Thanks Tim
B.P. Marsh & Partners (LON:BPM)
i am not convinced Brian Marsh has bought and shares recently - are you sure you are correct in your assumption here FREng?
note then update dated 7th August has tick next to "An event changing the breakdown of voting rights" - the "An acquisition or disposal of voting rights" box is empty.
Company has been buying back shares here so his holding will be going up by him doing nothing.
B.P. Marsh & Partners (LON:BPM) - see RNS announcements today showing BM bought roughly 1% and Wellington increased their holding to 9.5%
B.P. Marsh & Partners (LON:BPM)
sorry cant see anything - i can only see 3 RNS updates today none of which seem to relate to BM.
there is the one dated 7/8 but as i have advised per earlier post it looks very much to me as if his % holding increase was simply down to company buying back wad of shares rather than him buying -any hey ho i could easily be wrong here
what are your specific numbers where his shares increase 1% what is date and have you checked to see if it might be change in % ownership rather than him actually buying shares.
OCN obviously not suitable for this portfolio, but I wonder if the timing of your sale might prove doubly unfortunate? After the merger completes, doesnt the published value of the combined company include OCN's (mainly quite liquid) assets at OCN's NAV of around £20 pr share instead of today's market price?
Yes that's right, the stake in OCN should see an immediate uplift as its valued at NAV rather than share price. Furthermore, the OCN NAV should have seen a decent rise since the last published NAV rise given rise in US equity markets. My rough calculations are that the combined entity will be on a 45-50% discount to the current NAV.
@Shenwood - quite possibly the timing is terrible on the OCN sale. You may be right. It does seem a very anomalous situation.
The interesting thing is that nobody ever challenges a NAPS rollover when normally about 15 or more of 20 stocks get replaced at the year-end.
But when a single share situation comes up like this, it inspires quite a bit more debate!
What a vindication for your methodology! Hope we see more of the same by Autumn Mello so we can see a broad smile on Stocko faces.
Ed - thanks for the update as always. In terms of selling OCN, which was originally added to the portfolio as an Industrial stock, should it not be replaced by a high-ranking Industrial? As at this morning this would be NTBR or MER or 0H3Q, which are all ranked 99.
Currently, I work down the list and select the highest ranked stock regardless of sector, as long as it doesn't break any diversification rules.
At the start of the year, we had a third industrial, (rather than two) , because it was higher ranked than other sector candidates.
I would only automatically select an industrial to replace an outgoing industrial if it took the number of industrials below two.
In this situation, VINO is the highest ranked next stock. It takes the consumer defensive sector count from 2 to 3. And it leaves the industrial sector count at two.
I must admit, I was surprised you didn't take action on OCN within the portfolio sooner. With the sale of the shipping business having gone through, I did wonder what was the point of owning what was now essentially an asset manager. When the reverse Dutch auction was announced, I decided to take it up and as a result sold nearly 80% of my holding at the strike price (1543p), and sold the remaining holding at an effective 1448p after costs, for an overall total return of 26%. I appreciate you use rules to govern the relatively hands-free portfolio, but sometimes perhaps it's necessary to add rules to cope with new situations?
Nevertheless, an overall excellent performance so far, and I'm pleased to be sharing the journey!
Yes, I was a bit flat footed I'm afraid!
Well done on the excellent performance this year. Interestingly I bought Ocean Wilsons Holdings (LON:OCN) this morning - by my rough calculations it's now trading on a 45-50% discount to the combined Hansa/Ocean Wilsons NAV once the merger goes through.
Hansa has traditionally traded on a c.35% discount - I think the historic discount is mainly because of the complexity of their cross holdings and their large stake in the Brazilian shipping company Wilson & Sons. However, they have now sold Wilson & Sons, while HAN and OCN will be combined into a single entity - this will make it a much cleaner, simpler business. In addition, it has reduced fees and committed to buybacks (they will have plenty of cash from the Wilson & Sons sale). The combined entity should also benefit from greater liquidity due to its larger size. Also worth noting that the majority of the investments are now held in listed equites.
Given all this I think the discount could narrow significantly once the merger goes through - just as an illustration, if the discount narrows from 50% to 30% then that's 40% upside, although I suspect the discount could get even lower than this (20-25% would be my guess)
The irony of the situation is I've an instinct that OCN will outperform VINO. But that's my own internal bias - and my internal bias meter is normally haywire. By investing with rules, I am constantly surprised to the upside by things I don't expect, and that outweighs the downside surprises that I often do expect. Though more often than not the downside I do expect doesn't occur!
Agree with this. The decline in Ocean Wilsons Holdings (LON:OCN) is to a certain extent artificial as it is driven by the proposed share for share exchange ratio of the merger. Once the merger goes through this should trade at a similar discount to other IT of that size and a similar mix of listed equities, funds and direct private equity holdings, which is around 20% or so.