Record: £2.2m of performance fees and strong inflows lift our view after two profit warnings

Analyst’s view:
Given two recent profit warnings, I am still wary that they aren't completely out of the woods. However, strong flows into their new Absolute Return Strategy this quarter, combined with a recent high in performance fees, suggest things are getting easier rather than harder. At an 11x forward multiple and with a decent yield (even if it is forecast to be a bit lower this year), I think we can afford to be a bit more generous.
Up 7% to 46.5p - Q2 Trading Update
This seems to be a strong quarter for this currency hedging and investment specialist, with AUM up 7%:
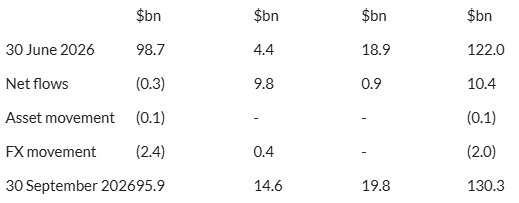
Unlike the Q1 update, which credited Passive Hedging for growth, we don't get any guidance on the relative performance of the low-margin Passive and high-margin Dynamic hedging stratgies.
We may get more insight on this in November's interims. However, I expect no major deviation from recent trends, which show passive products increasing their share of what they call their Risk Management Pillar.
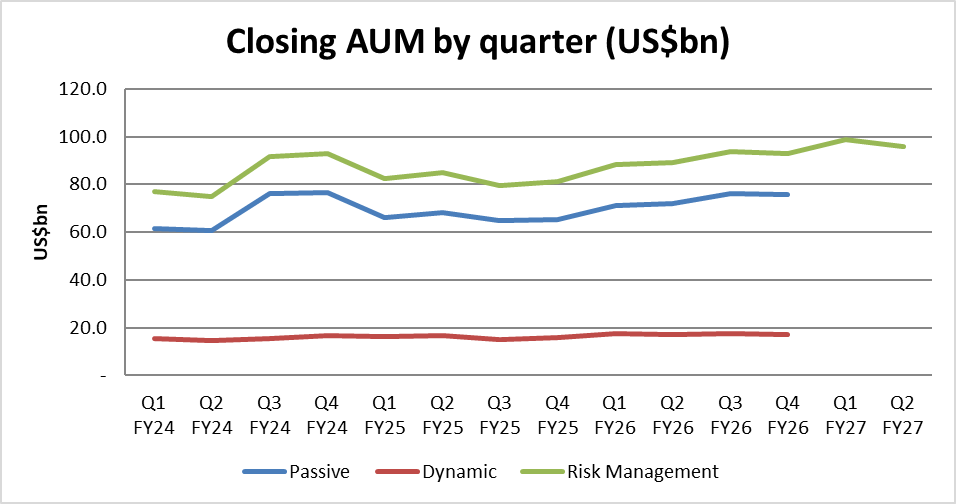
Almost all of the group’s $10.4bn inflows came from the new Absolute Return strategy, not hedging. That pillar’s AUM more than tripled in the quarter, and is starting to make a meaningful contribution to AUM.
Perhaps the most interesting development is the return of performance fees, after they didn't generate any in Q1:
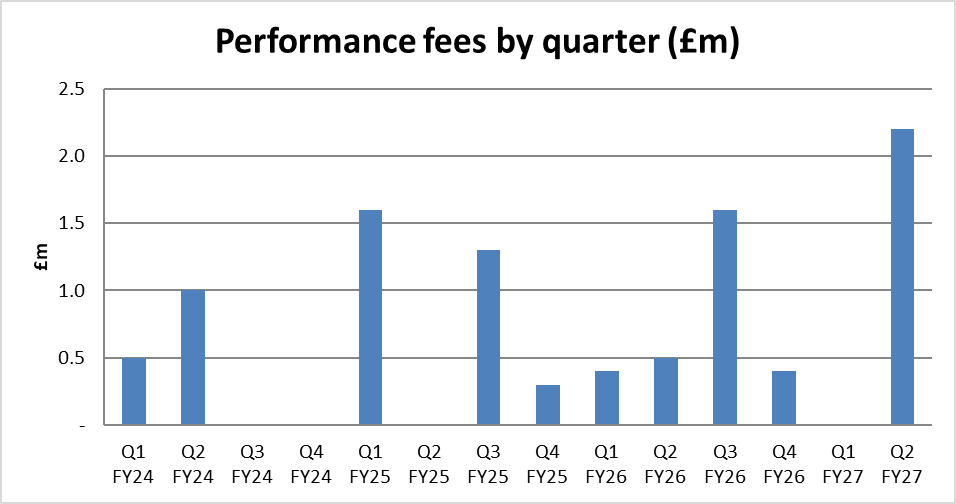
At £2.2m, this is their best quarter in recent times, and is material for a company that has struggled to grow the bottom line recently, and is forecast to deliver just short of £10m PAT for the full year:
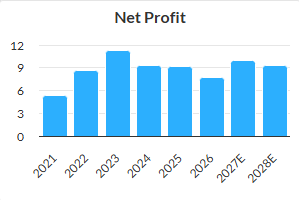
Ultimately, they say "Performance across the Group remains in line with expectations for the full year." Future performance fees, of course, depend on performance through the rest of the year. However, it gives some confidence that the current forecasts may be achievable.
Mark's view
Graham reduced our view on this company to AMBER/RED following a second profits warning in a row earlier this year. I am still wary that they aren't completely out of the woods. However, strong flows into their new Absolute Return Strategy, combined with a recent high in performance fees this quarter, suggest things are getting easier rather than harder.
At an 11x forward multiple and with a decent yield (even if it is forecast to be a bit lower this year), I think we can afford to be a bit more generous. AMBER
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Record (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?