RentGuarantor on track to dramatically reduce valuation multiples as it grows

Analyst’s view:
With the company referring to "claims management" and the "claims ratio" in today's update, and with possibly more than half of applications being accepted, I think it's about time that investors start to think about what happens when something goes wrong - when a guaranteed tenant fails to pay their rent. As this is such a young, fast-growing company, I expect that there's quite a wide range of uncertainty around the performance of the new customers. Investors should therefore bear in mind that some portion of its £12m cash pile - hopefully a very small portion - will be needed to pay out claims. With estimates unchanged today, I'm going to leave our positive stance unchanged. RGG remains on track to dramatically reduce its valuation multiples as it grows.
Down 5% at 96.3p (£163m) - Quarterly Review
This might be the most exciting growth story we've covered all year.
Here are the latest figures from RentGuarantor, "a leading provider of rent guarantee services":
Year-to-date (Jan-Sep) revenue £13m, with £4.5m in September.
Year-to-date adjusted EBITDA £5.85m
Year-to-date adjusted net profit £5.93m
What makes the figures so interesting is that the business had barely started a few years ago.
For the same 9-month period last year, revenue was only £1.7m, and adjusted EBITDA and net profits were negative. The company is within its rights to call this an "exceptional revenue acceleration".
Perhaps the only slight negative is the year-on-year growth in applications: up 208%, compared to a 395% increase in contracts. Doesn't this suggest that the company was less selective this year, compared to last year? The number of contracts was more than half the number of applications, compared to only a third last year.
For now, at least, "the claims ratio remained in line with the Board’s expectations and risk policy."
Cash is strong at £12m by the end of September 2026.
Activities: some interesting activities are announced today, including agreements with Build-to-Rent operators and with King's College London. They have also opened a new office in Bristol that includes a "tech lab", "its dedicated research and development function focused on AI, machine learning and advanced technologies."
CEO comment:
Q3 2026 marked another major step forward in RentGuarantor’s growth and profitability. The combination of accelerating revenue, higher contract volumes and strong earnings demonstrated the effectiveness of the Group’s growth strategy and the operating leverage inherent in our business model...
As we enter the final quarter of the year, our focus remains on converting strong demand into contracted business, maintaining a disciplined approach to claims management, managing costs and cash effectively, and ensuring our operational capabilities continue to scale alongside the growth of the business.
Estimates
Thanks to Shore Capital for covering this one today - they have left estimates unchanged. These estimates include earnings per share of 5.8p this year, 8.2p next year, and 13.6p in 2028.
Graham's view
With the company referring to "claims management" and the "claims ratio" in today's update, and with possibly more than half of applications being accepted, I think it's about time that investors start to think about what happens when something goes wrong - when a guaranteed tenant fails to pay their rent.
As this is such a young, fast-growing company, I expect that there's quite a wide range of uncertainty around the performance of the new customers.
Here's the relevant table from the 2025 annual report, showing how previous cohorts of customers were performing:
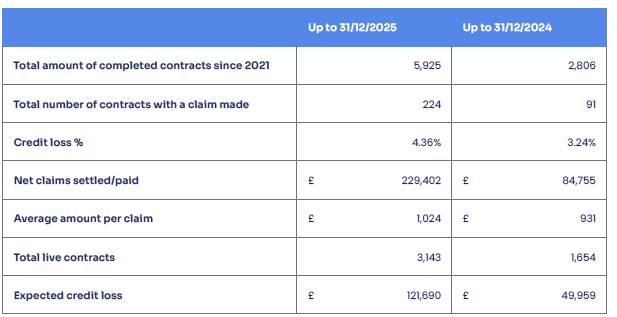
These numbers look small - a credit loss of 3% to 4% - but surely it's reasonable to think that this number is rising? The company says that claims are in line with expectations and with their risk policy, which is not the same as saying that claims are stable!
The provision for expected credit losses at the end of 2025, which was presented within current liabilities on RGG's balance sheet, was merely £120k. This number should be vastly bigger at the end of 2026, thanks to the company's explosive growth.
Where I find reassurance is in the £12m cash balance. But investors should bear in mind that some portion of this cash - hopefully a very small portion - will be needed to pay out claims.
As it's becoming more mature, perhaps we need to start thinking of RGG as a type of insurance company where there are real risks involved, rather than a business that is simply printing profits out of thin air.
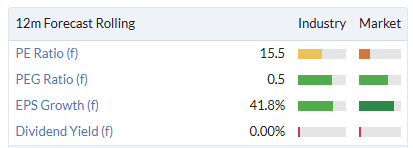
We've been fully positive on this and I'm going to leave that stance unchanged today, with the company on track to dramatically reduce its valuation multiples as it grows.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Rentguarantor Holdings (1)
Comments here are also visible in the Daily Stock Market Report
Graham, from my understanding RentG have their own insurance against such claims rather than using their own cash reserves
Its Propertymark listing says the service and contracts are underwritten by insurance, covering up to 12 months rent or £120,000 per tenancy, whichever comes first
Its NRLA partner page says it is backed by Lloyd‘s of London insurers, and that it manages and pays for the eviction of defaulting tenants
So while increasing claims rates could increase the cost of this insurance going forward I am less concerned than I would be if they were self-insuring. As you can probably guess I am a shareholder in RentG