Retailers riding on the health of the consumer – Part 2

Yesterday, I discussed the robust start to the financial year for the retail sector and also highlighted the significant challenges that the sector is facing. As mentioned, we have a fairly positive view that these challenges will only be short term hurdles, and that the higher quality retail businesses will be able to overcome them.

In today’s instalment, I will discuss the remaining stocks from the list below including the key drivers of their performance. (If you missed Part 1 of this series you can read it here)
And remember, these companies appear in no particular order.
ASX: AX1 Accent Group. QVM StockRank score 91
Distributor and retailer of shoes and leisure wear, AX1 just makes it above 90 on the QVM StockRank table on account the quality of its earnings doing much of the heavy lifting.

AX1 has now put the drop in profitability and margins of the COVID years, behind them. Thus far for the first 18 weeks of FY23, total Group owned sales are up 52% compared to FY22 with margins significantly improving as well. With 50 new stores due to open in 1H23, we expect a return to a growth trajectory.
As another interesting aside Brett Blundy continues to be a significant investor in the firm and recently lifted his holding in AX1 to just below 20% when he made a large on market purchase earlier this year. Such a move has provided confidence to the market.

ASX:UNI Universal Store Holdings. QVM StockRank score 96
Similar to AX1, UNI are a leisure wear fashion retailer that has proven incredibly resilient in the face of rising cost pressures.
Quality earnings underpin this retailer, who only saw sales fall 1.4% last period in the face of COVID lockdowns. This resulted in a fall in profitability and margins. Though pleasingly, it could have been worse, with margins only slightly falling. Cashflow is strong, both ROE and ROC are at high levels relative to peers and the dividend has remained stable with hopes that this will be lifted next year.
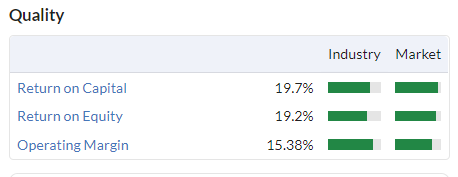
The company is embarking on a strong store rollout plan with 11 new stores opening last year and it has a target of target is 100+ Universal Store sites across Australia / New Zealand (currently they have around 80).
They also recently acquired the THRILLS group of stores completed at the end of October 22 and offers a great opportunity for more growth, particularly in light of the fact that in a recent sales update the company told us they had achieved growth in total group sales of 40.2% to the 20th November, and that excludes the 10 THRILLS stores which have been brought into the portfolio.
This anticipated growth has flowed onto analysts expectations with the recent update bringing to an end an earnings downgrade cycle which had plateaued to July but has since started to improve one more.

UNI is a company with an aggressive omni-channel strategy who feel they will benefit from not only recenet acquisitions and new store rollouts, but also an ongoing ramp-up social occasions to continue to trigger apparel purchases.
ASX:BLX Beacon Lighting. QVM StockRank score 96
Retailer of lights and ceiling fittings, BLX has been a beneficiary of Australia's property boom and for the past few years has maintained a StockRank at, or around 90, on the back of its quality earnings ,

At their recent AGM, the company tried its best to decouple earnings expectations from the Australian property market where there are signs of a slowdown underway. There was quite a bit of time spent on its global expansion plans, including into the US where it expects to achieve solid growth.
While no quantitative guidance was provided on how things are progressing thus far, the company told us they have seen a strong comparative sales period to date compared to pcp. though it expects an eventual easing on the pace of growth once the company starts to cycle through a very strong FY22 post COVID restriction sales. We also suspect the usual pressure points across the sector remain and BLX will not be immune to them.
It really comes down to the continued expansion into the USA, China, Asian and European markets. Analysts appear positive on the company's ability to achieve this raising their earnings expectations on the stock for FY23 over the month since the AGM.

Investors should note the stock only trades o average $100,000 per day so a position in this business needs to be a long-term one. At least the current dividend yield of 4.5% would be enough to keep you interested through the long wait. Of course, there are no guarantees with Dividends. However, BLX continued to pay their dividend even through the COVID uncertainty, showing a strong commitment to it. Even with its big capex plans, there is still a margin of safety at current levels to continue paying ut a similar dividend per share amount moving forward.
ASX: JYC Joyce Corporation. QVM StockRank score 96
JYC is a plumbing and home fittings business. It's one of those classic stocks you find from time to time. Consistent business performance, strong dividend yields, with no dilutive capital raisings.
Since Stockopedia started providing StockRanks it has remained above 80 for the entire period (with the exception of a short blip in 2000)
But as often seems to be the case with tightly held, well run businesses like JYC, they hardly trade!

This makes the stock not a real option for investors. On occasions there are spikes in volume and a sizeable parcel to purchase.
Under normal conditions it can take days for a retail investor to obtain a marketable parcel as there can be wide spreads and limited market depth.

For me it has always one of those stocks I have admired from the sidelines.
ASX:CCV Cash Converters International. QVM StockRank score 97
AS much of our focus has been on a potentially stressed consumer, a potential beneficiary is CCV whose store network is also supported by its financing business (which makes up about half their revenue, but the major amount of their profit) they too have seen an improvement on COVID times.
As a ‘payday’ lender the majority of their clients come from those who have stretched personal balance sheets and require an injection of funding to pay key bills and many other of life’s unexpected events.
During COVID in the face of government support, the business saw a drop off in loan book values. However in the most recent update at the AGM they showed that loan book growth had improved. Most pleasing for them was that medium amount credit contracts (MACC) had risen to a point where they have surpassed small amount credit contracts (SACC). As MACC is for values up to $5,000 (vs SACC which is values to $2,000) these yield a better return. The other pleasing thing is that earnings from the vehicle lending business also continue to grow.

The stock is cheap on most valuation metrics and is why it commands the attention of value investors.

Further it pays a strong dividend of 2 cps fully franked however, most pleasing is that in supporting it, the company returned to positive free cashflow per share this period. Should it continue to do that, then based on the forecasts of the one broker who covers it, a flat dividend in FY23 and FY24, yields above 8% at current prices.
Investors should be aware though that it only trades ~$20k per day and therefore any position in the business needs to be accepting of this fact.
From an outlook perspective, the company feels conditions are ripe for a good period with Christmas ahead. They anticipate continued MACC and vehicle finance loan book growth and a contribution from their new product development, the online ‘PayAdvance’ program.
They also recently purchased the remaining 75% of the NZ Cash Converters Master licence that they didn’t already own (previously 25%). The company says it is ready in the face of rising living costs to “support a large part of the population that many other lenders won’t.”
Some investors may be concerned by the recent tabling in Australian parliament of a Financial Services Reform Bill, potentially impacting the regulation of SACCs. It may come as a surprise that the Company supports a majority of the proposed changes as it sees itself as a highly regulated and compliant participant at the minute anyway, since it applied changes back in 2017 to comply with changing legislation back then.
ASX: TRS The Reject Shop. QVM StockRank score 96
Speaking of a budget conscious consumer, the Reject Shop is also in line to be a beneficiary of rising cost of living pressures leading to increased patronage of its stores.
But TRS has had a tumultuous time of it when earlier this year, then CEO Andre Reich stood down from the position half-way into the company’s five year turn-around plan. Obviously COVID lockdowns impacted the business significantly and it finds its price well below all-time highs.

Now a new CEO has been appointed, investors will hope for a positive vision moving forward driven be a committed team who hope to stand from an improvement in foot traffic, with lockdowns behind us and value on the mind.
The stock is relatively cheap, however investors have discounted it on the operational uncertainty that surrounds it.
As a retailer who targets cheaper offerings, their margins are quite skinny. So one of the major challenges of the new management is keeping a lid on costs to run the business. Not an easy thing to do when wages are rising, as is the costs of doing business more broadly. Their ROE also doesn’t currently excite at 4.7%. It is well and truly down from the heady days of 2010 when it was over 50%.
Investors will be looking for a sales update for guidance as to whether this company can get back on track.
ASX: SUL Super Retail Group. QVM StockRank score 98
Autoparts and outdoor and sporting goods retailer SUL proved resilient during the COVID period attributing revenue growth to a growing online presence and strong inventory management.
However, we all know that we couldn’t leave our countries of residence therefore domestic travel was encouraged which was a boon for SUL who amongst their brands are included Supercheap Auto, rebel, BCF (Boating Camping & Fishing) and Macpac. The latter two experiencing strong cyclical COVID highs. However, as they cycle off irregular highs, the growth exhibited in the Auto divisions as well as the sporting Rebel business has been very pleasing.
In fact, at its latest AGM the company told us that thus far in FY23, sales are up 20% across the group, and it too points to its large active club member base and the resilience of its key auto and sports categories to cope with potential consumer volatility.
This led to a swathe of analysts lifting their earnings expectations for the stock. At the very least for 2023, though they have been somewhat muted for 2024.

Given its obvious qualities, and underpinned by the less than overheated valuation, there is an upside risk that if they are able to defy pundits expectations of an earnings reversion to more ‘normal’ levels and at least hold their own, then this quality retailer may see a further re-rate beyond the one which has occurred since the end of October.
The company will also be hoping for the 30 new stores openings in FY23 to further support growth.
NZE:BGP Briscoe Group. QVM StockRank score 91
BGP is a holding company for retail stores such as Briscoes Homeware, Living & Giving and Rebel Sport, which are located throughout New Zealand.
Like SUL, BGP has seen a strong performance in its sporting goods division, up +33% thus far compared to the corresponding period last year.
The company was upfront in noting that last year’s 3rd quarter was heavily impacted by the Auckland (and other) stores enforced shutdowns from mid-August to early November, meaning they are cycling off what was a very tough time for them.
The company is high quality, generating both strong levels of ROE and ROC. Despite the price pullback over the past 12 months, the stock is trading at fair value relative to the market, but against peers it is at the upper end and investors should be cognisant of this.

In terms of outlook the company says that it remains optimistic of producing a full year of net profit after tax (NPAT) growth above last year’s $87.91 million, however this will depend on economic conditions. And with the recent RBNZ rate hike of 0.75%, it will be interesting to see whether that is successful in curbing inflation and how it impacts spending behaviour. It is probably contributing to the current price weakness.

For Australian investors who are interested, the stock also trades on the ASX under the same code BGP Briscoe Group.
Auto Dealer Stocks
ASX:PWR Peter Warren Automotive Holdings. QVM StockRank score 97
ASX:ASG Autosports. QVM StockRank score 97
ASX:APE Eagers Automotive. QVM StockRank 96
ASX:MTO MotorCycles Holdings. QVM StockRank score 96
NZE:CMO Colonial Motor. QVM Stock Rank score 91
All dealerships have bounced since recent lows in June. Fuelled by order backlogs, created by the global shortage in microchips, second hand sales have done much of the heavy lifting. Each of these businesses is in the enviable position of having a strong order book, coupled with strong current sales.
But, there is evidence that these unique conditions which have been so good for business are starting to cycle off. In a recent presentation ASX:APE included an Order Bank graph which highlighted it, showing the peak buying and backlog period of 2020 has now moderated
However, as the local market expresses a desire to move to EVs, there is a potential re-cycling to occur in the future not seen since lead petrol vehicles were taken off the road. These dealerships potential to play a significant role in that future may see many investors willing to hang around to see what happens.
Also look for potential consolidation as there are pockets of value to be found at the minute.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
1 comment
Please keep it coming