Rightmove doing fine as it delops its own AI-based toolkits

Analyst’s view:
I view this as a very solid update from a company of exceptional quality. Given Rightmove's unique position in the UK property market, I still consider it to be in "value" territory (P/E ratio less than 20x). The company generated £123m of net cash from operating activities in H1 alone, with only minimal investment requirements. So I do not object to them spending cash flow that is not needed for product development on buybacks.
Up 0.9% at 555.4p (£4.0bn) - Trading Statement
[At the time of publication, Graham has a long position in RMV.]
Rightmove has been at the centre of concerns over AI disruption to existing web-based business models, and this has been reflected in its share price over the last two years. The market was spooked by the amount Rightmove planned to spend in order to stay at the leading edge of property search:
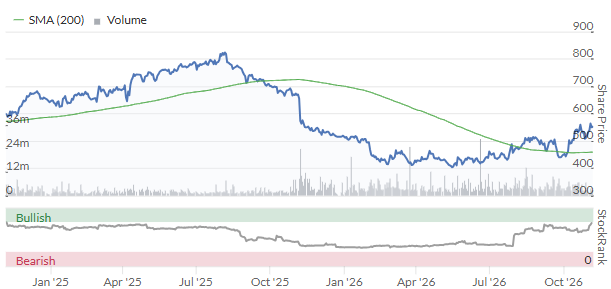
The share price eventually found a floor around 400p, and we've considered it to offer good value this year as a contrarian play. See Roland's coverage in May and my earlier coverage in February.
All of which brings us to today's trading update.
Note that the FTSE is down 1% today, so the small rise in the Rightmove share price is a more significant outperformance than it looks.
Key points:
Revenue and profit growth in line with previous guidance for 2026 (but the ranges have changed)
Upgrading guidance for underlying earnings per share from at least 5% to at least 7%.
Operationally, Rightmove is "delivering our fastest-ever pace of product innovation, with leading solutions for consumers and partners driving increased engagement."
Consensus forecasts suggest revenue growth of about 7% in 2026, and then a similar rate of growth in 2027. They may very slightly miss the consensus revenue forecast (more on that below, in the "outlook" section).
But for a business that was supposedly going to be ruined by AI-based alternatives, I don't believe that growth of about 6-7% is a bad achievement! Especially when we consider that the UK property market is not so healthy:
While near-term revenue growth remains affected by UK end-market headwinds and the interest rate environment, Rightmove continues to grow revenue, profits and free cash flow through strong execution, targeted investments and rigorous cost discipline.
"Ask Rightmove" is Rightmove's answer to 3rd-party AI chatbots: its own experimental AI chatbot, powered by Google Gemini. So far, it appears to be working: "consumers engaging with any aspect of Ask Rightmove have spent over 2x more time on site, saved 3x as many properties and sent over 3x as many leads as those who chose not to use conversational AI."
Market share: Rightmove controls something approaching a natural monopoly, in my view, and its share of consumer time on portals is 90% (source: Comscore) or 76% (source: SimilarWeb). These are stable readings compared with the company's interim report this year.
It's also worth highlighting, as I often do, that Rightmove doesn't have to advertise to get this traffic. It's organic/direct, and today's statement lets us know that less than 1% of traffic originated from LLMs.
Tools for estate agents: Rightmove is always a little controversial in the industry, considering the power it has. But it continues to launch a plethora of new tools for agents. "Rightmove IQ" now offers call transcripts, call summaries and property performance summaries.
Property market conditions: these are tough, and could get tougher in 2027 if mortgage rates rise as expected.
The Bank of England raised rates to 4% yesterday, and Rightmove notes that further base rate rises are priced in for 2027. So affordability could begin to seriously weigh down the property market next year.
House prices have already softened by 0.3% over the past year. Rightmove says that volumes have reduced at estate agents: "buyer demand down 10% and sales agreed 9% lower, as ongoing record stock levels cause some downward pressure on house prices".
Outlook
Rightmove's 2026 revenue growth is within guidance (6-8% growth), but the range is reduced to 6-7%. Fewer new home developments and lower spending by developers are impacting ARPA growth (average revenue per advertiser).
Underlying operating profit growth is expected to be "at least 3%", which is at the lower end of previous guidance for 3-5%.
More positively, the share count has reduced thanks to £95m of buybacks since the end of July, and underlying EPS is expected to grow by at least 7% (previous guidance was at least 5%).
Another £80m of buybacks are expected by year-end.
CEO comment:
This has been a quarter of strong strategic progress, in which we delivered innovation at our fastest-ever pace, compounding on top of our trusted brand and powerful data. After a meaningful step up in capability, we have a well-invested, AI-ready platform. We continue to roll out quality AI solutions to both consumers and partners, leveraging the intelligence layer we create with supply and demand data, and our platform.
Graham's view
I view this as a very solid update from a company of exceptional quality.
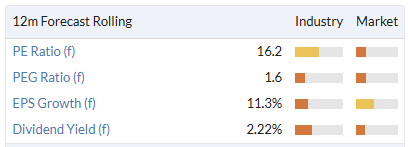
Given its unique position in the UK property market, I still consider it to be in "value" territory with a P/E of less than 20x:
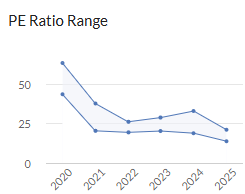
We often debate buybacks in this report. They are often badly-timed and risky. But this is one instance where I am very glad to see the company buying back its own shares. It has paid a much higher price for buybacks in the past:
The company generated £123m of net cash from operating activities in H1 alone, with only minimal investment requirements. So I do not object to them spending cash flow that is not needed for product development on buybacks.
The bears may be right about eventual AI disruption here, but they aren't right just yet.
At the time of publication, Graham has a long position in RMV.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Rightmove (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?