Robert Walters: net fee income grows 1%, but continued losses keep us cautious
Analyst’s view:
NFI shows an improving trend of +1% in Q3 from -4% in Q2. However, their outsourcing arm has done the heavy lifting, rather than the core recruitment busienss. Their ongoing cost-cutting program should help the bottom line eventually, but they remain loss-making in the near term. Net cash continues to decline, and (incl. leases) has declined by £130m since 2020, despite an £85m drop in NWC. This raises some uncomfortable questions as to what happens if/when NFI starts to recover more quickly. This may leave them having to decide between being a permanently smaller business or finding additional sources of funding in order to be able to fund the increased working capital that a growing permanent recruiting business would require.
Up 7% to 139p - Q3 2026 Trading Update
One of the big questions for the sector that I raised when I previewed the recruitement sector in The Week Ahead was whether the decline in Net Fee Income in the sector has now bottomed? And I think there are signs that it mostly has.
Today Robert Walters reports NFI for the third quarter up 1%.
Michael Page (LON:PAGE), which reported yesterday, had NFI up 1.5%, its first growth since Q4 2022. Hays (LON:HAS) NFI declined 3% LFL in their Q1 update on Monday.
However, the recovery is highly dependent on the type of recruitement. Robert Walters only grew NFI because its outsourcing arm saw fees rise 19%. Temporary Recruitment was flat and Permanent continued to decline by 5%.
Hays saw similar trends, with Permanent down 7% LFL and Temp down 1%. Only Michael Page managed to grow NFI here, with Perm up 1% and Temp +3%.
Regionally, for most of them, the UK and Continental Europe are the weak spots, with the US and APAC doing better.
Interestingly, for Robert Walters, the UK is a bright spot with NFI up 14% in Specialist Recruitment, and showing strength in permanent positions.
Profitability:
Hays didn't give any specific FY27 profit guidance, only mentioning their desire to achieve medium-term targets. With the shares trading at 30x forward earnings, you can see why the market may have been put off by this update, and the shares dropped 13% on Monday.
The Michael Page share price was largely flat yesterday, as they slightly increased their 2026 operating profit guidance to £29m (from £28m). However, this still puts them on a P/E above 30x.
So far, the market appears to have liked the Robert Walters update, as they have shifted from guiding “towards the upper end” in July to "at least in line with expectations". However, a quick check of the footnotes reveals that:
Current company-compiled consensus for 2026, being the mean average of three analyst estimates, is an operating loss of £(8.3)m.
Trumpeting an improvement in expectations, when those are still for large losses, and competitors are profitable, seems a bit like a company excited about a H&S improvement because fewer employees have been killed!
Cost-cutting:
In the current environment, it is perhaps unsurprising that any recovery in sector profitablity has largely been driven by restructuring rather than better NFI performance. I certainly appreciate the irony that all the major recruiters are firing staff.
Michael Page continued to reduce fee-earner headcount, Hays is exploring options for seven countries, and Robert Walters has its own review under way. It seems that the pace of firings will now moderate with them saying:
The Group considers existing fee earner headcount levels to be broadly appropriate overall, but will remain agile in positioning the business based on market conditions and fee earner productivity levels.
Balance sheet:
The bigger issue I see is that, while cost-cutting is the right thing long-term, the immediate cash cost still hits the company finances. Ongoing losses continue to hit the company's cash balance:
Net cash of c.£13m as at 30 September 2026 (30 June 2026: £17.2m). The Board continues to expect net cash at the end of 2026 to be stable versus the 2025 year-end position.
One of the problems with this measure is that it excludes lease liabilities. The StockReport includes leases and calculates a £42m net debt position:
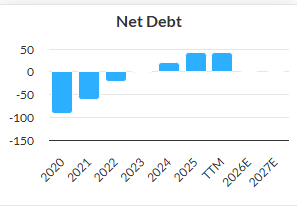
We've seen £130m increase in net debt since 2020, including leases, which seems a huge shift in the state of their finances. Some of this appears to be due to paying an uncovered dividend in FY24, and there was a buyback in place from August 2022 to October 2023. However, given that the share price ranged from around £4-5 at that time, they apper to hav destroyed a huge amount of shareholder value with it!
I also have some big doubts around their ability to rebuild net cash (excl. leases) back up to the £26.2m level it was at FY25 year-end.
The half-year results showed a £4.5m operating loss, so based on current guidance we'd see at least a £3.5m operating loss in H2. Interest paid and principal paid on lease liabilities are likely to be at similar levels to H1, offsetting D&A.
This means they need to generate somewhere between £13-16m out of net working capital in Q4 to hit that figure. At the half-year, we had already seen NWC drop down to £35m:
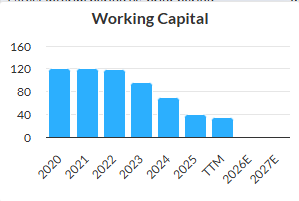
While it is not inconceivable that periods of very weak trading lead to strong working capital in flows, the problems come when trading recovers.
The market appears to have priced in a strong recovery in NFI already, but if they were ever to return to 2021/2022 levels they would likely need another £100m of working capital to fund it. They seem to recognise this with an additional £20m of financing facilities secured in this quarter.
I can't see this being enough, though. Given the current balance sheet, I think they will need to either accept being a permanently smaller business going forward or secure additional funding.
This doesn't mean that there isn't a wider sector recovery play here, just that I think it will be hard for them to ever return to previous highs of trading or market cap.
Mark's View
While the return to growth in NFI is welcome, it is driven by their outsouring arm rather than growth in overall permanent recruitment. Still there are signs that things are bottoming for NFI accross the sector.
On top of this we have cost-cutting and headcount reductions across all the major recruiters, which should bear fruit at the bottom line eventually.
The problem with Robert Walters is that, despite these trends, H2 is forecast to be at least a £3.5m operating loss, and their once high net cash balance has been eroded by losses and one off cash costs associated with the cost savings.
Net cash/debt (incl. leases) since 2020 has declined by £130m despite net working capital dropping by £85m. They are guiding net cash to recover into the year-end, but with trading losses, that can only mean a further stretching of working capital.
I think there is a real risk that the company face a difficult choice of being a permanently smaller business, or requiring additional financing as markets recover. As such, the recent share price strength looks a little premature to me.
Roland considered this AMBER/RED at 99p in July when they released their Q2 trading update. With the share price now almost 40% higher, I'm just not sure that a shift of NFI being down 4% in Q2 to being +1% in Q3, while the company continues to be loss making is enough to change our view.
It is worth noting that the Stock Rank disagrees with me. As the algortithm's now rate it a Super Stock. However, the only substantive change appears to be in the Momentum rank, which has gone from 18 to 92. However, changes like this, which are entirely driven by increases in share price, tend to be far riskier than those backed by improving fundamentals in my experience. Those who bought in on the short-term momentum may want to watch carefully for any sign of mean reversion.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Robert Walters (1)
Comments here are also visible in the Daily Stock Market Report
The TU from Robert Walters (LON:RWA) is likely to be of interest to others besides myself. It confirms what is already in the price - the tide for recruitment agencies has turned everywhere outside Europe. In Europe prospects remain poor. It confirms that existing expectations of a full year operating loss of £8 million or thereabouts still hold. It is possible that that is reassuring.