Daily Stock Market Report (Wed 14th Oct 2026) - VTU, SCT, RWA(HAYS,PAGE), JHD, CNS, ASHM

The price of oil is up for the fourth day in a row after the Houthis from Yemen managed to hit Saudi Aramco’s headquarters in Dhahran, Saudi Arabia.
Yemen has a very complicated political situation: the (Iran-backed) Houthis have control over the majority of the population, while the (Saudi-backed) internationally recognised government controls the majority of its land mass.
The civil war between the two sides was reignited this summer after Saudi Arabia attacked the airport in Yemen’s capital.
If the conflict between the US and Iran was not enough, the Red Sea has now suddenly become another main stage for geopolitical uncertainty.
Overnight market movements:
The FTSE is up 0.2% at 10,665
S&P 500 is unchanged at 7,810
Brent crude (December) is up 0.7% at $106.40/bbl
Gold is down 0.3% at $4,145oz
Bitcoin is unchanged at $83,300
Mark Simpson joins me today.
All done for today, cheers! Spreadsheet accompanying this report: link.
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Rio Tinto (LON:RIO) (£114bn | SR85) | ~1% YTD increase in copper equivalent production, driven by growth from Oyu Tolgoi copper and Pilbara iron ore. Oyu Tolgoi copper production increased 29% year-to-date. Production/sales guidance is maintained. Unit cost guidance is maintained. | ||
Softcat (LON:SCT) (£4.15bn | SR68) | Gross profit +24.7%. Underlying operating profit +19.4% (£215.1m). Outlook: “Looking ahead, and excluding the contribution from GDT, business momentum remains strong and the Board expects to deliver high single-digit underlying operating profit growth in FY2027, slightly ahead of gross profit growth”. | AMBER = (Graham) | |
Ashmore (LON:ASHM) (£1.61bn | SR58) | Q1 (to September). Net inflows $1.1 billion. AUM increased from $54 billion to $54.5 billion. Typical commentary that customers need to increase their emerging market allocations: "Positive net inflow momentum has continued during the quarter, with Ashmore again delivering broad-based net inflows across both fixed income and equities, reflecting the increasing recognition of the relative attractiveness of EM and Ashmore's ability to deliver outperformance together with an acknowledgement that EM allocations need to increase." | GREEN = (Graham) [no section below] | |
Chemring (LON:CHG) (£1.36bn | SR33) | Multi-year strategic partnering agreement with a major US Prime Contractor for the supply of its COTS Nav-Sync Miniature Radar Altimeter product. Worth at least $170m over the first five years. Expected to extend to at least 2035. | GN note: no reference to any impact on market expectations. | |
Great Portland Estates (LON:GPE) (£1.26bn | SR32) | “Another strong leasing performance.” Renewals were 4.1% ahead of estimated rental value in the first half. “...with high quality space increasingly scarce across our core central London markets, we are well positioned to maintain this momentum.” | ||
Discoverie (LON:DSCV) (£857m | SR67) | H1 sales up 8% organically. Orders up 22% organically and up 30% at constant exchange rates. “The positive outlook continues with full year adjusted earnings running ahead of the Board's expectations and driving strong earnings growth over last year.” | ||
James Halstead (LON:JHD) (£554m | SR80) | Revenue £259.9m (2025: £262m). PBT £48.2m (2025: £55.1m). “Short term ongoing headwinds in Europe (particularly the UK) are affecting repair, renewal and roll-out budgets that have been constrained by additional employment costs in education, healthcare and hospitality sectors… The Board remains confident in the Group’s prospects…” | AMBER/GREEN = (Graham) | |
Porvair (LON:PRV) (£422m | SR77) | “Continued to trade well with a strong start to the final quarter… The Board expects trading to be slightly ahead of full-year market expectations, supported by a diversified customer base, strong recurring revenue streams and disciplined operational management.” | ||
Tatton Asset Management (LON:TAM) (£419m | SR70) | Interim results are in line with Board expectations. AUM up 15% to £26.2 billion. Average net inflows lower than guidance range. Expectations for the full year remain unchanged. | ||
Ferrexpo (LON:FXPO) (£321m | SR68) | “Tight liquidity, constrained logistics capacity, and the temporary suspension of production resulted in lower production levels in the quarter, totalling 780 thousand tonnes in the third quarter, lower than the 963 thousand tonnes in the second quarter.” The $100m fundraise “has allowed us to restart production activities, albeit at significantly lower capacity than before the full-scale invasion”. | ||
Petrotal (LON:PTAL) (£283m | SR95) | Group production averaged 11,797 barrels of oil per day in Q3 2026, and 13,076 bopd YTD, 3% ahead of internal budget expectations. | ||
Vertu Motors (LON:VTU) (£252m | SR96) | Revenue +3.4% to £2.597bn, Adj. PBT+19% to £23.8m, NTAV/share 80.8p (28 Feb: 75.9p). Net debt£54.2m (28 Feb: £78.3m) substantially below expectations. | AMBER = (Mark) | |
Kistos Holdings (LON:KIST) (£252m | SR95) | Signed a Sales and Purchase Agreement with Vår Energi to acquire a 10% working interest in the production licenses PL 169E, PL 956 and PL 956B on the Norwegian Continental Shelf for $12.9m. | ||
Brooks Macdonald (LON:BRK) (£241m | SR60) | Q1 net inflows of £54m, BPS net outflows of £53m. Total FUMA +0.5% at £21.8bn. (Performance contributed £0.2 billion of Q1 FUM growth.) | ||
Galantas Gold (LON:GAL) (£200m | SR24) | High-grade gold-copper in new structures outside the current MRE, including 1.48 m at 11.84 g/t | ||
Xaar (LON:XAR) (£117m | SR52) | Appointment of Daniel Dayan as Chair with immediate effect. Ben Stocks will step down as Chair at the same time. | ||
Robert Walters (LON:RWA) (£94.1m | SR92) | Q3 NFI +1% (Specialist recruitment -2%, Recruitment outsourcing +19%). Net Cash excl. Leases £13m (30 Sep: £17.2m). | AMBER/RED = (Mark) | |
Audioboom (LON:BOOM) (£91.9m | SR12) | Q3 Revenue +17% to $23.8m, Adj. EBITDA +89% to $2.2m (ahead of current market expectations). Now expects Adj. EBITDA at least $7.7m for the FY. Cash $6.7m (30 Jun: $5.4m). | ||
Corero Network Security (LON:CNS) (£61.5m | SR47) | SP +21% | AMBER/GREEN ↑ (Graham) [no section below] | |
Zephyr Energy (LON:ZPHR) (£58.8m | SR32) | Successful acquisition at auction of 5,692 acres under U.S. federal leases in Utah. | ||
DP Poland (LON:DPP) (£58.1m | SR27) | Q3 Poland total system sales increased +10.4% to PLN76.8m (+14.4% YTD) LFL -7.2% in Q3 and -2.0% YTD. | ||
Orosur Mining (LON:OMI) (£56.4m | SR5) | First hole at El Cedro continues to show consistent gold mineralisation from surface and remains open at depth incl. 46.4m at 1g/t gold. | ||
Helium One Global (LON:HE1) (£39.6m | SR22) | Helium One Global Ld - Placing to Raise £3 million and Project Updates | £3m gross raised at 0.29p, a 26% discount to last night’s close. | |
Predator Oil & Gas Holdings (LON:PRD) (£25.8m | SR15) | MOU-6 drilling operations to 950 metres successfully completed. Wireline logs have been acquired. Test operations to commence shortly. | ||
Metals One (LON:MET1) (£15m | SR16) | Strategic Project designation has not been granted by the EU. | ||
Angus Energy (LON:ANGS) (£14.8m | SR35) | Rig secured for the planned BRX4Z workover at the Brockham Oil Field, in which Angus holds an 80% interest and is the operator, with mobilisation expected in early November 2026. | ||
Cirata (LON:CRTA) (£12.5m | SR7) | Q3 Billings $1.3m, Cash $6.2m after $7.3m placing in period. FY26 outlook unchanged (following profits warning in Sep.) | ||
Lexington Gold (LON:LEX) (£11.1m | SR9) | South African Department of Mineral and Petroleum Resources has granted the renewal applications in respect of two significant Prospecting Rights forming part of the Company’s Kroonstad Gold Project in the Free State Province of South Africa, following the successful conclusion of a longstanding appeals process. | ||
Cellbxhealth (LON:CLBX) (£10.5m | SR4) | $65k SOW under existing MSA with US-based pharmaceutical company to process c.100 patient samples using the Company’s proprietary Parsortix® platform to isolate and harvest CTCs for downstream molecular analysis, including mRNA analysis. |
Mark's Section
Vertu Motors (LON:VTU)
Up 3% at 84p (£252m) - Interim Results - Mark - AMBER =
The headlines here are all heading in the right direction with revenue, cash generation and PBT up, plus net debt down:
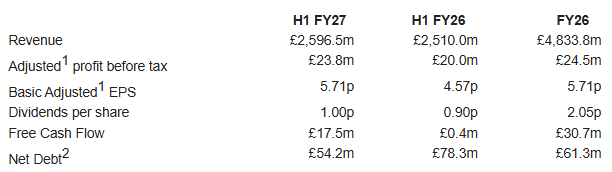
Shareholders are rewarded by a 11% increased interim dividend.
This is also another upgrade:
Full year results for the year ending 28 February 2027 are anticipated to be ahead of current expectations.
Momentum is clearly behind them as their AGM trading update in June also said they would be ahead of expectations. However, the broker upgrades at the time were relatively slight; Shore raised their EPS forecasts from 5.7p to 5.9p. Today, that jumps to 6.6p, a much more impressive 12% upgrade to the bottom line.
The problem is that this comes in a context of a huge downgrade earlier in the year:
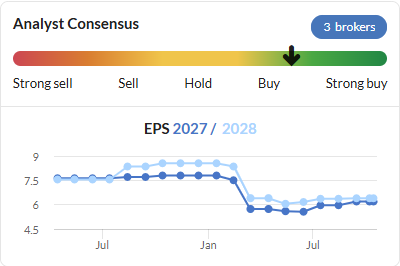
FY27 EPS estimates are still some 10% below where they started the year.
For FY28, Shore don't make any changes, which means their 6.4p is 30% below the 9.1p they had in at the start of the year. Yet the share price is around 33% higher than back then. This means that the FY28 earnings multiple is close to double what it was.
This can be seen in the P/E ranges, which are much higher than recent times:
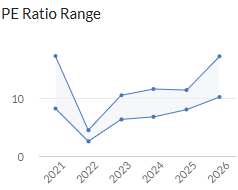
Of course, given recent upgrades to FY27 numbers, investors may be expecting that momentum to continue into FY28.
Historically, the company has been under-represented in the Chinese brands that have seen the biggest sales growth in the UK. The company appears to have responded to this, though:
The Group continues to reshape its portfolio to capture attractive growth opportunities, including automotive brands from China. We now have 20 Chinese automotive outlets, with more on the way.
It seems a further 11 Chinese brand outlets are planned in the next 9 months. However, it would need some pretty big upgrades to look like good value compared to normal multiple ranges.
Balance sheet:
Things look better on this front. Despite some further working capital outflows, they generated £32.5m of cash from operating activities, up from £16m in H1 last year. With lower net capex at £5.3m, and £10.9m of lease principal payments, this means free cash flow was £16.3m versus an outflow in H1 last year.
This cash flow has been directed towards £3.5m of dividends, £5.7m of share repurchases, and still allowed a reduction in net debt (excl. leases) of £54.2m, which they say is lower than expected.
The interim dividend is raised by 11% to 1.0p. However, it is worth noting that the payout hasn't risen as fast as the share price and the 2.5% forecast yield is below the typical range for the company, following a cut in FY25:
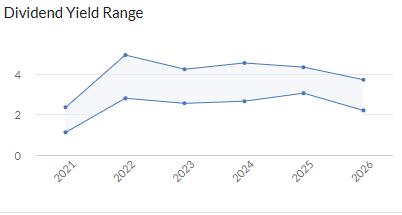
Part of this is a preference for buybacks over dividends:
The Group continues to repurchase its own shares as part of its Share Buyback programme. To date, 21.9% of the share capital of the Group has been repurchased since the commencement of the programme in 2018. £10.2m remains of the £12m buyback announced on 5 March 2026 and the Company will purchase shares up to 85p.
It is interesting that they have been so slow to buy back their own stock and also that they put a specific figure on the price they are willing to pay. It is tempting to think that this may put a floor on the share price in the near term. However, they have historically not given the broker a mandate to buy stock in close periods, so this isn't a given.
Part of their confidence in buying back their own stock is the strong asset backing of the shares. They report a further increase today:
Tangible net assets per share of 80.8p (28 February 2026: 75.9p) a new record level
Their calculation appears to include an IAS19 pension surplus, which would not necessarily be a surplus on more cautious Triennial assumptions, nor whether it will ever be accessible by the company if it is in surplus. This takes 1.1p/share off these numbers, but is obviously not particularly material to the investment case.
This means that the company still trades at a very modest premium to TBV where the vast majority of those assets are freehold property. However, that also raises questions about how productive those assets are.
In the Annual Report, freehold and long-leasehold property made up around 92% of PP&E, which would make it around £323m at the half-year, based on a similar proportion.
Freehold land isn’t depreciated, and freehold buildings are depreciated at 2% a year. If we guess that the split here is roughly 50-50, then this is a 1% charge to the P&L.
Lease yields on these types of properties are around 7%. So the P&L charge would go up by around 6% pa if they sold and leased back all of these. This would be an additional £19.4m charge.
This is 2/3rds of the company's ongoing PBT. So it would be possible for the company to split into a PropCo and an OpCo and return the vast majority of the current share price to shareholders, say 75p after costs. However, the remaining OpCo on a typical 9xP/E would only be worth an additional 20p or so, giving a 95p total valuation. This is above the current mid-80s share price, but perhaps not enough to make it obviously good value.
Mark's view
While everything in this report is heading in the right direction, and we have the second FY upgrade, this still leaves forecasts below where they started the year. It is difficult to feel there is further significnat upside in a stock where the FY28E earnings multiple has already doubled over the last 9 months.
That said, there does appear to be a modest undervaluation based on the scale of the freehold assets, and Tangible Book Value per share continues to grow. These assets limit the downside, and that may be an attractive quality to many investors. However, the upside from here also looks quite limited unless we see some very material upgrades in the, as yet unchanged, FY28 forecasts. In light of this, I am happy to keep our neutral view for the moment. AMBER
Robert Walters (LON:RWA)
Up 7% to 139p - Q3 2026 Trading Update - Mark - AMBER/RED =
One of the big questions for the sector that I raised when I previewed the recruitement sector in The Week Ahead was whether the decline in Net Fee Income in the sector has now bottomed? And I think there are signs that it mostly has.
Today Robert Walters reports NFI for the third quarter up 1%.
Michael Page (LON:PAGE), which reported yesterday, had NFI up 1.5%, its first growth since Q4 2022. Hays (LON:HAS) NFI declined 3% LFL in their Q1 update on Monday.
However, the recovery is highly dependent on the type of recruitement. Robert Walters only grew NFI because its outsourcing arm saw fees rise 19%. Temporary Recruitment was flat and Permanent continued to decline by 5%.
Hays saw similar trends, with Permanent down 7% LFL and Temp down 1%. Only Michael Page managed to grow NFI here, with Perm up 1% and Temp +3%.
Regionally, for most of them, the UK and Continental Europe are the weak spots, with the US and APAC doing better.
Interestingly, for Robert Walters, the UK is a bright spot with NFI up 14% in Specialist Recruitment, and showing strength in permanent positions.
Profitability:
Hays didn't give any specific FY27 profit guidance, only mentioning their desire to achieve medium-term targets. With the shares trading at 30x forward earnings, you can see why the market may have been put off by this update, and the shares dropped 13% on Monday.
The Michael Page share price was largely flat yesterday, as they slightly increased their 2026 operating profit guidance to £29m (from £28m). However, this still puts them on a P/E above 30x.
So far, the market appears to have liked the Robert Walters update, as they have shifted from guiding “towards the upper end” in July to "at least in line with expectations". However, a quick check of the footnotes reveals that:
Current company-compiled consensus for 2026, being the mean average of three analyst estimates, is an operating loss of £(8.3)m.
Trumpeting an improvement in expectations, when those are still for large losses, and competitors are profitable, seems a bit like a company excited about a H&S improvement because fewer employees have been killed!
Cost-cutting:
In the current environment, it is perhaps unsurprising that any recovery in sector profitablity has largely been driven by restructuring rather than better NFI performance. I certainly appreciate the irony that all the major recruiters are firing staff.
Michael Page continued to reduce fee-earner headcount, Hays is exploring options for seven countries, and Robert Walters has its own review under way. It seems that the pace of firings will now moderate with them saying:
The Group considers existing fee earner headcount levels to be broadly appropriate overall, but will remain agile in positioning the business based on market conditions and fee earner productivity levels.
Balance sheet:
The bigger issue I see is that, while cost-cutting is the right thing long-term, the immediate cash cost still hits the company finances. Ongoing losses continue to hit the company's cash balance:
Net cash of c.£13m as at 30 September 2026 (30 June 2026: £17.2m). The Board continues to expect net cash at the end of 2026 to be stable versus the 2025 year-end position.
One of the problems with this measure is that it excludes lease liabilities. The StockReport includes leases and calculates a £42m net debt position:
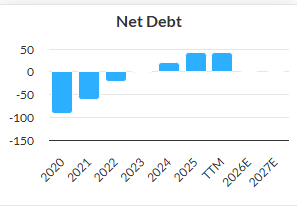
We've seen £130m increase in net debt since 2020, including leases, which seems a huge shift in the state of their finances. Some of this appears to be due to paying an uncovered dividend in FY24, and there was a buyback in place from August 2022 to October 2023. However, given that the share price ranged from around £4-5 at that time, they apper to hav destroyed a huge amount of shareholder value with it!
I also have some big doubts around their ability to rebuild net cash (excl. leases) back up to the £26.2m level it was at FY25 year-end.
The half-year results showed a £4.5m operating loss, so based on current guidance we'd see at least a £3.5m operating loss in H2. Interest paid and principal paid on lease liabilities are likely to be at similar levels to H1, offsetting D&A.
This means they need to generate somewhere between £13-16m out of net working capital in Q4 to hit that figure. At the half-year, we had already seen NWC drop down to £35m:
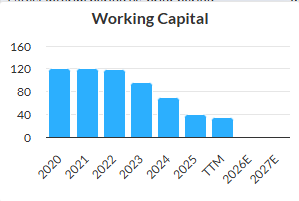
While it is not inconceivable that periods of very weak trading lead to strong working capital in flows, the problems come when trading recovers.
The market appears to have priced in a strong recovery in NFI already, but if they were ever to return to 2021/2022 levels they would likely need another £100m of working capital to fund it. They seem to recognise this with an additional £20m of financing facilities secured in this quarter.
I can't see this being enough, though. Given the current balance sheet, I think they will need to either accept being a permanently smaller business going forward or secure additional funding.
This doesn't mean that there isn't a wider sector recovery play here, just that I think it will be hard for them to ever return to previous highs of trading or market cap.
Mark's View
While the return to growth in NFI is welcome, it is driven by their outsouring arm rather than growth in overall permanent recruitment. Still there are signs that things are bottoming for NFI accross the sector.
On top of this we have cost-cutting and headcount reductions across all the major recruiters, which should bear fruit at the bottom line eventually.
The problem with Robert Walters is that, despite these trends, H2 is forecast to be at least a £3.5m operating loss, and their once high net cash balance has been eroded by losses and one off cash costs associated with the cost savings.
Net cash/debt (incl. leases) since 2020 has declined by £130m despite net working capital dropping by £85m. They are guiding net cash to recover into the year-end, but with trading losses, that can only mean a further stretching of working capital.
I think there is a real risk that the company face a difficult choice of being a permanently smaller business, or requiring additional financing as markets recover. As such, the recent share price strength looks a little premature to me.
Roland considered this AMBER/RED at 99p in July when they released their Q2 trading update. With the share price now almost 40% higher, I'm just not sure that a shift of NFI being down 4% in Q2 to being +1% in Q3, while the company continues to be loss making is enough to change our view.
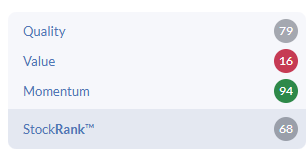
It is worth noting that the Stock Rank disagrees with me. As the algortithm's now rate it a Super Stock. However, the only substantive change appears to be in the Momentum rank, which has gone from 18 to 92. However, changes like this, which are entirely driven by increases in share price, tend to be far riskier than those backed by improving fundamentals in my experience. Those who bought in on the short-term momentum may want to watch carefully for any sign of mean reversion.
Graham's Section
Softcat (LON:SCT)
Down 7% at £17.93 (£3.9bn) - Preliminary Results - Graham - AMBER =
Softcat is "a leading UK provider of IT infrastructure products and services", i.e. rather similar to Computacenter (LON:CCC).
Last month, I looked at Softcat's acquisition of GDT, a Texas-based IT company, for £785 million.
Through the use of some rather tortured back-of-the-envelope calculations, I estimated that GDT was expected to deliver in the region of £40-45m of after-tax profits in its first full financial year under Softcat ownership.
GDT's contribution to earnings per share would be offset by a higher interest bill and a higher share count, as Softcat both borrowed and raised equity in order to fund the deal.
Let's quickly review these full-years which are before the acquisition of GDT:
Gross invoiced income +30.5% (£4.7bn)
Gross profit +24.7% (£616m)
Underlying operating profit +19.4% (£215m)
So far, so good. These results are "significantly ahead of our expectations at the start of the year". This chart shows how EPS forecasts evolved:
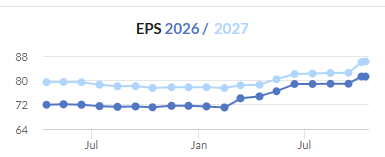
The total dividend for the year is increased by 7.5% to 31.5p, but there is no special dividend as there was last year (which makes sense considering the need to fund the acquisition!)
Net cash finished just shy of £200m.
Outlook:
Outlook: Looking ahead, and excluding the contribution from GDT, business momentum remains strong and the Board expects to deliver high single-digit underlying operating profit growth in FY2027, slightly ahead of gross profit growth following very strong two-year growth across FY2025 and FY2026.
After gross profit growth of 18% in FY25 and then nearly 25% in FY26 (mostly organic), it would be greedy to expect these growth rates to continue for very long.
So we'll have a softening of organic growth in FY27, but this will be combined with GDT's contribution.
CEO comment:
AI is one of several factors making IT infrastructure more critical, complex and strategically important for our customers’ operations....
Post year-end, we announced the acquisition of GDT, a leading US-based multi-vendor IT solutions provider. This is a significant strategic step for Softcat, giving us enhanced capability in the US and strengthening our ability to serve customers with international requirements. GDT will strengthen our foundations for long-term growth, alongside and in combination with, our existing UK and Ireland business. We are very encouraged by how well received the transaction has been by customers, vendors and employees alike.
Estimates: this is covered by 14 brokers and the latest consensus estimate is for EPS of 86p in FY July 2027, rising to nearly 100p in FY July 2028 (including GDT's contribution).
In September, I pencilled in 101p of EPS in FY28, so it looks like I may have been pretty close.
That puts the shares on a P/E multiple of 18x for FY28 - the financial year starting nearly a year from now.
Graham's view
I was neutral on this on valuation grounds last time, and I'm going to leave that unchanged today.
An earnings multiple of 18x would be pretty high, in my view, even if it was based on current-year earnings and even if the company had a net cash position.
However, that's based on next year's earnings. And the company is going to be carrying substantial debts for the next few years: nothing that would make me concerned for its safety, but enough to impact how much I'd be willing to pay for the equity.
I'd also point out that after a few years of very strong organic growth, the market may have been lulled into a false confidence here. With organic growth about to fall to a more sustainable level, investors may wish to reassess this one - with the shares down 6% today, they may already be doing so. This is especially true if any air comes out of the AI bubble.
In summary: I think Softcat is a fine business, but I also think that the market may be overvaluing it here.
The StockRanks consider it to be a High Flyer. In general that is a winning style, but it's also highly vulnerable to changes in Momentum.
James Halstead (LON:JHD)
Up 3% at 131.8p (£549m) - Preliminary Results - Graham - AMBER/GREEN =
James Halstead plc, the AIM listed manufacturer and international distributor of commercial flooring, announces its results for the year ended 30 June 2026:
This family-controlled business has announced its "50th year of increased dividend" - a rare achievement indeed.
As noted by Roland (e.g. here and here, and he owned shares in JHD on both occasions), the company's recent growth numbers aren't great.
Today's FY June 2026 results were already previewed in a prior trading update, but let's take a look:
Revenues eases back from £262m to £259.9m
PBT falls 12.5% to £48.2m
Earnings per share 8.5p (2025: 9.7p)
The total dividend for the year is 8.95p, slightly higher than last year. Unlike last year, it is not covered by earnings.
The company acknowledges this:
Our dividend cover in this year fell below 1 for the first time. However, the year saw several headwinds that took profit lower than the prior year. Notwithstanding dividend cover being reduced our cash inflows were very good and the final dividend payout is well within our cash resources.
The company's cash position finished the year at £75.9m, assisted by inventories falling by a few million pounds. So that cash pile can certainly help to subsidise the dividend for a while, as alluded to by the company.
I'm no expert when it comes to the manufacture of commercial flooring, so let's let the Chairman to the talking. Here are the market conditions in the UK:
The background is simple to describe: our core markets have seen a fall in new build activity and more importantly reductions in the quantum and regularity of repair and renewal activity. For the UK, education, healthcare and prison sector budgets for flooring have been much reduced due to increased spending elsewhere. Allied with this, hospitality has come under pressure, both new outlets and repair and renewal work, in part because of the degree of uncertainty/confidence across the sector but more immediately due to increased costs particularly on wages but compounded by energy and other material costs.
It's hard to find any bright spots here and poor conditions are compounded by the collapse of Headlam, which was "an important customer for many years". Hopefully the slack will be picked up by Likewise (LON:LIKE)?
The UK is responsible for 43% of JHD's turnover and has been a key focus, given the difficult conditions mentioned above - the result has been a very slight increase in UK revenue, despite the wider market shrinking.
Gross margins were about flat at 44.5%.
Outlook:
The ongoing concerns over energy costs and the upward cost pressure on other materials locally and in relation to global supply chains are key short term matters to contend with. Every year has its issues that need focus, experience and solutions but as in years past we formulate resolutions to the best of our abilities.
Graham's view
This type of stock isn't really in my wheelhouse but I understand that family-owned and family-managed businesses carry strong appeal. Chairman Mark Halstead owns 6% of the business, the "John Halstead Settlement" owns another 17%, and there are other family members on the register in addition to these.
CEO Gordon Oliver informs us that sales prices have increased at the start of FY2027 - so despite whatever poor visibility the company may suffer from, we should at least be able to expect gross margins to hold up. Roland previously explained that JHD had refrained from raising prices, and absorbed the higher input costs relating to the Iran conflict.
I have no balance sheet concerns: there is tangible equity of £180m and as we discussed previously, a very high cash balance. I do expect this cash balance to come under pressure from the dividend and perhaps also from inventories rebuilding.
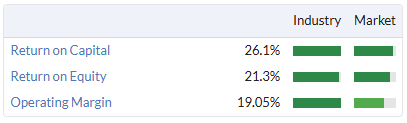
Return on equity is very strong at 19% and that's despite having a rather "inefficient" balance sheet. I'm genuinely surprised that a flooring manufacturer can achieve this - suggesting to me that the company benefits from very clever management, highly differentiated products, or both.
The StockReport confirms high ROE, with 21% for last year:
So yes, I can see the attractions here. And I'm going to leave Roland's moderately positive stance untouched.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
I am a bot,
All the best
Hi Graham, I note Thor Explorations (LON:THX) Q3 results released today weren't mentioned on the report at all? As the last discussion was around a year ago will you be looking at this one?
I don't cover the sector but I will check if any of my colleagues wishes to comment! Sorry about that Steve.
Interest rates are coming down big time.
iShares 20+ Year Treasury Bond ETF (NMQ:TLT) is an excellent investment opportunity.
Recession will be long and painful.
All the best
CPI is hot and pours cold water over rate cut prospects unless Oil takes a rather sudden and unexpected turn South.... the Dollar has reacted positively sending Gold and Silver down. For now Bond yields higher has momentum and little to reverse it unless unemployment surprises negatively. An interesting scenario since neither Oil nor AI investment are likely to be that sensitive to interest rates but the market wants them up. Net net its a headache into the year end and supports action to take profits and reduce equity to manage the rise in volatility. An unhelpful data point today.....
Any thoughts on why Ben Stocks appears to have been removed from his job as chairman of Xaar (Xaar (LON:XAR) with immediate effect after just a year? Stocks, who did a good job as the long running ceo of Porvair (Porvair (LON:PRV), seemed a sensible choice on paper, but it sounds like Odyssean Capital IT, Xaar's major shareholder, may have had other ideas. Daniel Dayan, the non-exec chairman of Bodycote, which is currently being bid for, has been drafted in as Xaar's new chairman.
Meanwhile Stocks says that "for reasons of professional focus and concerns about over-boarding, now is a good time for me to step away."
Perhaps the transition from successful company CEO, to successful company chairman, is not as easy as it sometimes seems.
Can a review of Porvair (LON:PRV) be done please guys as they released a trading update this morning and i hold. interested to hear if a peak has likely been reached
SABA is now up at 10% in Grainger (LON:GRI)
Would love to hear views on James Halstead (LON:JHD) and Ashmore (LON:ASHM) as a holder in both.
Graniger is my bet on the housing market. It already has the housed built (at least most of it), therefore increased cost of building does not bother the company. Debt is an issue but the discount compensate for that.
I also hold Ashmore and James Halstead and would welcome Graham comments on the results.
I thought Grainger also developed new properties, so that part of the business would be impacted by higher build costs. Not looked at it recently so they may have scaled back their development activities?
The TU from Robert Walters (LON:RWA) is likely to be of interest to others besides myself. It confirms what is already in the price - the tide for recruitment agencies has turned everywhere outside Europe. In Europe prospects remain poor. It confirms that existing expectations of a full year operating loss of £8 million or thereabouts still hold. It is possible that that is reassuring.
I have noticed in the last couple of days that the daily reads number has trebled. Then it becomes obvious enough that when a person visits the page, the count goes up by 3!
Bots everywhere these days -:)
All the best
I am a bot.
(I visit several times a day)
$SCT
On the face of it SoftCat appears to have produced sparkling results, but the market has marked them down 7.5% so far. The results don't include contribution from their US acquisition, and outside of their US acquisition contribution, they expect to have high single figure growth, and the dividend is increased by circa 7%.
I
At the moment (14 10) Softcat (LON:SCT) is the 4th most viewed share on Stocko but only 1 comment - from Trident.
I thought the results looked good, a slight beat even (eps expected 81.3 actual 83.2) so I was surprised at the 8% share price drop but then I saw this from Reuters: "Co expects to deliver high single-digit underlying operating profit growth in FY2027. Jefferies analysts say 2027 forecast would be one of the slowest growth performances in the last 10 years".
Well, they could have said that a year ago when the company confirmed their guidance for "high single-digit operating profit growth in FY2026" but only if significant incremental contribution from large deals in the comparative period were ignored otherwise low single digit. Today's result was neither - it was 19.4%. This company is generally cautious.
They also say that GDT is not included in the 27 guidance (the completion date has yet to be announced) but they did say that "The Acquisition is expected to deliver in the range of high single-digit to low double-digit underlying EPS accretion in the first full fiscal year with modest financial leverage".
More good stuff from Great Portland Estates (LON:GPE) seems to be forming a bowl... Still a value trap per Stocko
Would it be possible for you to comment on Victorian Plumbing (LON:VIC) ? Ahead of expectations yesterday and stock rank from 80 to 90.
Thank you to Mark Simpson for his comments on Sanderson Design (LON:SDG) I too sold my shares in the Company for a small loss and have taken a keen interest in the outcome of this attempt by LBV to force a GM on the 29th October.
Frontier Developments (LON:FDEV) announce yesterday release of new game, which sounds like good news, and down nearly 9% today, which certainly isn't.
Far too old to be playing video games, but why the bad reaction? A topping up exercise or something I have missed?
Maybe some profit taking after a strong run up to the release? I have to admit I was expecting a strong day today as the number of users playing Planet Zoo 2 on opening day looked very impressive and the game already sits top of the Steam top sellers list in the US and 2nd worldwide. It's already my biggest holding so probably won't buy more on this dip, but certainly won't be selling anytime soon.
Frontier Developments (LON:FDEV)
which sounds like good news, and down nearly 9% today, which certainly isn't.or something I have missed?
shares go up and shares go down its that simple - the share price is above where it was 7 days ago and the shareprice is materially up on where it was since they last updated last month 15% ish i think.
After amazing run up why are you not defaulting to it being natural there would be a minor pullback at some stage (its hardly even that in the scheme of things really) - also whats that addage sell on the news.
10 second google search suggests game has been well received so my lazy research suggests its all sticky tickety boo probably.
"shares go up and shares go down its that simple" - key is not to sell 'em on the way down and buy 'em on the up!!
One share going down forces another share to go up in order to keep the equilibrium stable. Play the game, be a Trader!
I have to do some research - but interestingly Planet Zoo 2 day 1 usage on Steam is way higher than Planet Zoo. 45k users versus 38k... will go and read some reviews.
Possibly “sell the news” after the run-up, plus an early Steam review score that looked soft, rather than anything wrong with demand.
The weak spot is the Steam user score, around 70–71% positive and sitting right on the 70% line where Steam’s label flips from “Mostly Positive” to “Mixed”. In the negative reviews, about half the complaints are launch bugs: crashes, animals glitching through fences, and Franchise mode struggling on day one.
Graham. I appreciate that CNS - Corero Network Security is a tiddler, but in the current environment of cybersecurity risks, their numbers out today look good, and growth could be on the cards. If you have any thoughts, they would be welcome.
Good update from Vertu Motors (LON:VTU) .Their pivot to Chinese Brands seems to be working well, the Jaecoo 7 was the top selling car in September.
I'm certainly noticing a great many of this make and model of car, completely unknown to me before June, on our Westcountry roads.
HI Bob surely the only question is why you have to pay to cross the Tamar Bridge into Devon but it is free to cross into Cornwall......
The Cornish are so much nicer
Vertu Motors (LON:VTU) have done a lot of things right in recent years. I originally bought because of the possibility of a takeover and stayed because it was clearly a well-run business. Robert Forrester is a class act and (more importantly) he seems to have built a system and incentives that make good people want to work and stay at the company. The SP stayed flat for a long time, finally moving in May/June 2026 but the operational improvements had been evident for years in my view. I'm a happy holder.
I wrote about Sanderson Design (LON:SDG) on Monday's DSMR, so I thought it was worth sharing that LBV have responded to the board regarding the requisitioned GM:
https://www.lbvam.com/assets/news/LBV-Response-to-SDG-Circular-13Oct2026.pdf
I have no skin in the game, having sold my shares when I realised the recent rise in the share price appeared to be entirely down to LBV backing its position and the EBT buying shares in an illiquid market. However, LBV's position as laid out above seems entirely reasonable to me, and personally, I hope they are successful with the GM requisition on the 29th.
Any chance you could comment of today’s Thor Explorations results ?
James Halstead (LON:JHD) (I hold)
Morning Graham,
Please could you comment on today's results from James Halstead?
Thanks!
Good morning, I think we will! Cheers Richard.
Lord Lee is also a holder; if he's a subscriber he might welcome your view
;-)
I would welcome Lord Lee's view on James Halstead (LON:JHD)
Any chance we can get a guest column or feature from him on Stockopedia? :)
Good suggestion!
He'll likely mention JHD in his next online chat with Paul Scott.