Daily Stock Market Report (Mon 7th September) - WRKS, SRC, CNC, SDLF, ASHM, RGG

There is no one major news story to mention from the weekend, but rather a handful of smaller ones:
The AfD in Germany has won a local state election in Saxony-Anhalt, attracting 44% of the vote, in a major blow for the ruling Christian Democratic Union.
De Nederlandsche Bank (the Dutch central bank) has moved 86 tonnes of gold, worth about $11 billion, from North America to London. It did this "in view of increasing geopolitical unrest", so that it would be "readily available for use in a crisis situation". It previously held over 300 tonnes of gold in North America.
Following on from the news last week of VW job cuts, Jaguar Land Rover has confirmed that "salaried and management team members" will be offered "the opportunity to leave the business". Up to 4,000 jobs could be cut, according to The Times. JLR employs 33,000 in the UK.
Overnight market movements:
The FTSE is down 0.1% at 10,815
S&P 500 is down 0.1% at 7,710
Brent crude (November) is up 1.6% at $97.80/bbl
Gold is down 0.8% at $4,395/oz
Bitcoin is down 0.2% at $79,800
Roland Head joins me today.
All done for today! Cheers. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£186bn | SR49) | Approval based on SERENA-6 Phase III trial results which showed combination reduced the risk of disease progression or death by 56% in patients with an emergent ESR1 tumour mutation. | ||
Standard Life (LON:SDLF) (£9.4bn | SR70) | H1 operating cash generation +6% to £745m, with IFRS adjusted operating profit up 25% to £563m. Solvency Coverage Ratio -7% to 169% vs Dec 25. Outlook: “on track across all 2026 financial targets”. | AMBER/GREEN = (Graham)
I’m comfortable leaving our stance unchanged today. My reasoning is that even if the adjusted operating profit figures have been inflated by the adjustments, they are still close to £400m (£563m minus £179m). And that’s in just a six-month period. So in valuation terms, at a market cap of less than £10 billion, this does appear to still offer some value. The ValueRank is 61, is and yield is over 6%. That’s before the Aegon acquisition, which brings with it some risk but has the potential to create a nice jump in the overall size of the business. | |
Ashmore (LON:ASHM) (£1.56bn | SR50) | AUM +13% to $54bn with net inflows of $2.7bn and investment gains of $3.7bn. Pre-tax profit +17% to £126.9m with EPS +28% to 15.0p. Outlook: “positive outlook for emerging markets positions the Group well”. | GREEN = (Graham) The high P/E multiple (29x) doesn't tell the whole story here: the balance sheet for June 2026 has equity of about £800m, or half of the company's market cap. Of that figure, only £83m is goodwill; the assets are overwhelmingly "current" and easily converted into cash. As for the performance of the business itself, I'm very encouraged by the inflows Ashmore has achieved ($2.7 billion), helping AUM grow to $54 billion. However, I acknowledge that revenue has been held back by lower performance fees. Personnel expenses have increased too, and adjusted operating profit therefore has taken a step backwards: only £32.1m for FY26, vs. £49.4m for FY25. On the bright side, the company's gains on its seed capital investments (£38.9m) were higher than underlying operating profit, helping to demonstrate the benefit of having a large, well-invested asset base. CEO Mark Coombs can always be relied on to talk up the prospects for investors repositioning into emerging markets, but the inflows here back up what he has been saying recently. I'm also inclined to agree with him on the basis that the US seems tremendously overvalued to me. So I'm leaving our positive stance unchanged here. | |
Sigmaroc (LON:SRC) (£1.43bn | SR84) | Revenue +2.5% to £523m with adj pre-tax profit +11.4% to £75.1m. Outlook: full-year expectations unchanged. Acquisition: will pay up to €118m for Dolomitas, a “leading Lithuanian dolomite business” with c.3.5m tonnes of annual production capacity and c.25 years of reserves and resources. Dolomitas reported revenue of €70m and EBITDA of €18m in 2025. | AMBER/GREEN ↑ (Roland) A reduction in leverage, a sensible acquisition and H1 results in line with full-year expectations. While I take issue with some of the profit adjustments used by Sigmaroc, fundamentally I think the business is in decent shape and is travelling in the right direction. To recognise the upgrade to 27/28 EPS forecasts and underlying momentum I have moved our view up by one notch today. | |
Grainger (LON:GRI) (£1.25bn | SR55) | Occupancy at 96%+ with strong demand and LFL BTR rental growth of 3%, in line with guidance. “Good pipeline momentum”. Outlook: expects to see 35% earnings growth from FY25 to FY29. | ||
Gamma Communications (LON:GAMA) (£1.03bn | SR78) | Revenue +4% to £330m with adjusted pre-tax profit -3% to £59.2m. Adj EPS flat at 47.7p. Stronger growth in German business. Due to proposed acquisition, the group does not intend to pay or declare any further dividends prior to the effective date. Share buybacks are also suspended. | TAKEOVER | |
Spire Healthcare (LON:SPI) (£959m | SR72) | 250 pence in cash. Alternative offer will allow shareholders to apply for “Rollover Securities”. | TAKEOVER | |
Iqe (LON:IQE) (£632m | SR34) | Revenue +43% to £64.6m with pre-tax loss reduced to £(8.2)m and net cash of £30.2m. Seeing strong momentum across markets including AI data centres and defence. Outlook: confident of achieving FY26 guidance for revenue growth of >30% and “low-teens £m adjusted EBITDA”. IQE is now planning to move from AIM to the Main Market. | ||
ACG Metals (LON:ACG) (£472m | SR52) | Entered into an agreement with Meta Nikel Kobalt Madencilik Sanayi ve Ticaret A.Ş. to acquire 100% of mining licence 60926, which contains the Keşkek gold project for an initial cash consideration of US$4 million plus potential contingent consideration of $3.85m. The licence covers 666 hectares. | ||
Petrotal (LON:PTAL) (£271m | SR94) | YTD production of 13,181 bopd with Bretana drilling campaign on schedule to resume in October. Amendment to Block 131 licence has been completed, reducing royalty payments on incremental production. | ||
Kistos Holdings (LON:KIST) (£251m | SR62) | Has received confirmation of Royal Decree from Sultanate of Oman, granting legal ownership to Kistos. Completion of Block 9 continues to progress. | ||
Concurrent Technologies (LON:CNC) (£231m | SR42) | H1 revenue +10% to £23.2m with pre-tax profit +19% to £3.2m and EPS +5% to 2.93p. H1 order intake +110% to £46.9m. Outlook: confident in delivering FY26 profit ahead of market expectations. | AMBER = (Roland) Concurrent is in good health, performing well and continuing to grow. Ultimately, I think the question here is around valuation. The group’s quality metrics are only slightly above average and the stock is already trading at more than 30 times forecast earnings. I’d need to see faster earnings growth or an improvement in profitability to justify taking a positive view here, so I’m leaving our neutral view unchanged today. | |
Gulf Marine Services (LON:GMS) (£198m | SR73) | H1 revenue -3% to $84.1m with adjusted net profit -51% to $6.9m. Net debt +3% to $185.4m with leverage of 1.75x (FY25: 1.39x). Secured backlog of $659m on 17 Aug (FY25: $606m). 2026 outlook: expects stronger H2. EBITDA guidance of $105m to $115m is unchanged. | ||
Ferrexpo (LON:FXPO) (£170m | SR n/a) | SP +28% Following the US$100 million fundraising announced on 4 September 2026, the Company has mobilised its operations over the weekend and production has recommenced using one pellet line. Given the attacks currently taking place on ports and vessels in the Black Sea, the Company intends to focus on exports to customers in Europe. | ||
Rainbow Rare Earths (LON:RBW) (£169m | SR23) | A Pre-Feasibility Study for the Uberaba project in Brazil has commenced in conjunction with partner MOS Utility (NSI:MOS). he PFS will focus on building a processing plant on-site to process the phosphogypsum waste residue at an annual throughput of c. 2.7 Mtpa over an initial project life of 30 years. | ||
KEFI Gold and Copper (LON:KEFI) (£162m | SR11) | The company experienced a serious security incident on 4 September 2026 resulting in “multiple fatalities involving security personnel and community members, including one Company employee”. Work on project development activities has been suspended while the company engages with community, government and security stakeholders. | ||
Savannah Resources (LON:SAV) (£151m | SR34) | Has started the “final pre-construction drilling programme” on the Barroso lithium project. Two rigs are currently operating at site. | ||
Rentguarantor Holdings (LON:RGG) (£150m | SR42) | Three new non-executive directors appointed. In addition, the Chief People and Risk Officer has joined the board and a non-exec, David Cliff, has transitioned to an Executive Director role as Director of Research and Innovation. | GREEN = (Graham) [no section below] One of the things which has made me turn positive on RGG is the belief that it has achieved a high level of legitimacy in the UK property market, giving it an advantage over competing services. For example, in February of this year, it announced a strategic partnership with the National Residentail Lanlords Association. As part of that deeal, the NRLA agreed to promote the RGG service to its membership of over 111,000 landlords: more than just a "recognised supplier", it has developed a closer partnership with the NRLA. Today's Board changes include a NED who is Director of Home Moving Strategy at the Mortgage Advice Bureau. This continues to strike me one of the most interesting growth stocks we look at in this report. | |
Strategic Minerals (LON:SML) (£147m | SR45) | The company’s wholly owned subsidiary, Southern Minerals Group LLC, has agreed an extension to its access to the Cobre magnetite stockpile in New Mexico, USA, to 31 March 2031. This agreement previously expired in March 2029. | ||
Team Internet (LON:TIG) (£103m | SR44) | Revenue down 32.1%. Adjusted EBITDA down 20.7%. Loss after tax $6m. Trading since the period end has been in line with the Board's expectations. Confident of a stronger second half and a return to year-on-year earnings growth in H2 2026. “The strategic review is at an advanced stage, with discussions ongoing with a view to reaching a transaction in the near term… The Board reaffirms its expectation of a valuation materially exceeding USD 160 million.” | ||
Gateley (Holdings) (LON:GTLY) (£80m | SR42) | Austen Hays, has secured a settlement in respect of its first class action. Anticipated to result in a significantly improved contribution from Austen Hays and a cash benefit to the Group's net debt position this financial year. | ||
Cora Gold (LON:CORA) (£73m | SR22) | “These results continue to demonstrate the broad nature of the mineralisation that we come to expect from Zone B, and importantly it is the higher-grade core of these mineralised zones in the fresh rock that start to demonstrate the possibility of a much greater extended mine life, beyond the oxide mining and processing…” | ||
Ondine Biomedical (LON:OBI) (£63m | SR11) | Partnership with Hospital Ángeles Health System, Mexico's largest nationwide private healthcare network, to launch a multi-center pilot of Steriwave® nasal photodisinfection. | ||
Works uk (LON:WRKS) (£55m | SR95) | First 18 weeks of FY27: LfL sales +10.4%. “Whilst mindful of continuing macroeconomic uncertainty and that the key Christmas trading period is still to come… the Board now expects FY27 pre-IFRS 16 Adjusted EBITDA to be at least £16.0m, ahead of its previous guidance and current market expectations.” Prior expectations were £15m. | AMBER/GREEN = (Roland) [no section below] Much will depend on trading during the festive period, but today’s upgrade is positive; a 10% increase in LFL sales so far this year suggests to me that both volumes and prices have increased. Based on today’s upgrade, I estimate we could see a modest improvement in margins this year on top of higher sales. That should be good for cash generation. With the shares trading on c.9x FY27 earnings and the business showing good momentum, I don’t see any reason to change our previous broadly positive view. | |
Batm Advanced Communications (LON:BVC) (£52m | SR54) | A second order from a leading broadband communications provider in the US that serves more than 1.1 million residential and business customers across 24 states. The order is worth $1m and is expected to be delivered in the current financial year. | GN note: no reference to any impact on expectations. | |
Oxford Metrics (LON:OMG) (£44m | SR50) | Stefan Lampa’s appointment to take effect from early December 2026. He was most recently CEO of ProGlove, a provider of smart wearable scanner solutions for industrial applications. | ||
Churchill China (LON:CHH) (£42m | SR91) | Revenue down 2.9%. Operating profit before exceptional items down 17.9% (£2.3m). “Sales decline from 2025 has stabilised in a contracting market.” Performance has been broadly in line with expectations with profitability improving in Q2. Continue to expect full year profitability to be in line with expectations. James Roper recently became CEO (the Roper family have been involved with Churchill for over 100 years). | ||
Christie (LON:CTG) (£41m | SR87) | Darren Bond joins the Board as an executive director. He has been with Christie & Co since 2001. He is Global MD of Christie & Co and is a director of a number of Christie Group subsidiary companies. | ||
Getbusy (LON:GETB) (£35m | SR29) | ARR up 22% to $19.1m. H1 revenue up 9%, H1 loss before tax £428k. 2026 SmartVault ARR growth expected to be around 20%, exceeding current market expectations, with further upside potential from the second season of SmartRequestAI® availability. | ||
Amigo Resources (LON:AMGO) (£35m | SR83) | Achieved total gold production of 10 kilograms during August 2026. Amigo's immediate operational priority is expanding processing capacity across Mojimoto and Kabete. | ||
XP Factory (LON:XPF) (£34m | SR56) | FY March 2026: Underlying revenue +3%. Adjusted operating profit £0.8m. Net debt £5.9m. Trading since then: Unusually warm and dry weather impacted demand for indoor activities, subsequent improvement with normalisation in weather in recent weeks. LfL December B2B booking up 15%. The board continues to expect performance for the year to be in line with market expectations. | ||
Kavango Resources (LON:KAV) (£30m | SR4) | Jasper Musadaidzwa is “a highly experienced mining executive with more than 27 years' experience across the mining industry, including 17 years with AngloGold Ashanti”. | ||
Medpal AI (LON:MPAL) (£24m | SR3) | Annualised run rate now stands at c. £28m across three recurring revenue streams. | ||
Prospex Energy (LON:PXEN) (£21m | SR43) | Operational update “which demonstrates strong progress being made across all of the Company's operations in line with management expectations supported by a highly favourable macro-economic background for energy pricing in Europe.” | ||
Symphony Environmental Technologies (LON:SYM) (£16m | SR15) | Successful completion of an extensive independent testing programme. "...an important addition to a substantial body of scientific evidence demonstrating that plastics made with d2w® technology do not behave like conventional plastics at the end of their service life.” | ||
Kropz (LON:KRPZ) (£15m | SR40) | Has begun an urgent operational review and restructuring process at Elandsfontein. “...necessary to establish a more sustainable operating model.” | ||
Fulcrum Metals (LON:FMET) (£12m | SR9) | Seven prominent uranium-related radiometric anomalies have been identified, including one of the strongest responses north of Neely Lake. “...an encouraging start to Terra North's exploration programme at Charlot-Neely.” | ||
Tern (LON:TERN) (£11m | SR37) | Shareholders are entitled to subscribe for Open Offer Shares at the Issue Price (0.9p) on the basis of 1 Open Offer Share for every 16 Ordinary Shares. Friday’s close: 1.2p. |
Graham's Section
Standard Life (LON:SDLF)
Up 2% at 953p (£9.6bn) - Interim Results - Graham - AMBER/GREEN =
I don’t cover this one too frequently, but let’s take a look.
Standard Life plc was previously known as Phoenix Group Holdings plc. Standard Life is simply the main brand that it owns.
Financial KPIs for H1 to June 2026:
Operating cash generation +6% year-on-year to £745m
Solvency II leverage ratio 29% (Dec 2025: 33%)
IFRS adjusted operating profit +25% year-on-year to £563m
Statutory loss after tax £179m
The first three metrics above are all perfectly good.
Roland noted last year that the company was targeting a 30% leverage by the end of 2026. That has been achieved.
The number we’ll have to investigate is the fourth one, the statutory loss, along with the decline in shareholders’ equity (adjusted equity fell from £3.1 billion in Dec 2025) to £2.7 billion).
Here’s what the CEO says:
Standard Life continues to demonstrate exciting momentum against our vision to be the UK's leading retirement savings and income business. Our strong half year results reflect how we are helping more customers achieve better outcomes and we remain on track to deliver our end-2026 financial targets, while our profitable growth and strong cash generation is increasing our financial flexibility. The £2 billion acquisition of Aegon UK and our recently announced UK PRT partnership will further strengthen our capabilities and customer offering. Standard Life champions the belief that everyone's journey to and through retirement can be better and we look to the future with confidence."
The two core business have both seen large growth in H1 adjusted operating profit:
Pensions and Savings - adjusted operating profit up 36% to £244m.
Retirement Solutions - adjusted operating profit up 13% to £324m.
Coming up later this year is the £2bn acquisition of Aegon, which will create “the UK’s largest retirements savings and income business”.
Other players are said to be big in either Workplace or Retail pensions, while SDLF will have the #2 spots in both.
This will be paid for with £750m of cash and 181 million new SDLF shares (15% of the enlarged group). The amount of debt that will be used is “consistent with our target leverage ratio of 30%.”
The headline profit figures around this proposed deal are very encouraging: SDLF will acquire £160m of operating cash generation (FY25), expected to grow at mid single digits. They are also expecting £340m of one-off synergies and £110m of annual pre-tax cost synergies.
The price being paid is nearly a 20% discount to Aegon’s “Unrestricted Tier 1 capital”, which is conceptually similar to Aegon’s book value.
Statutory profits
Here’s the bridge between adjusted operating profit and the statutory loss:
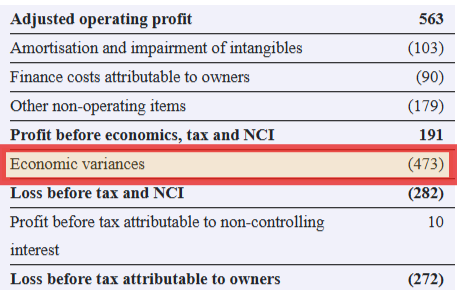
The key number is Economic Variances, highlighted above. The explanation is that the company hedges its exposure to equity markets and interest rates. With equity markets rising in H1, this results in a loss on its hedges, with the corresponding gains not shown on the accounting financial statements.
Combine this £473m “Economic Variances” loss with nearly £300m of dividends and also nearly £200m of “other non-operating items” (shown in the above table), and you get the decline in balance sheet value we mentioned earlier.
It sounds to me as if lots of awkward costs have been lumped into “other non-operating items”:
Other non-operating losses in the period totalled £179 million (H1 2025: £184 million loss), the majority of which reflects £123 million of planned investment spend across our strategic priorities, with £56 million of other one-off items that includes £25 million expenditure on strategic transactions announced this year.
This does make me wonder if the “adjusted operating profit” figure of £563m is rather optimistic. Should we really ignore “investment spend” on “strategic priorities”?
If the figure in H1 last year had been much lower, I’d be more inclined to look past this, but that’s not the case. It was £184m in H1 last year, and £179m in H1 this year.
Graham’s view
Roland was AMBER/GREEN on this a year ago at 625p.
I’m comfortable leaving our stance unchanged today.
My reasoning is that even if the adjusted operating profit figures have been inflated by the adjustments, they are still close to £400m (£563m minus £179m). And that’s in just a six-month period.
In 2025, full-year AOP was £945m.
So in valuation terms, at a market cap of less than £10 billion, this does appear to still offer some value. The ValueRank is 61, is and yield is over 6%:
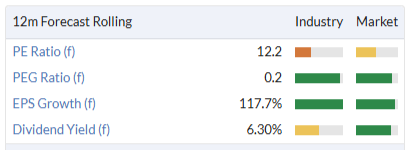
That’s before the Aegon acquisition, which brings with it some risk but has the potential to create a nice jump in the overall size of the business.
So this gets one thumb up from me.
Roland's Section
Sigmaroc (LON:SRC)
Up 12% at 144p (£1.60bn) - Interim Results & Acquisition of AB Dolomitas - Roland - AMBER/GREEN ↑
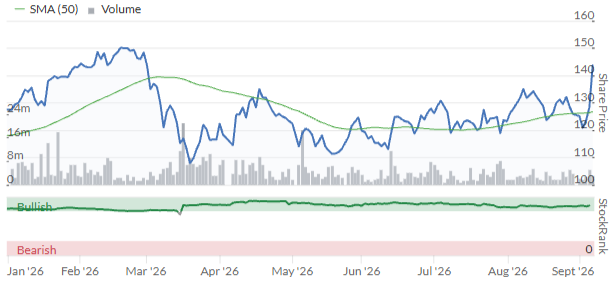
We haven’t looked at this lime and minerals group since March, when Graham took a neutral view. Until this morning, very little had happened to the share price since then.
However, today’s in-line half-year results and acquisition news have prompted investors to nudge the shares higher, lifting the stock into positive territory for the year to date:
Half-year results summary
With signs of improvement in some end markets and the continued focus on operational excellence, the Board remains confident in delivering full year results in line with consensus expectations.
The headline numbers from today’s half-year results suggest Sigmaroc is on track to meet existing forecasts:
Revenue up 2.5% to £523.1m
Adjusted EBITDA up 11.3% to £131.2m
Adjusted pre-tax profit up 11.4% to £75.1m
Adjusted EPS up 12.2% to 5.23p
Net debt down 7.2% to £462.6m
Covenant leverage of 1.66x EBITDA (FY25: 1.80x)
The reduction in net debt and leverage is welcome and suggests the business is generating genuine free cash flow. A quick look at the cash flow statement confirms this view: my sums suggest the business generated around £27m of surplus cash during the period, mirroring the reduction in net debt.
Trading appears to have improved during the second quarter, with the company reporting a 1% increase in like-for-like “core” volumes for the half year.
This follows a 3% decline in volumes during Q1 due to severe weather, so we can conclude that core volumes rose by around 4% in Q2.
It looks like further improvement is expected during the second half of the year, with the company noting “seasonally stronger H2 trading trending ahead of the prior year”.
Pricing is said to be strong with “attractive dynamics” in key markets despite the situation in the Middle East.
Profit adjustments: when Graham looked at Sigmaroc’s FY25 accounts in March, he concluded that they were not clean.
Having looked at today’s half-year numbers, I’ve come to the same conclusion. £25m of adjustments are used to increase reported net profit of £34.8m by 72% to an adjusted figure of £59.9m!
Here’s the full list:
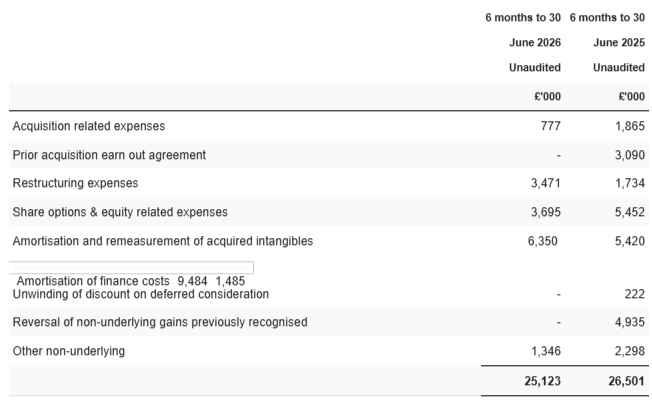
Opinions vary on how many of these are acceptable. Personally, I would not accept restructuring or share option expenses as in my opinion these are respectively business-as-usual and remuneration.
For an acquisitive business like this one, I’m also reluctant to accept too many acquisition-related expenses. They keep on coming and are an inevitable consequence of the business model.
“Other non-underlying” items are said to be professional adviser fees and similar, so I would guess some of these may also relate to restructuring and/or acquisition activity.
Profitability: in case it seems like we are overly petty about adjustments, I think it’s worth pointing out the difference these arbitrary exclusions make to the returns generated by a business.
I’ve calculated Sigmaroc’s trailing 12-month return on capital employed using adjusted and reported operating profit to illustrate this:
TTM ROCE (reported op profit): 7.5%
TTM ROCE (adj op profit): 9.7%
For a capital-intensive and relatively low-return business such as Sigmaroc, I would suggest that a 2% change in ROCE could be the difference between earning a return above the company’s cost of capital and failing to do so.
Outlook & Broker Estimates
Despite the positive reception given to today’s results, the company’s expectations for 2026 are unchanged.
The two broker forecasts that I can see for 2026 are unchanged or lower today:
Panmure Liberum FY26E adj EPS: 11.2p (unch)
Zeus FY26E adj EPS: 10.8p (prev. 11.0p)
The equivalent consensus figure on the StockReport is 10.9p, so it looks like brokers covering the stock have a fairly uniform view on 2026.
What has changed is the outlook for 2027, with both Panmure and Zeus upgrading their estimates for future years to reflect the expected contribution from today’s acquisition (which I cover below):
Panmure Liberum FY27E adj EPS: 12.6p (prev. 12.4p)
Zeus FY27E adj EPS: 12.7p (prev. 11.8p)
For some context, the 2027 consensus on the StockReport prior to today was 11.8p, so it looks like today’s acquisition is expected to add c.7% to 2027 earnings.
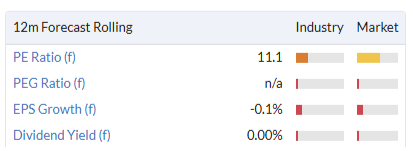
Pricing Sigmaroc against these revised 2027 EPS forecasts gives me a P/E of 11. That’s in line with the rating prior to today:
Let’s take a look at Sigmaroc’s latest purchase.
Acquisition of AB Dolomitas
AB Dolomitas is a producer of “high-quality dolomite” located in Lithuania. Dolomite is apparently a subgroup of high-grade limestone that’s “able to supply all of SigmaRoc’s core segments, whilst also being critical for the production of Green Steel”.
Dolomitas is said to be “an essential supplier to a significant network of companies and sectors” in the Baltic region. The company also has its own logistics network in the form of trucks and rail wagons.
Some key metrics about the acquisition:
Dolomitas generated revenue of €70m and EBITDA of €18m in 2025 (25% margin).
Sigmaroc is paying €110m (€90m cash + €20m new SRC shares), plus up to €8m for “certain non-core assets”, giving an acquisition multiple of c.6.5x EBITDA, slightly above Sigmaroc’s own EV/EBITDA multiple of c.7.5x.
Dolomitas has annual production of c.3.5m tonnes of dolomite and c.25 years of reserves and resources, “with the potential to secure additional reserves and resources for another ~20 years”.
The size, valuation and purpose of this acquisition all look reasonable to me. It’s consistent with Sigmaroc’s existing geographic and market footprint and is small enough to be a bolt-on deal that shouldn’t have too much impact on leverage.
Roland’s view
We’ve been neutral on Sigmaroc in recent times, despite the StockRanks taking a more favourable view:
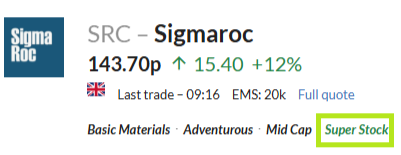
I can see some arguments in favour of staying neutral. I don’t think this is a business that deserves to be valued on a high earnings multiple. While quarries such as those owned by Sigmaroc tend to enjoy strong localised market share, they don’t generate high returns on capital. I don’t see this as a potential compounder:
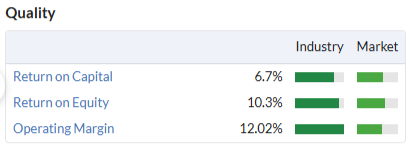
On the other hand, earnings forecasts have edged higher over the last 12 months and have been upgraded again today (for 2027 and 2029). This positive momentum is encouraging, suggesting Sigmaroc’s acquisition-based growth model is delivering results.
As these upgraded numbers feed into investors’ valuation estimates, we could see the stock drift higher.
I wonder if there could also be some upside to 2026 forecasts if the “seasonally stronger” trends highlighted today continue.
Finally, I’m encouraged by the upwards StockRank trend seen over the last two years:
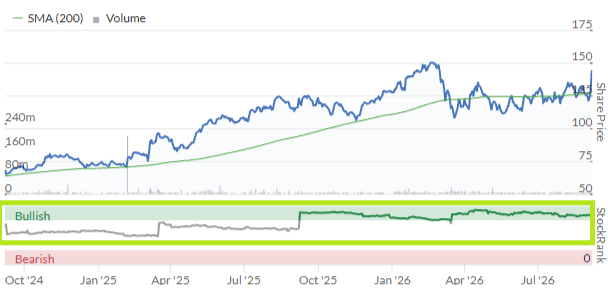
I’m going to take a chance and move our view to AMBER/GREEN today, with the caveat that I’d turn neutral if earnings momentum eases or if the valuation becomes too demanding.
Concurrent Technologies (LON:CNC)
Up 4% at 275p (£238m) - Interim Results - Roland - AMBER =
Half-year results: today’s headline numbers look fairly strong, with a remarkable 110% increase in order intake for the half year. This means that 2026 YTD order intake has now equalled the £47.0m reported for the whole of 2025:
Revenue up 10% to £23.2m
Pre-tax profit up 19% to £3.2m
Adj EPS +5% to 2.93p
Order intake +110% to £46.9m
Profitability also improved in H1 relative to last year, with an H1 operating margin of 14.4% (H1 25: 12.8%). However, it seems that margins may weaken slightly in H2. My reading of today’s upgraded guidance is that revenue will grow faster than profit during H2, depressing margins (my emphasis):
The Board is confident in delivering FY26 revenue materially ahead of market expectations. Profit for FY26 is expected to be ahead of market expectations.
The company obfuscates the reasons for this slightly, in my view, blaming both the phasing of revenue and profit recognition from a large contract and “some material one-off people related costs in the year”.
I’m not completely sure how to interpret the likely impact of this on 2027 margins, but I don’t think there’s anything serious to worry about and would guess that margins will remain broadly stable.
Broker estimates: however, I do think it’s interesting that broker Cavendish (at least) has not chosen to upgrade its EPS forecasts today, pointing out that its 2026 adj PBT forecast of £8.3m is already ahead of £8.0m consensus.
For a more rosy view, paid research house Equity Development are now forecasting 2026 EPS of 7.5p for Concurrent, nearly 10% above Cavendish’s unchanged 6.8p forecast.
My feeling is that any upgrade to consensus after today’s results could be relatively modest.
More broadly over the last year, it’s worth remembering that the trend in earnings forecasts has been slightly negative. This means that any upgrade following today’s results only seems likely to return expectations to where they were at the start of 2026:
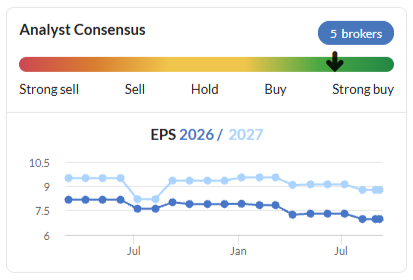
Roland’s view
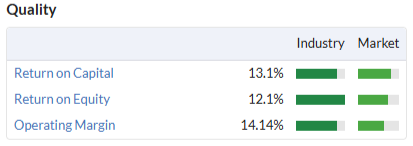
Concurrent is in good health, performing well and continuing to grow. Ultimately, I think the question here is around valuation.
While recent growth has been strong, quality metrics are only slightly above average…
… and the shares are already trading on a rolling forecast P/E of 32:
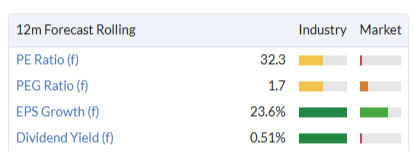
I would need to see more rapid earnings growth or stronger quality metrics to persuade me to take a positive view, so I’m staying neutral today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

28 comments
It seems no one else has picked up on the Next #NXT win in their equal pay court case.
How significant will it be as this will not only impact Next and other private sector companies but also the pubic sector, especially councils
My goodness, although RGG are slightly dipped as I look this morning, they have certainly got some pedigree management joining them to assist with what has been a meteoric growth. I am certainly provided much confidence as I scroll through the joint experience they bring to the company
Not surprise about JLR given they killed off the Jaguar brand manufacturing can’t afford to lose volume in the way they did for that fancy electric car strategy which still hasn’t materialised!
Ford then Tata, both amongst the largest car makers on the planet and owners of Jaguar Land Rover are making commercial, vehicles, buses and cars at the forefront of EV technology. It's just more expensive to do so in Britain.
I'm confused. Your daily report says of FXPO "shares currently suspended" yet according to your stock report the share price today is up "9.70+33.94%"
Please advise…
"....the suspension of listing is expected to be lifted at 7.30 a.m. on 7 September 2026..."
That was published on Friday but not picked up here.
https://www.londonstockexchang...
thanks, I've amended the table.
Thank you!
Can someone advise where I can find the takeover guide that Stocko published - earlier this year ? many thanks
Type in Takeover 2026 in search and scroll down to the articles. Regards julie
thankyou Julie
Do you mean this: https://www.stockopedia.com/ac...
yes thats perfect, thankyou Rusty2
Churchill China (LON:CHH)
In a rubbish market I thought that the interims were half decent.
The ship appears to have stabilised with self-help in the guise of factory automation and stock reduction to help match supply and demand. The shares remain cheap whichever way one looks at it, on trough earnings.
New CEO, James Roper a member of the founding family, with a significant holding knows the business well. When the economic and geo-political backdrop improves and at some point they will, I expect the shares to perform.
There has been no dilution. Thirty months ago the shares were £14.
With half decent markets I see no reason why they can't achieve Panmure Liberum £7 target. I have a modest holding and will continue to take the decent dividend while awaiting a recovery,
Patience as Lord Lee would say
RE: Gamma Communications (LON:GAMA)
Second bid expected: https://www.marketscreener.com...
timarr
And with Bodycote (LON:BOY) still trading above offer price maybe a second bid expected here too?
Hi bohenie
And with Bodycote (LON:BOY) still trading above offer price maybe a second bid expected here too?
Maybe, although the timeline there might be extended. I took the offer on Bodycote (LON:BOY) but hanging onto Gamma Communications (LON:GAMA) for the time being.
timarr
South Korean shares rose by more than 4% today. This is good news for the chip makers, I assume.
After a week away you get quite a different impression feeding numbers into a spreadsheet rather than watching the news. Of course there is always plenty to worry about....but markets don't seem as worried as the news channels. Vix has ticked up a little off low levels but at 14.5 is hardly worth comment....ditto MOVE which also remains low at 73. Bond yields have ticked up pretty much across the board and this is grabbing attention. The curve has more term premium this time compared to when 2 and 10 year yields were at similar levels last...BUT inflation expectations in the market remain at the same rather dull levels ...mid 2%. Of course various commodities are picking up causing some concern but this doesn't always feed into consumer prices ...and although the Dollar seems weaker ....it doesn't feel like the environment for the Euro to rip too much. So outside of something completely unexpected markets appear calm...but commentators edgy ...which is no doubt a healthy combination for now. I would lean a little more cautiously for choice but I haven't managed to do much - high cash is a nice defence but it does make you much money. Good luck all.
Good Morning, should note that U.S. market is closed for "Labor Day" holiday today.
done!
Sigmaroc (LON:SRC) I hold
Positive interim results and a worthwhile looking small bolt on acquisition from Sigmaroc. Management here impress me with the astute way they have built this business and are steadily improving margins. Would be good if the team could take a more detailed look today.
thanks for the suggestion, rwh3ue! Myself and Roland are here today. G
I can never remember the jump rules..if Sigmaroc (LON:SRC) holds the 11% upward move today, will it qualify please anyone? Many thanks in advance
On the back of Zeus increasing 2027 eps estimates
Good Morning Graham, could you cast your eyes over the Standard Life (LON:SDLF) results today? Looks like a generally positive update
that's noted, Felix! thank you.