Rockwood Strategic: How Smart Money Targets Turnarounds

Many investors aim to invest like ‘smart money’, institutional investors who spend their time analysing stocks and deploying millions into their portfolios. Research shows it is possible to outperform the market by piggybacking their moves. For instance, shares often rise when institutional investors take high-conviction positions in a company.
At the same time, blindly copying smart money can feel like copying someone else’s homework. There is a better approach. Understand smart money techniques and apply them as part of your own skillset. As the saying goes: “Give a man a fish, and you feed him for a day; teach a man to fish, and you feed him for life.”
With that in mind, I’ve analysed trades made by Rockwood Strategic, an investment trust focused on turnaround opportunities. Studying their trades reveals various qualitative and quantitative rules - practical criteria that can be used independently, so that we’re not just imitating smart-money investors. Instead, we can use smart money trades as timing signals within our own framework of analysis.
Who are Rockwood Strategic?
Let’s start by understanding who Rockwood Strategic are.
- Their strategy targets cheap turnarounds - i.e. ‘undervalued’ companies likely to benefit from operational, strategic or management changes.
- Their portfolio stays concentrated in around 25 stocks, where the top 10 holdings constitute approximately 60% of NAV.
- Their approach adds value through active engagement with their investments.
- This strategy seems to have paid off in recent years. Their NAV returned 21% in 2024–25, compared to just 3.4% for the FTSE Small Cap.
I examined holdings that made up a large portion of NAV. Their statements don’t provide a formal investment checklist, but we can infer criteria by examining the financial data of Rockwood’s holdings at the time they began investing. Sometimes Rockwood tells us exactly when they started buying. For example, their statements note: ‘We commenced buying M&C Saatchi for the strategy in November 2020.’ When these details are unavailable, I used a proxy, namely the date when a holding first appeared in the financial statements.
A Smarter Approach to Value
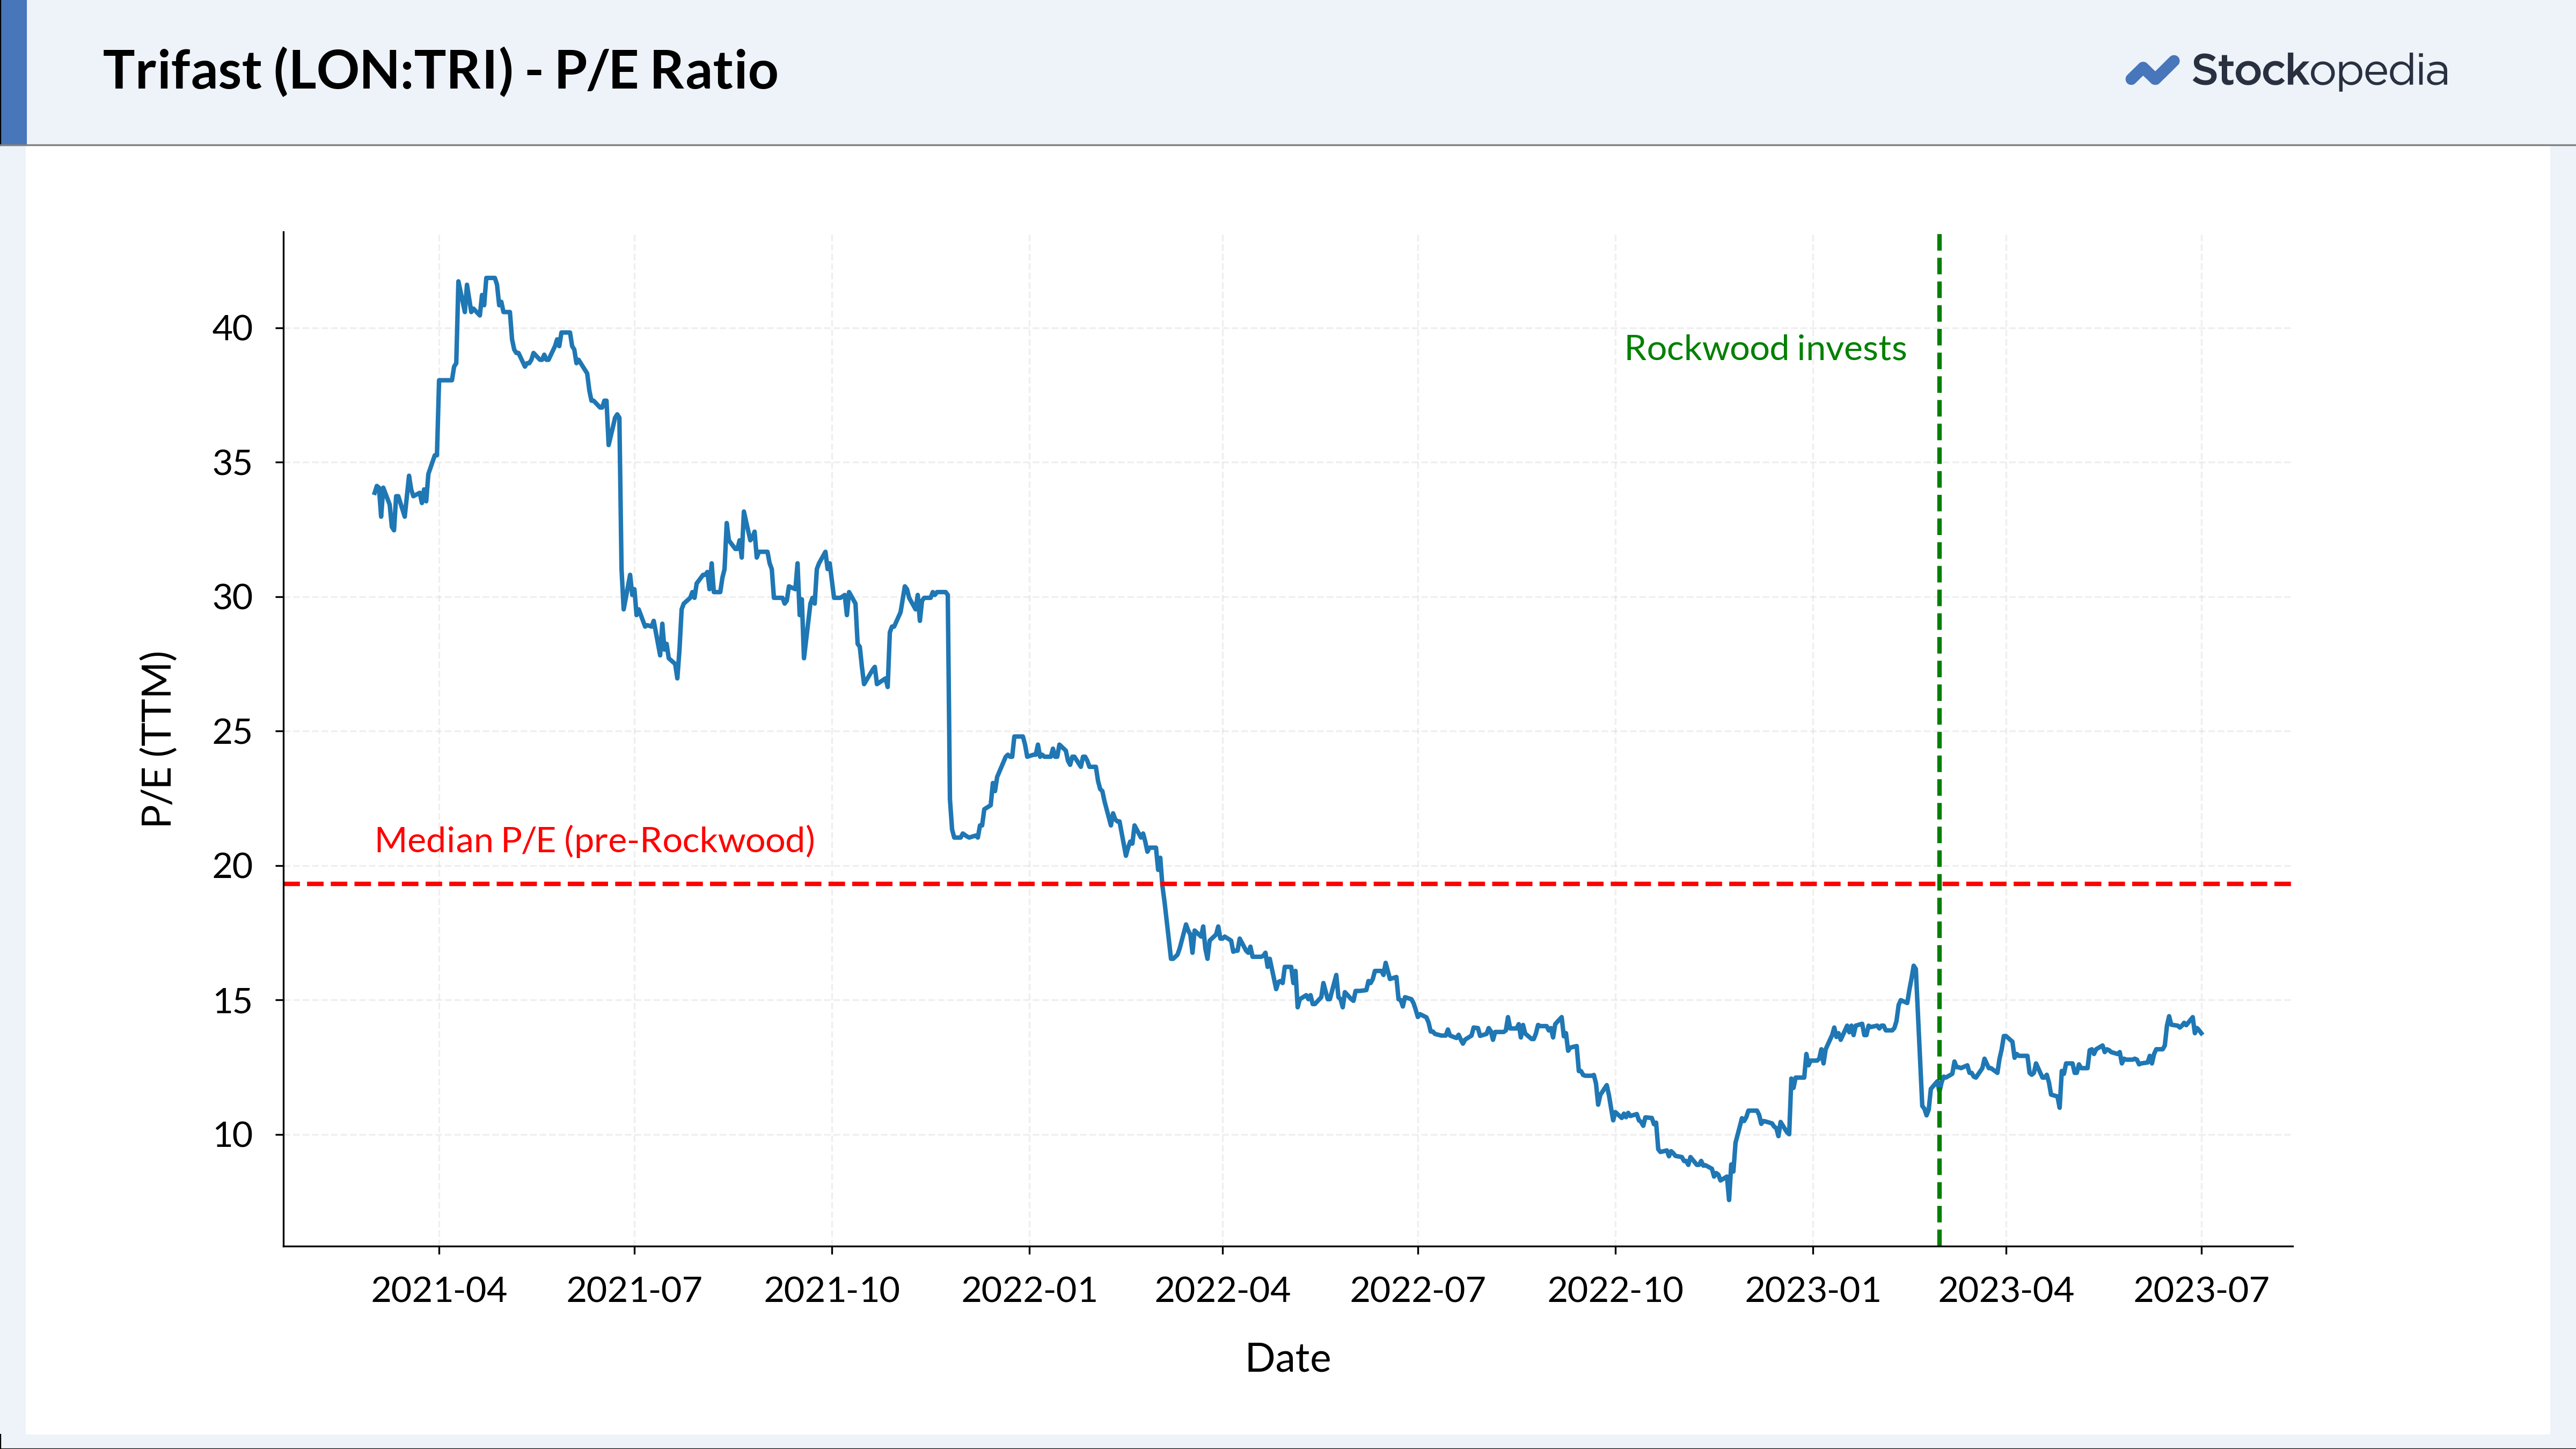
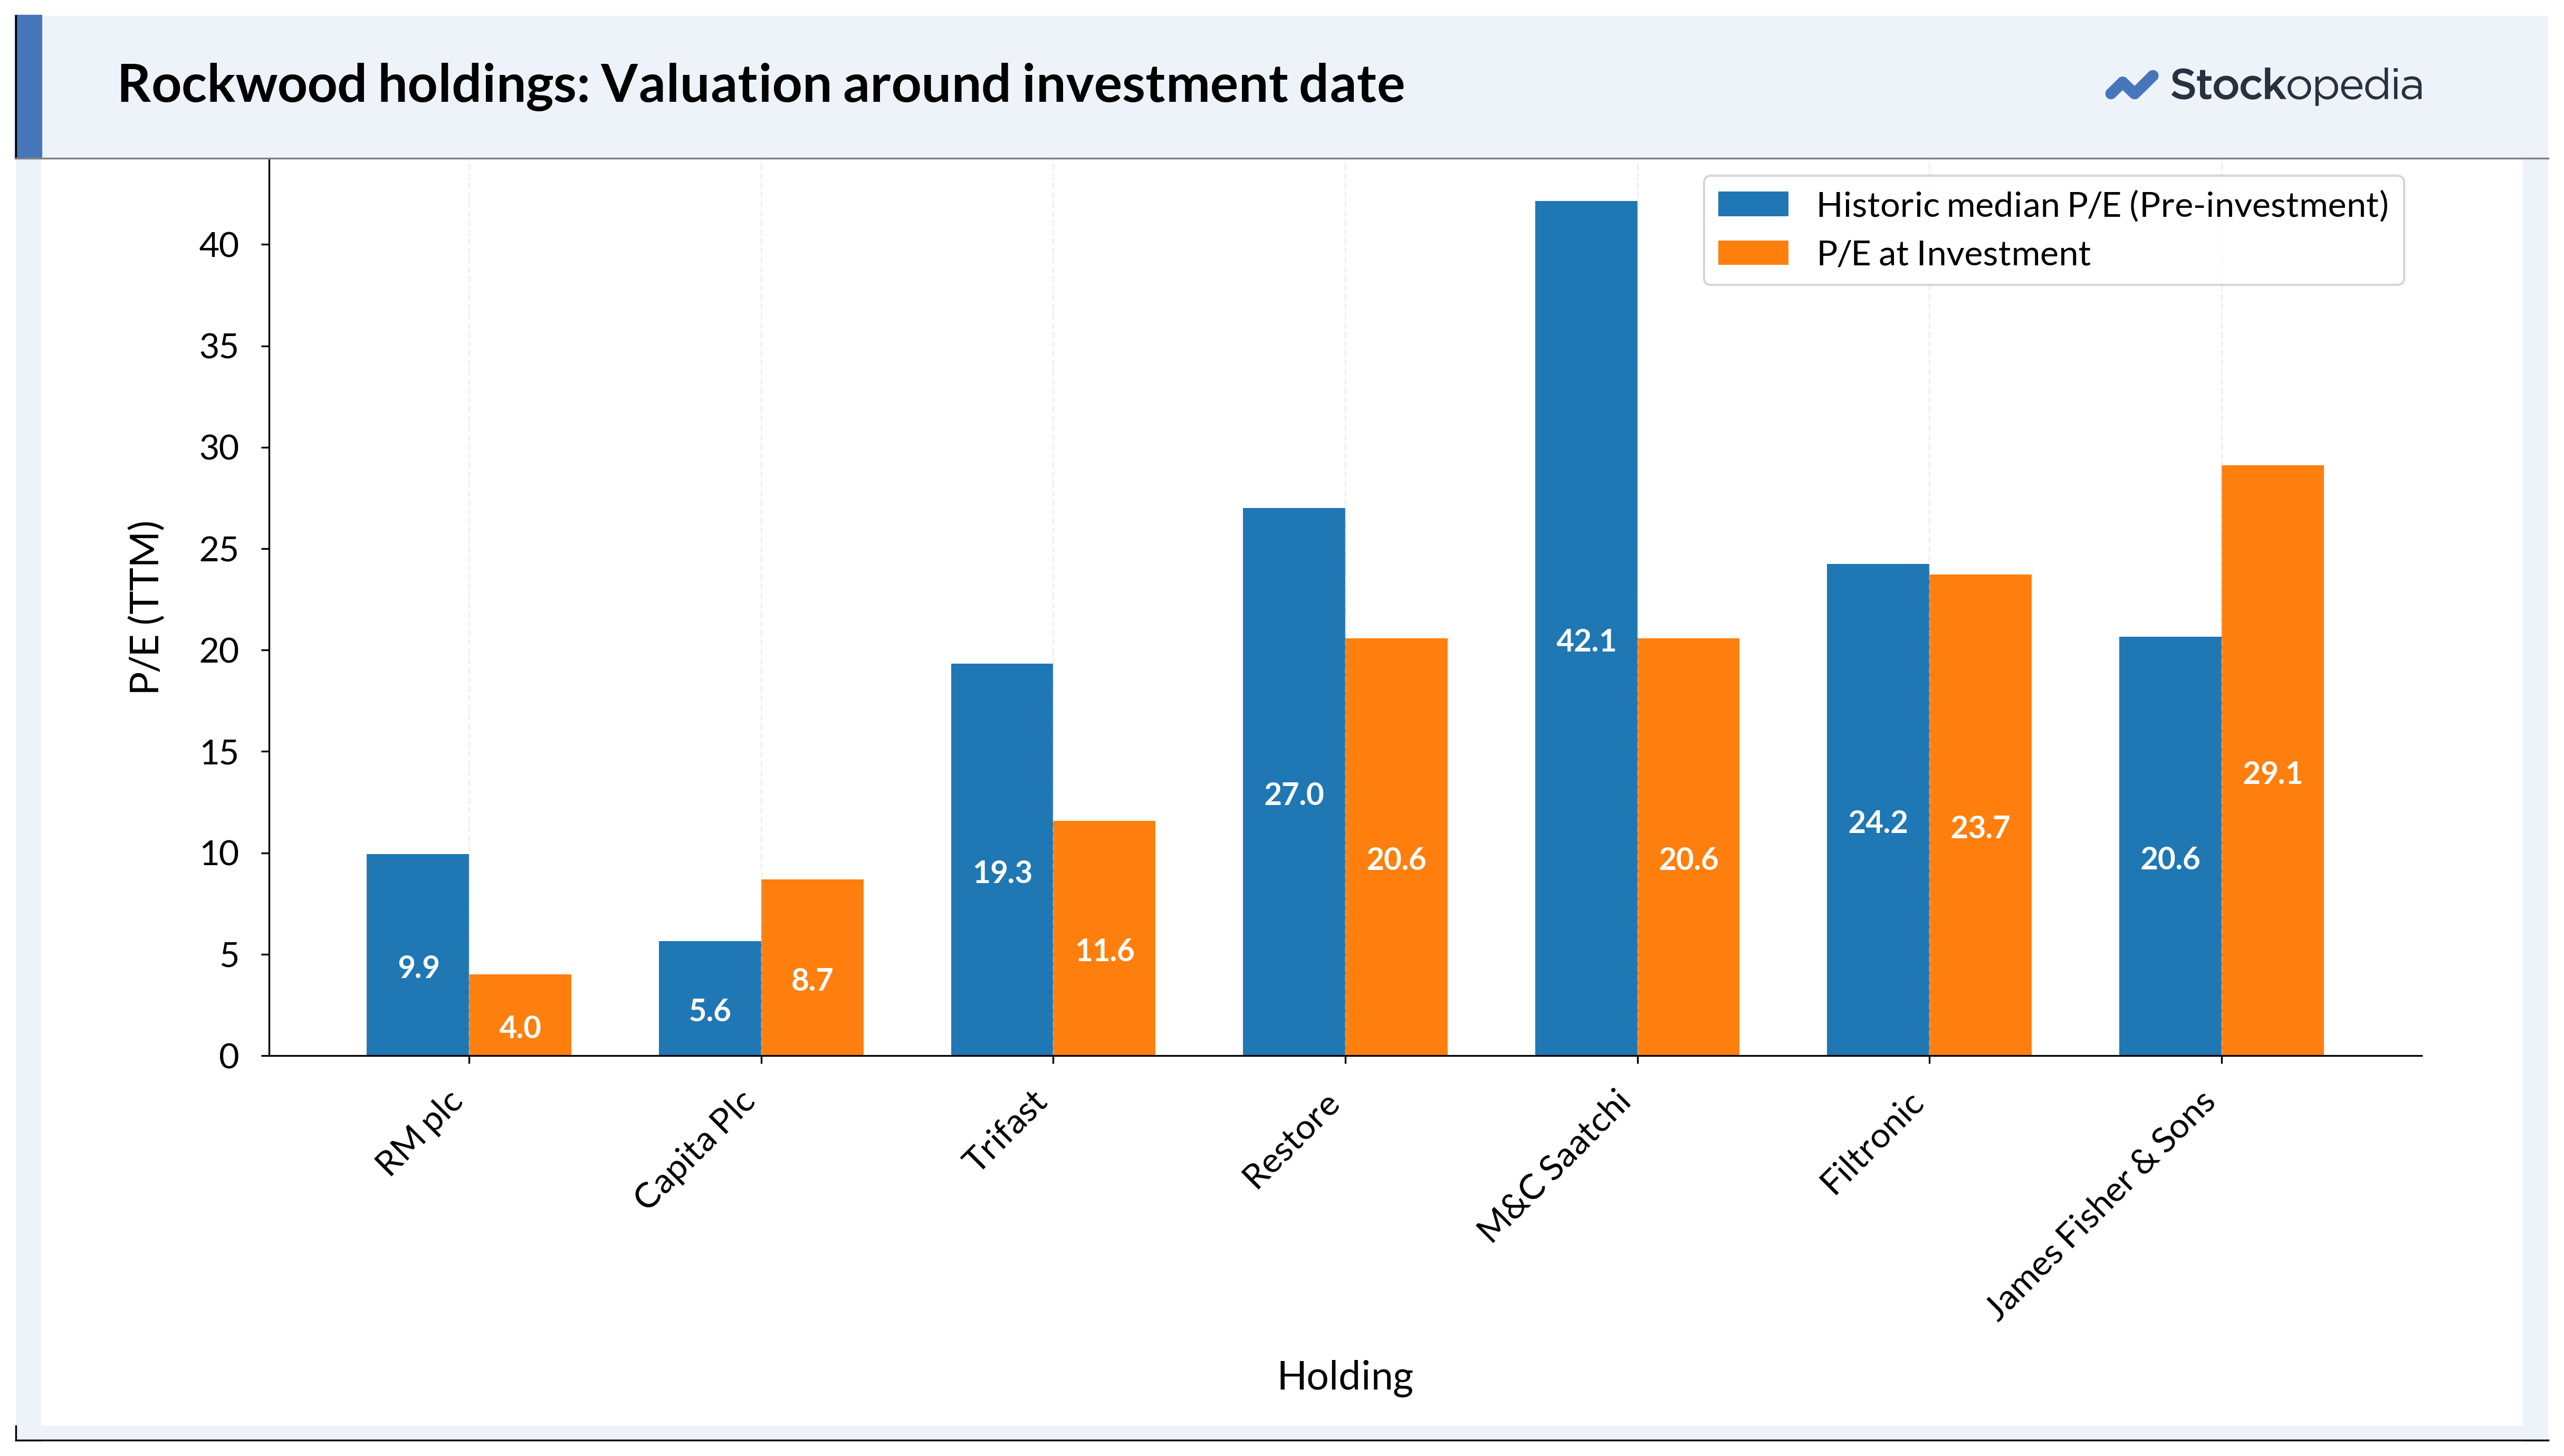
The word ‘undervalued’ appears frequently in Rockwood’s statements, but they never define it in quantitative terms. They don’t explicitly state a preference for companies with a P/E ratio below, say, 15.
Even so, we can see that Rockwood often targeted companies trading below their historic median P/E ratio. Rather than applying an arbitrary valuation threshold, they often compared each company’s valuation to its own historical range.
A Smarter Way to Time Investments
When shares are cheap, it is often because they have weak price momentum. I personally prefer to invest in shares that have strong price momentum - when the price rises, it can serve as a ‘buy trigger’, because it suggests an investment thesis has social proof and the price could be bolstered by investor sentiment. However, Rockwood Strategic appear to disregard this line of thinking entirely. They often buy when momentum is weak.
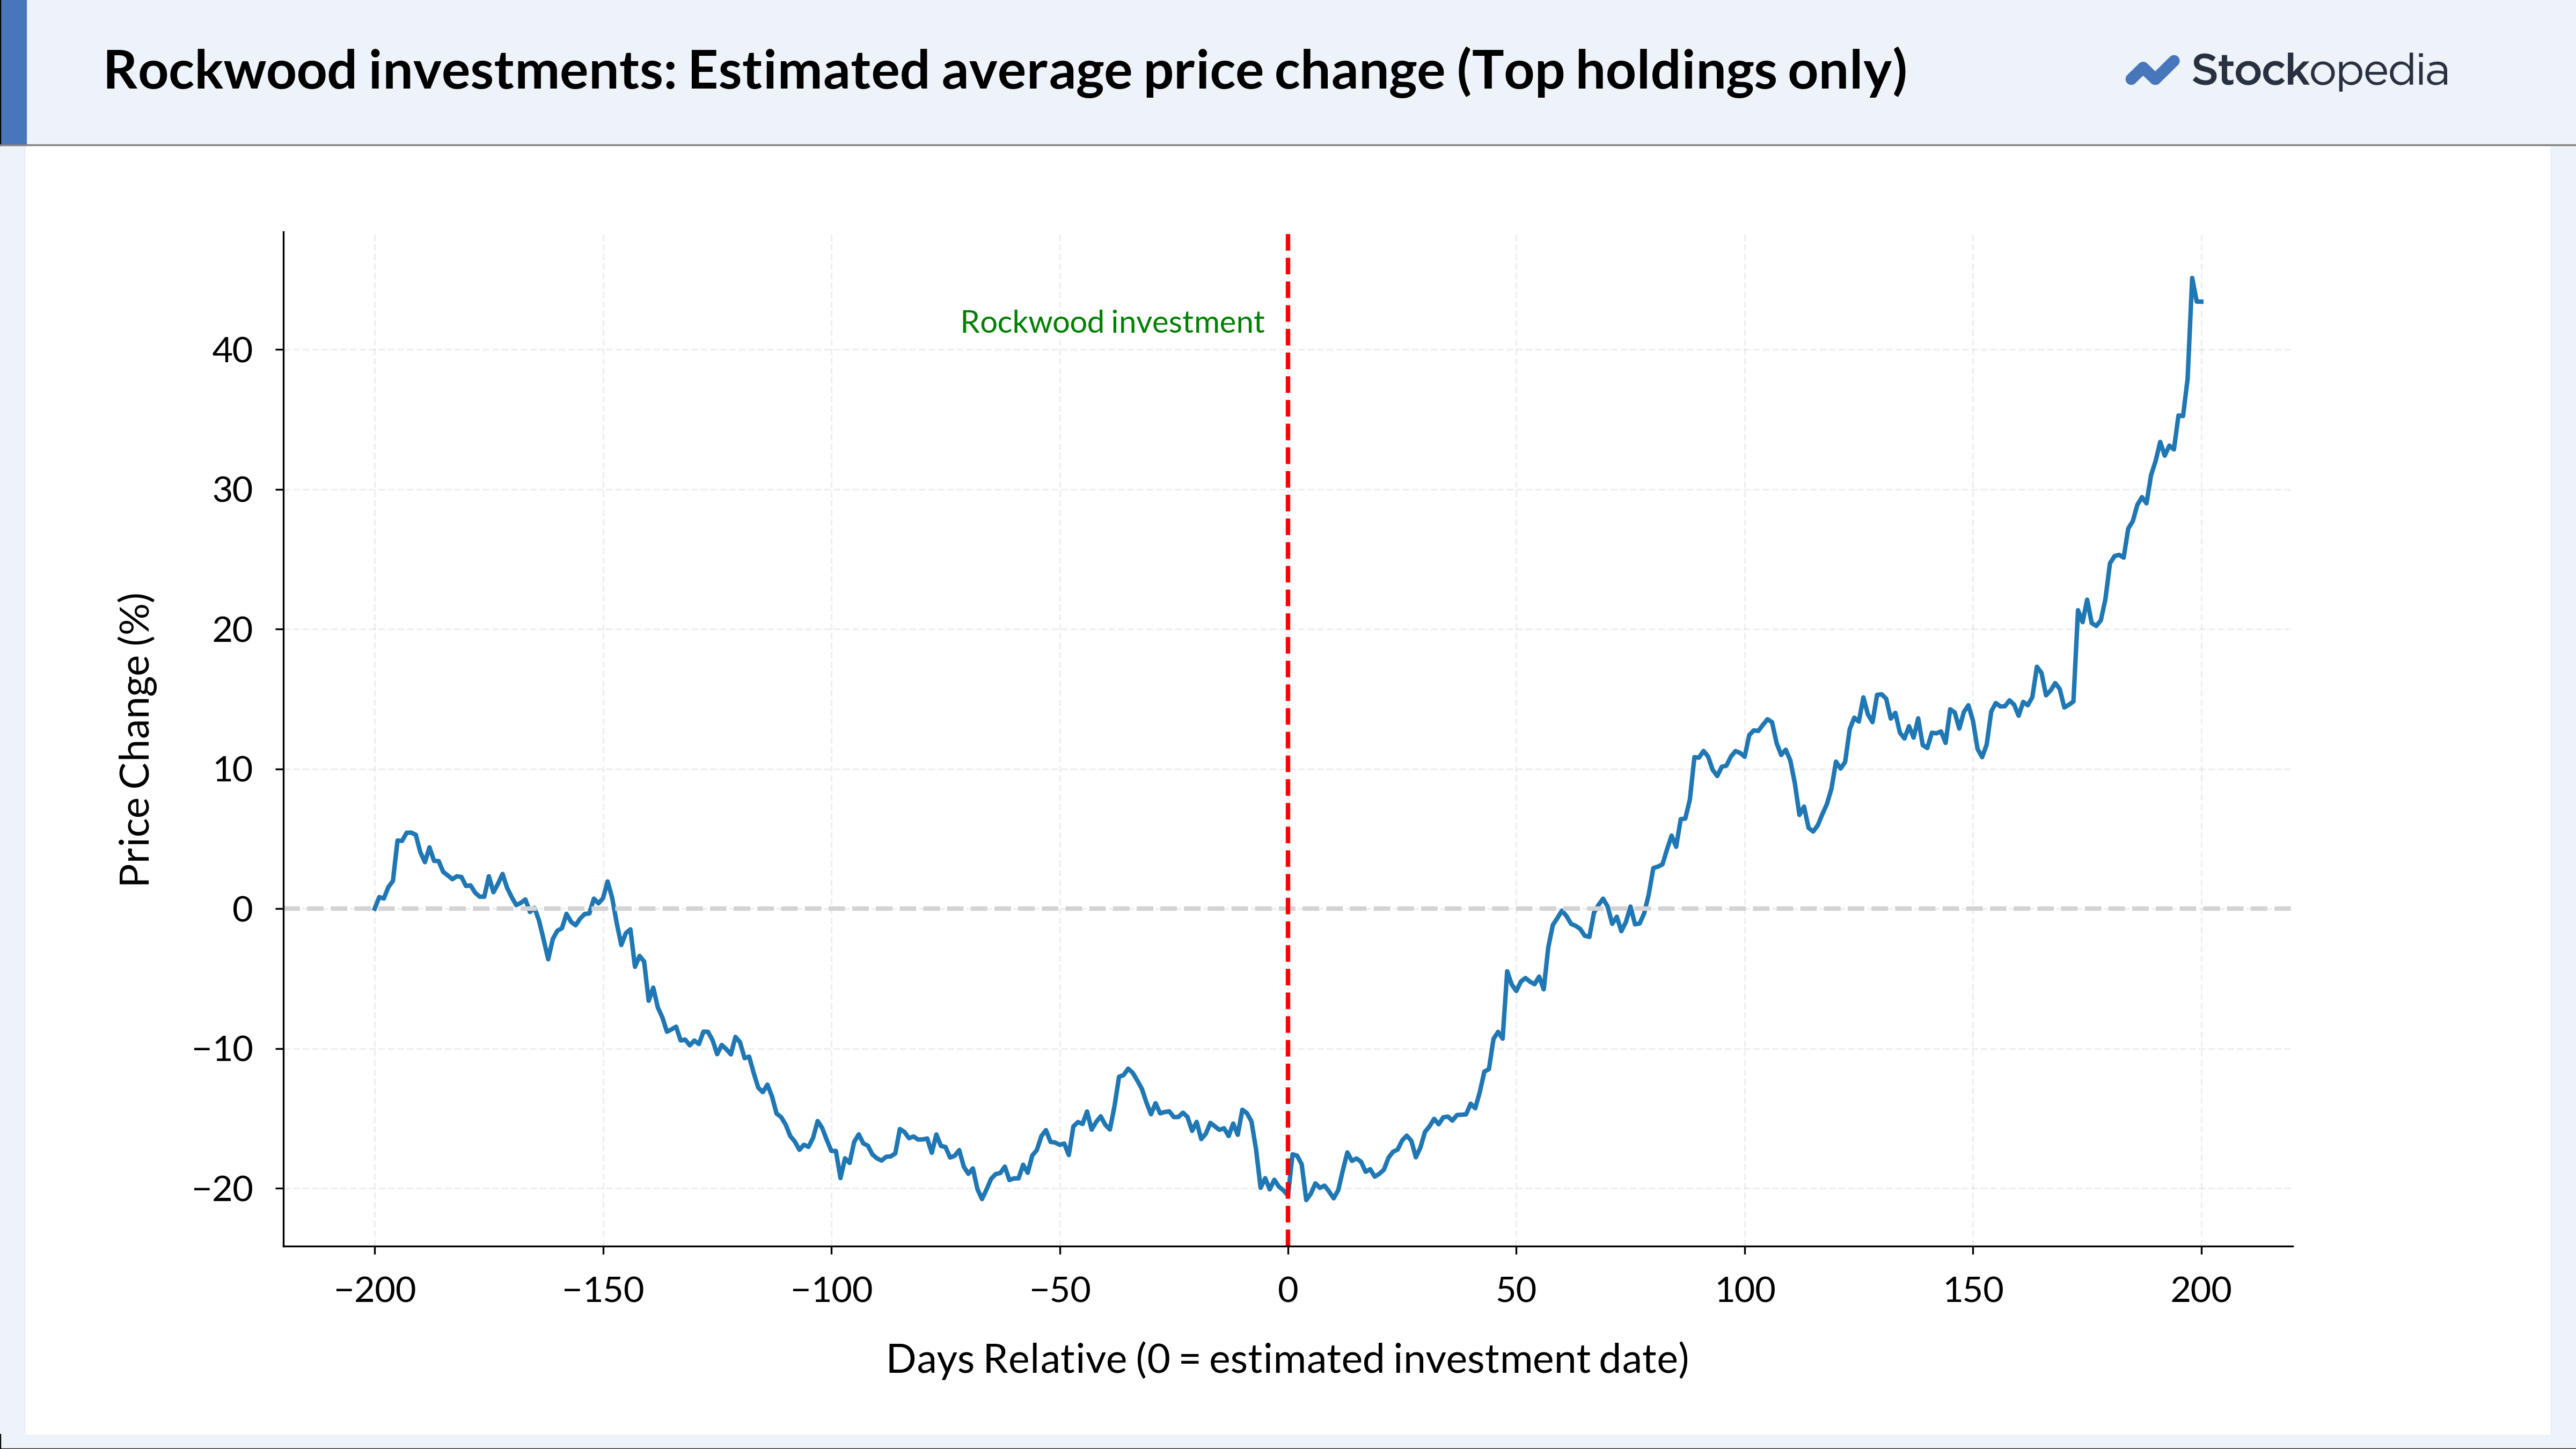
If you follow the crowd, it’s possibly too late. Perhaps it’s better to move before the bandwagon takes off. This suggests an alternative timing trigger: rather than waiting for the market to move, we can validate an investment thesis by checking that the smart money has started to buy. This allows us to replace the wisdom of crowds with the judgement of institutional investors, who are arguably more informed and better skilled at interpreting stock information.
The above chart is constructed from the performance of Rockwood’s largest holdings, so the data may be subject to survivorship bias. Nevertheless, research suggests that stocks tend to rise after smart money begins buying. Nofsinger showed that stocks with large increases in institutional ownership beat those with large decreases by over 30% per year.
Spotting Opportunities when Earnings Collapse
Rockwood focuses on turnaround plays. They look for shares ‘where the Company is benefitting, or will benefit, from operational, strategic or management changes.’ Before turnarounds recover, the fundamentals need to be bad in the first instance. Accordingly, Rockwood look for ‘mean reversion potential’ in terms of profitability. When Rockwood starts building a position, the company’s earnings trajectory is often negative. For example, Rockwood targeted RM Group after ‘a recent collapse in profitability’.
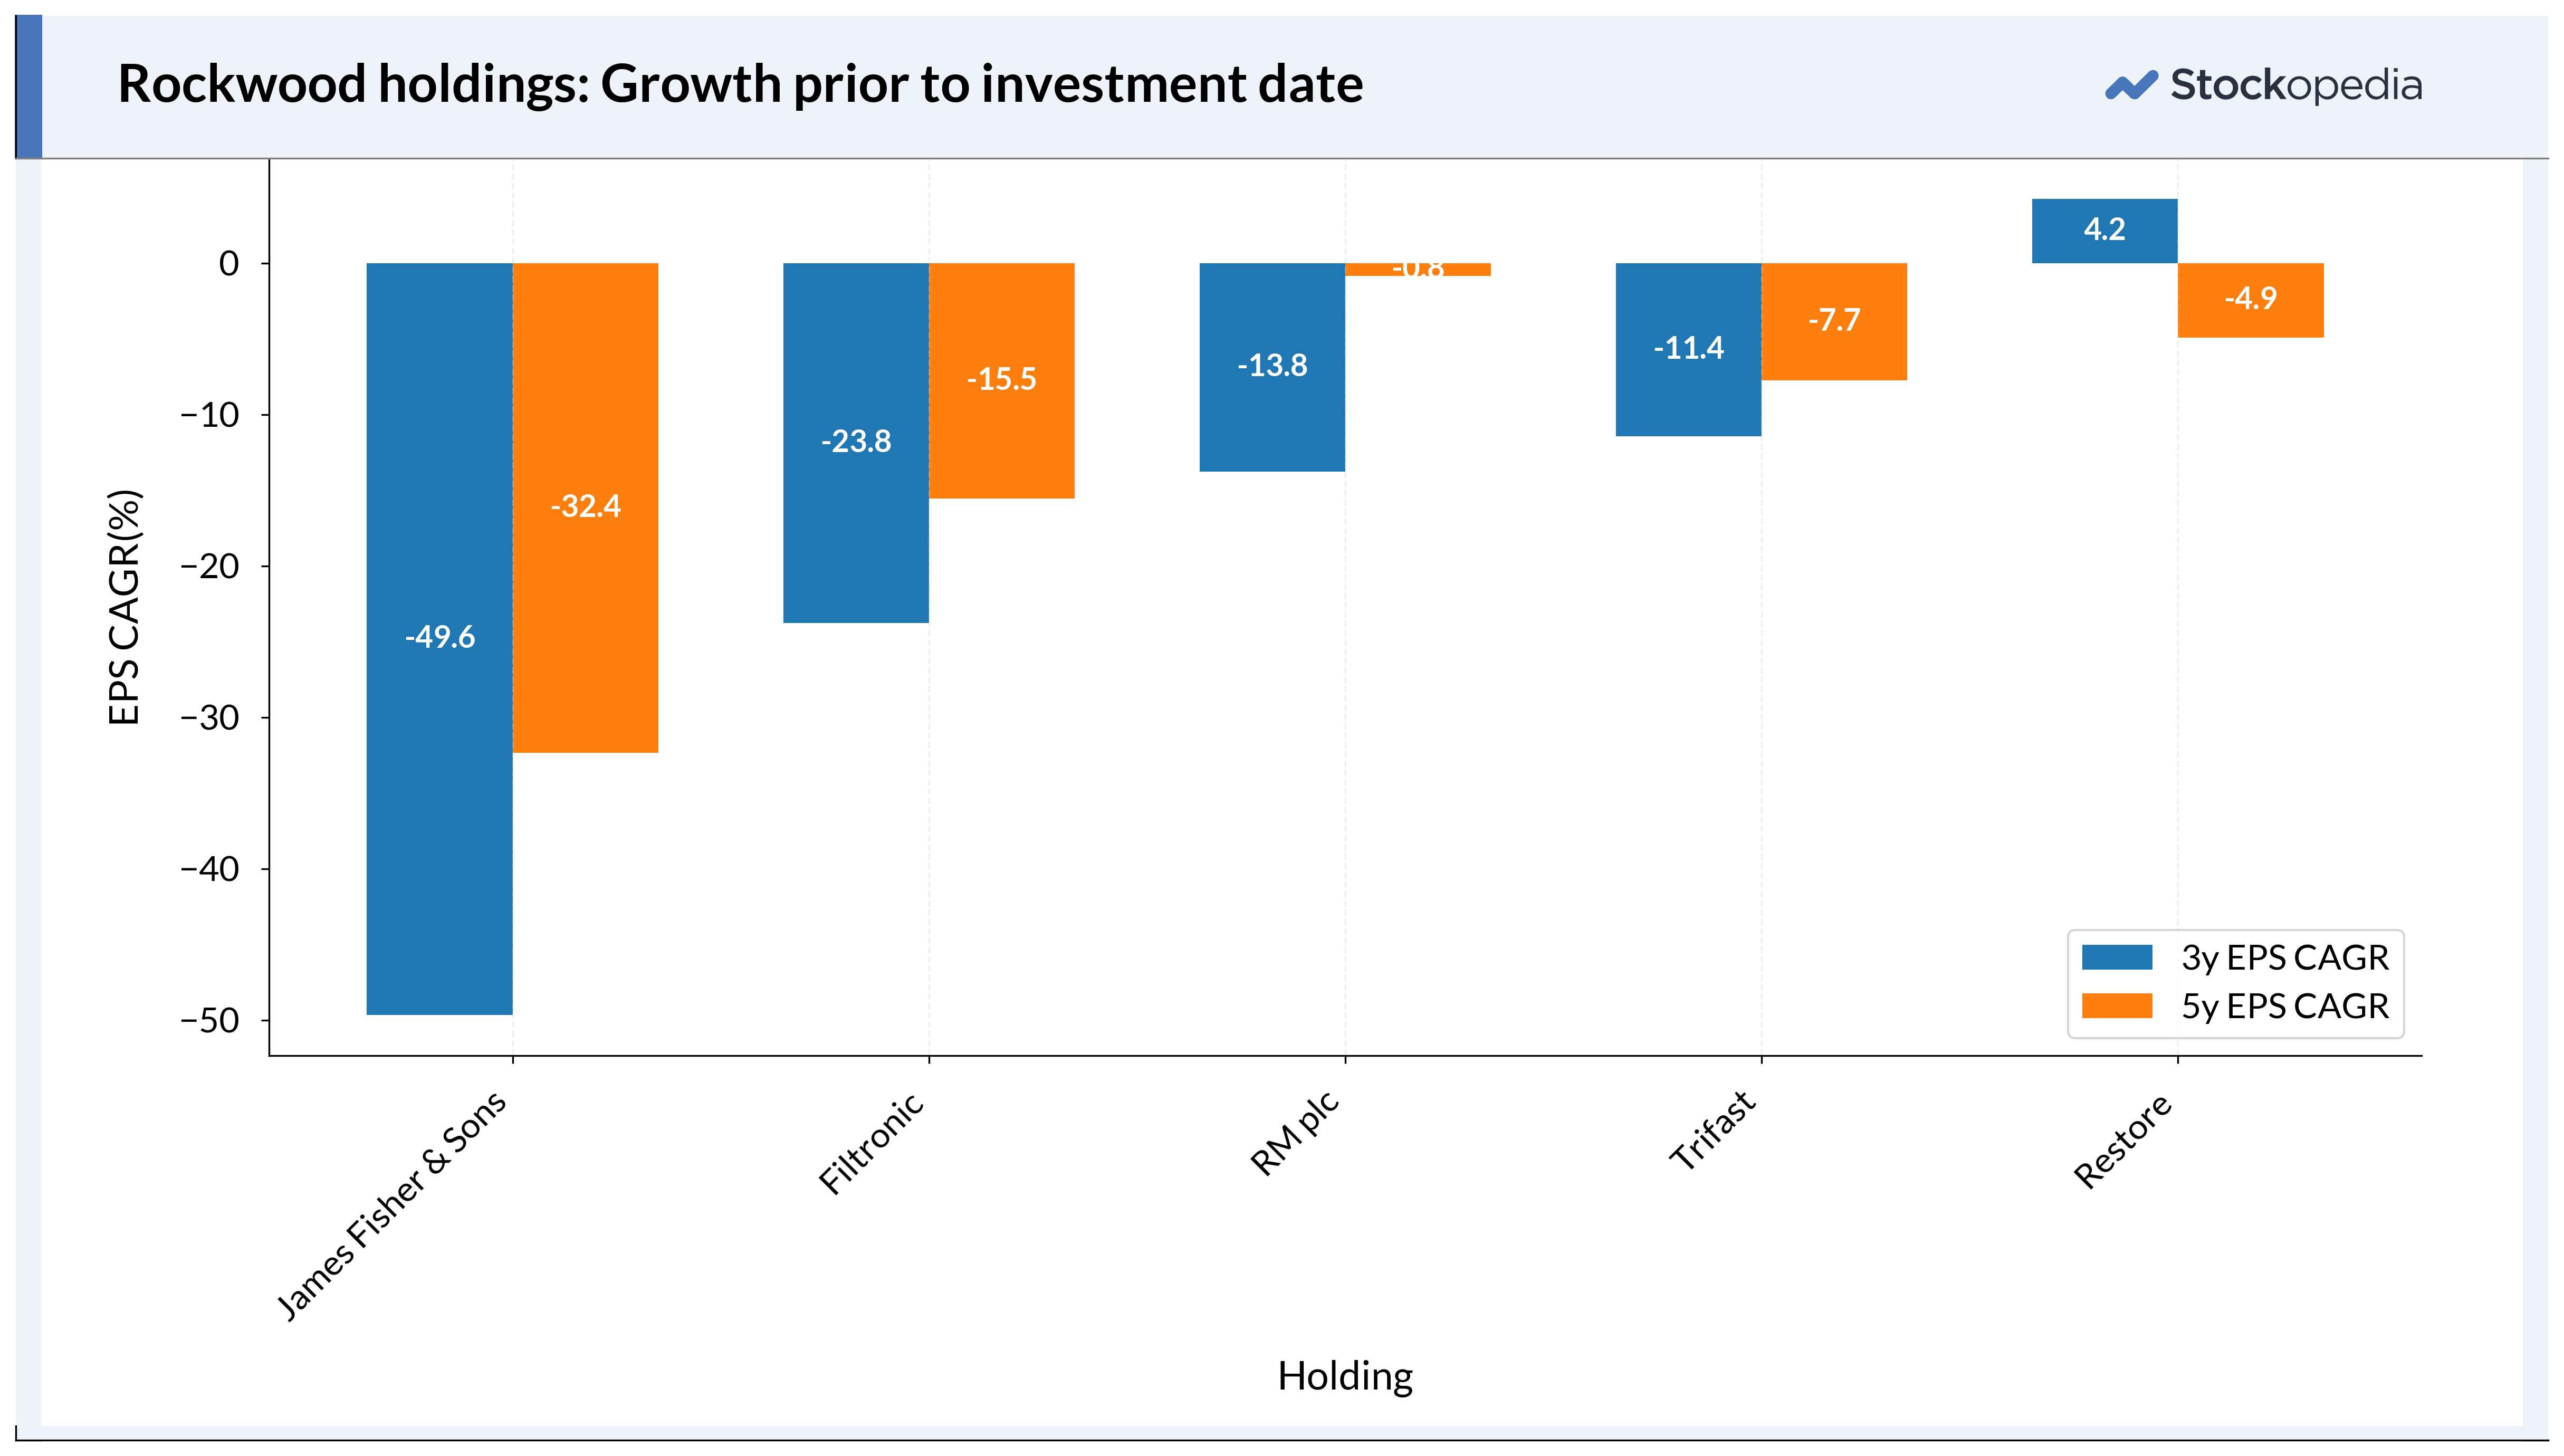
Of course, the plan is that earnings will bounce back. This leads to our next question: how confident can we be the smart money is actually right? Let’s explore this further…
Ride the “Piotroski Wave”
How can we quantify the extent to which a company is going through a successful turnaround? This is where the Piotroski F-Score becomes useful. This metric analyses fundamental momentum - whether fundamentals are improving across areas like profitability, cash flow, and balance sheet strength.
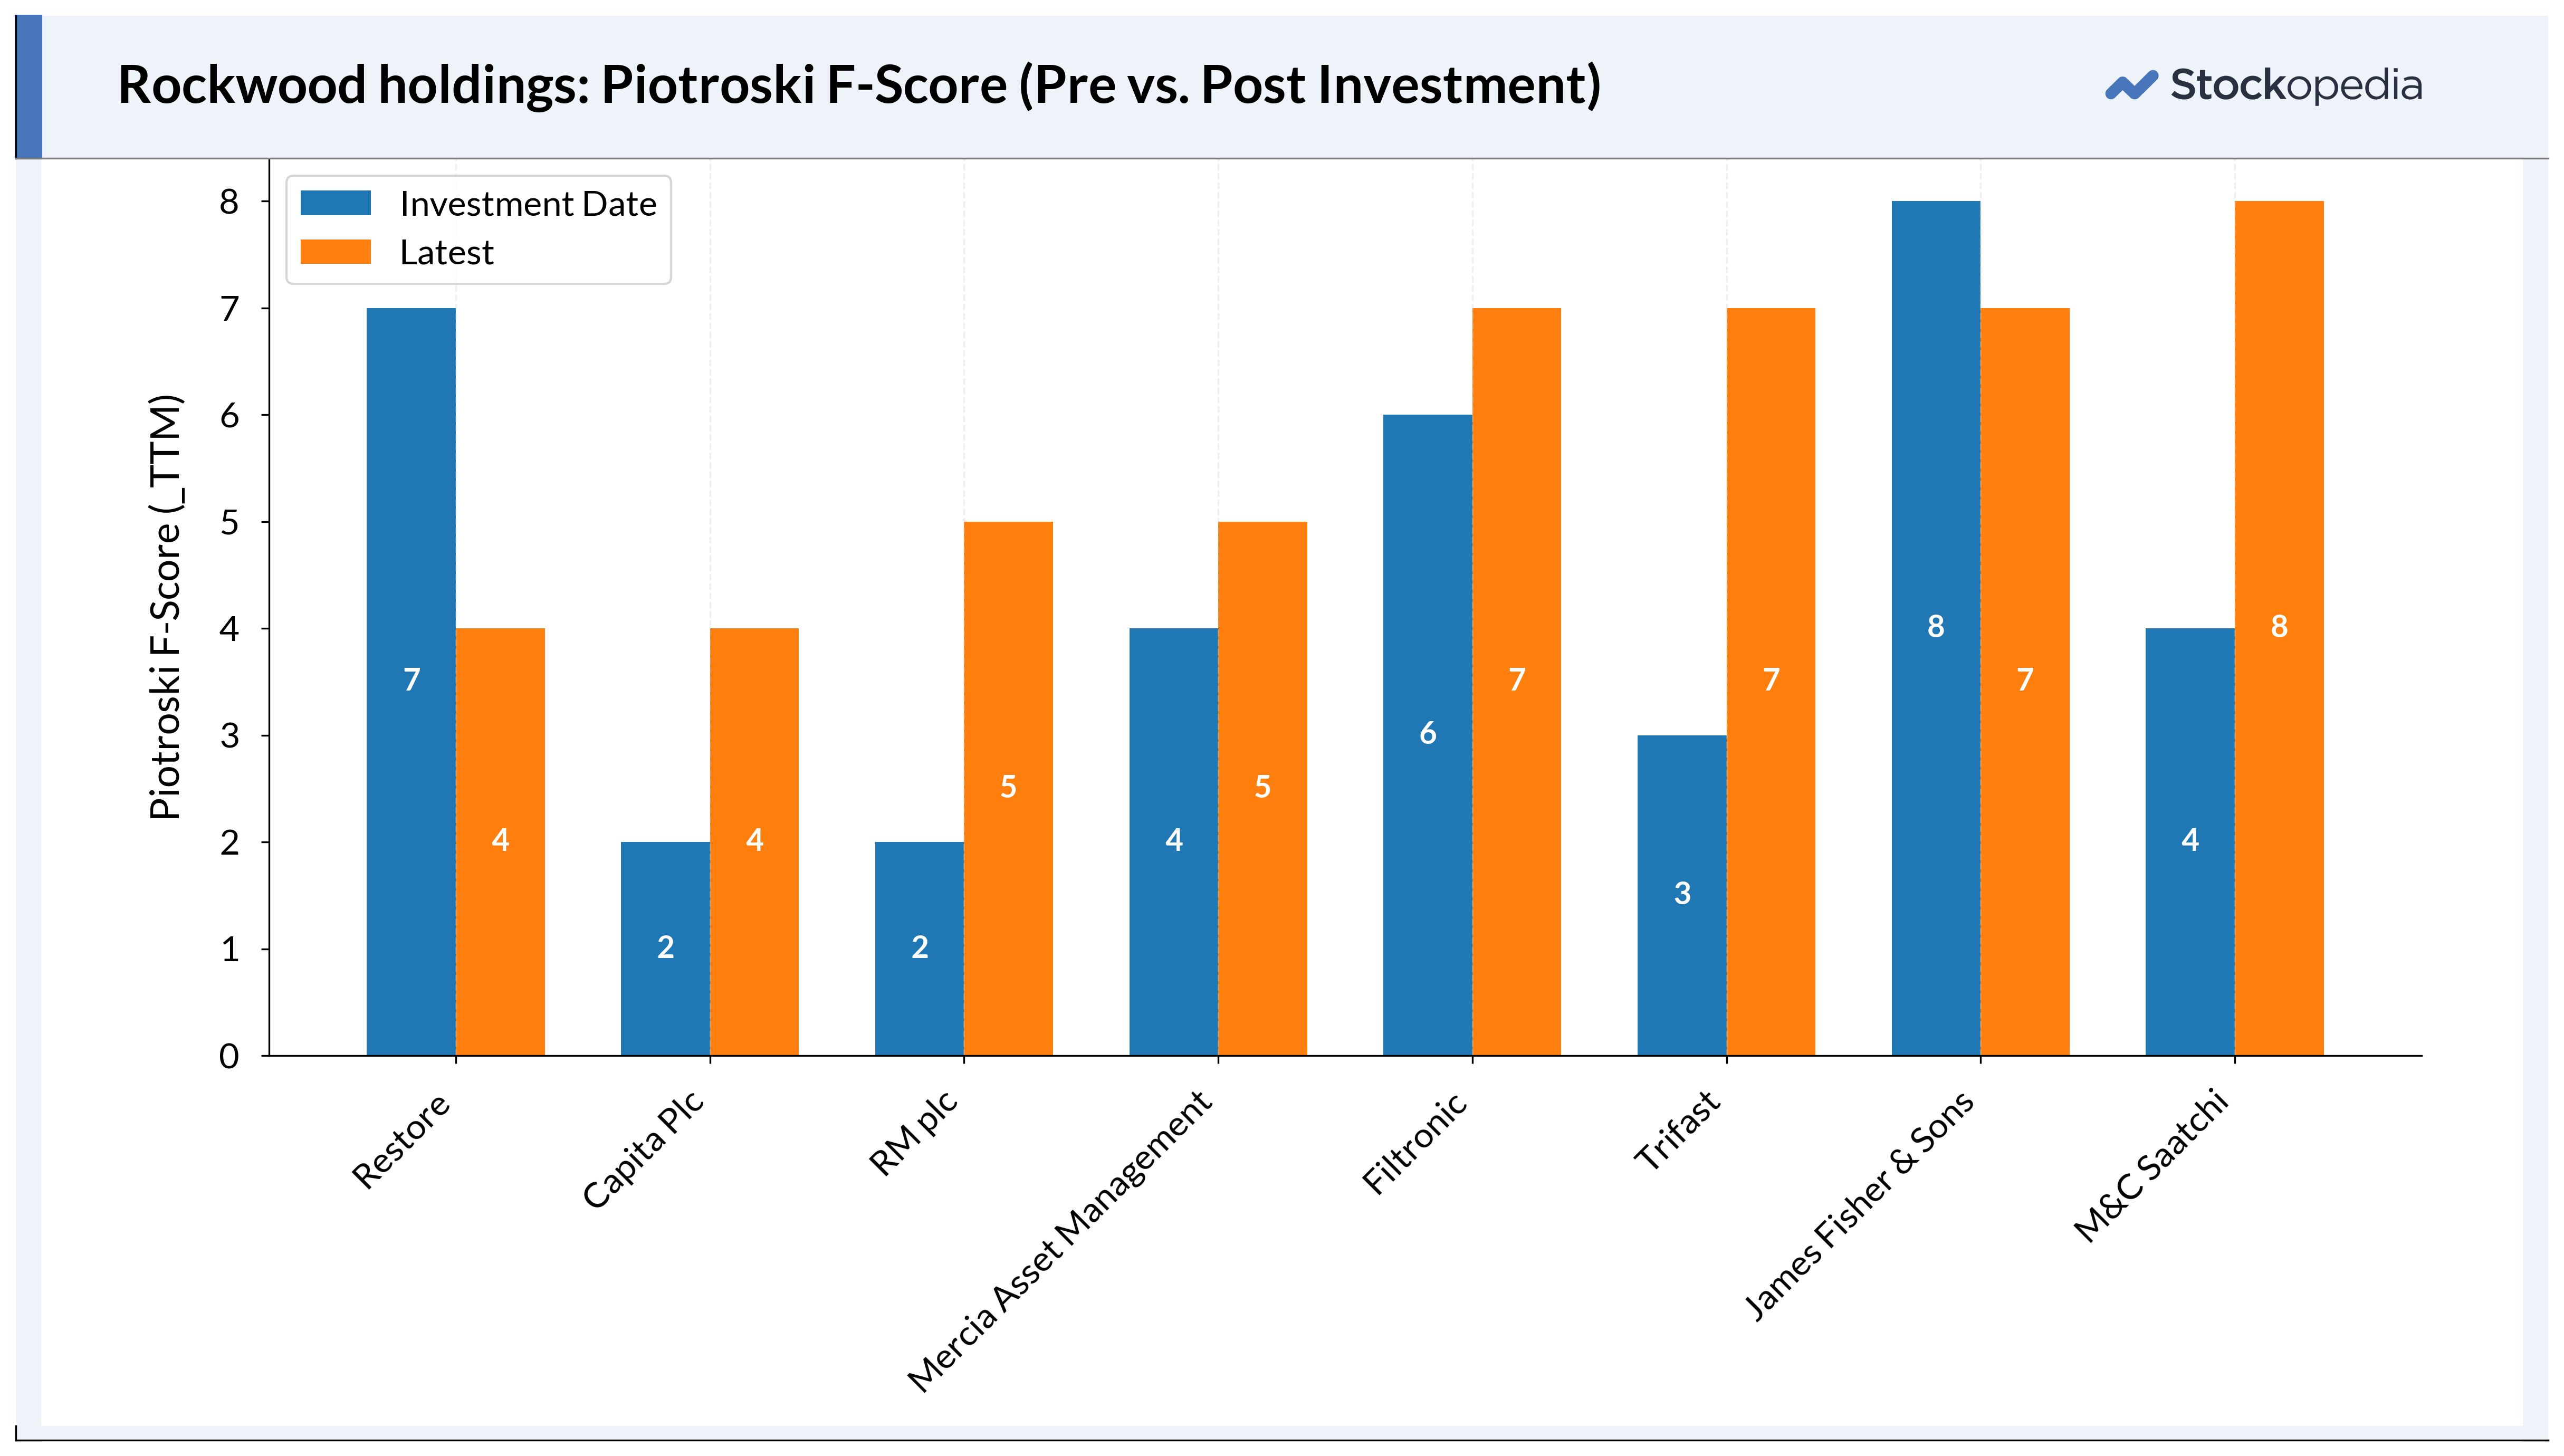
It is not clear that Rockwood use the Piotroski system. However, Rockwood’s investments do sometimes follow a ‘Piotroski wave.’ They tend to start buying when fundamentals show little or no improvement —when the F-Score is low— then the F-Score and share price rise in tandem as the turnaround takes hold.
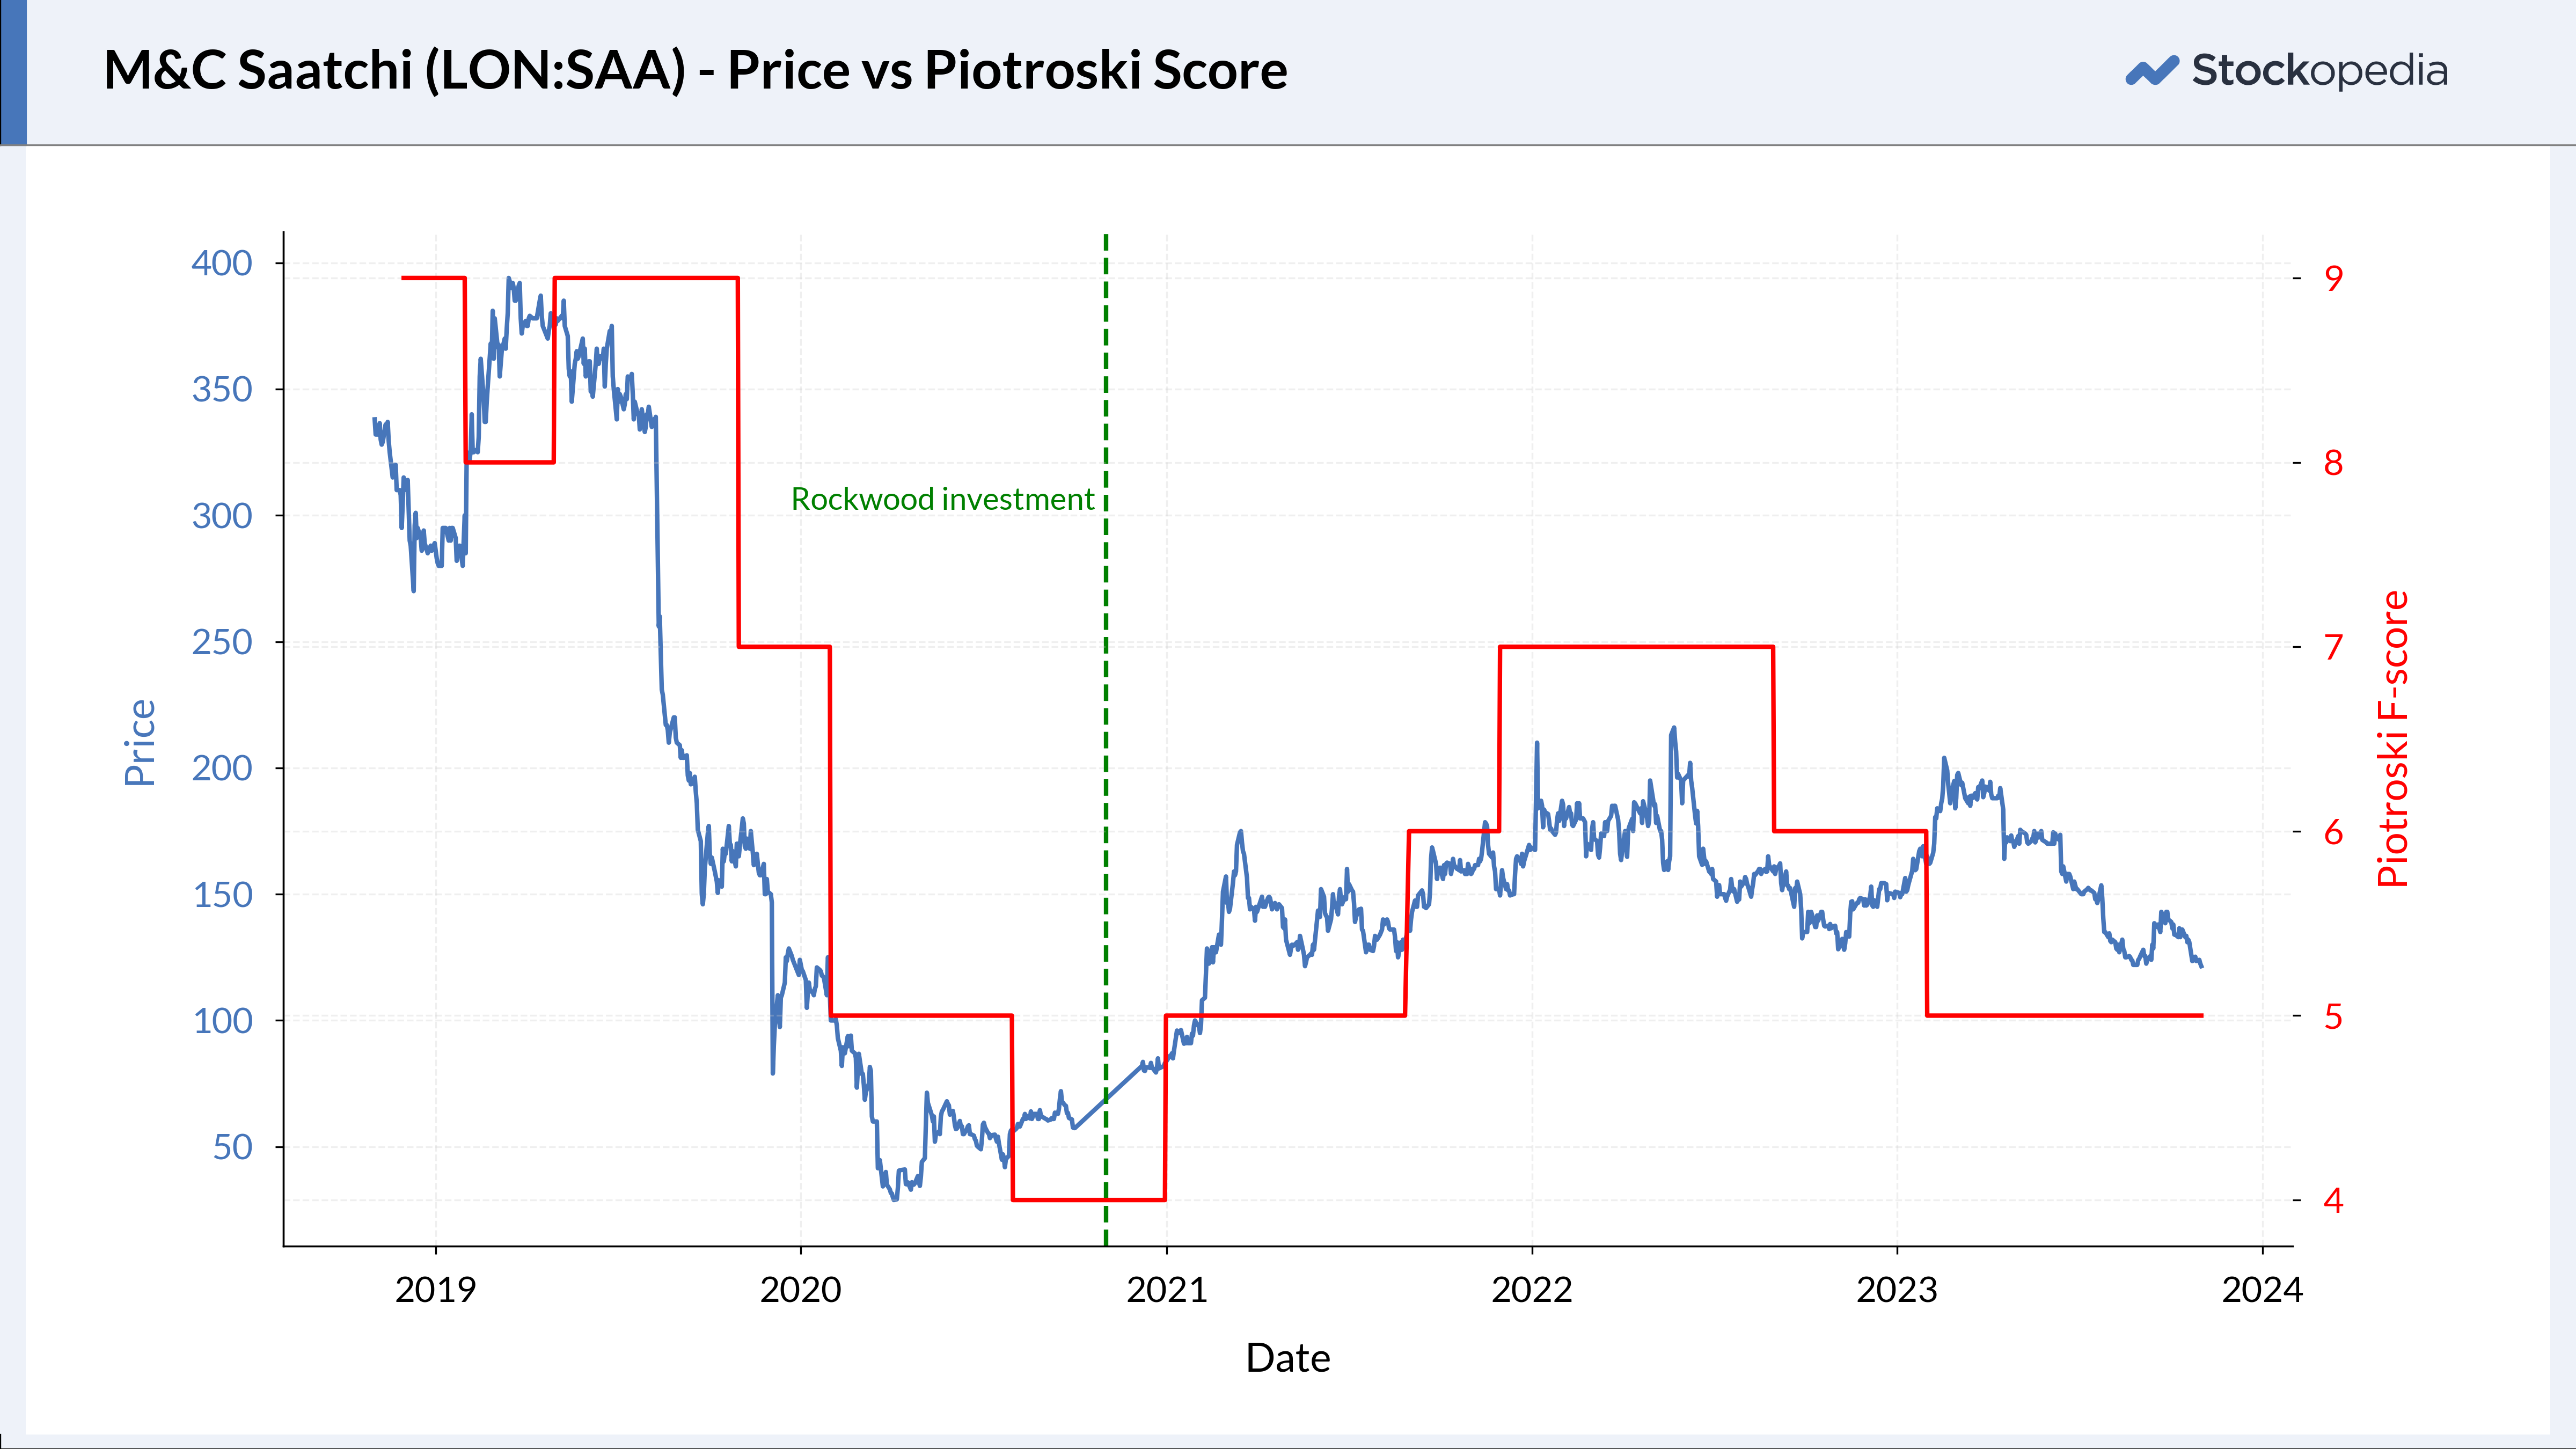
Rockwood has often taken a company with a low Piotroski score and turned it into a company with a higher score.
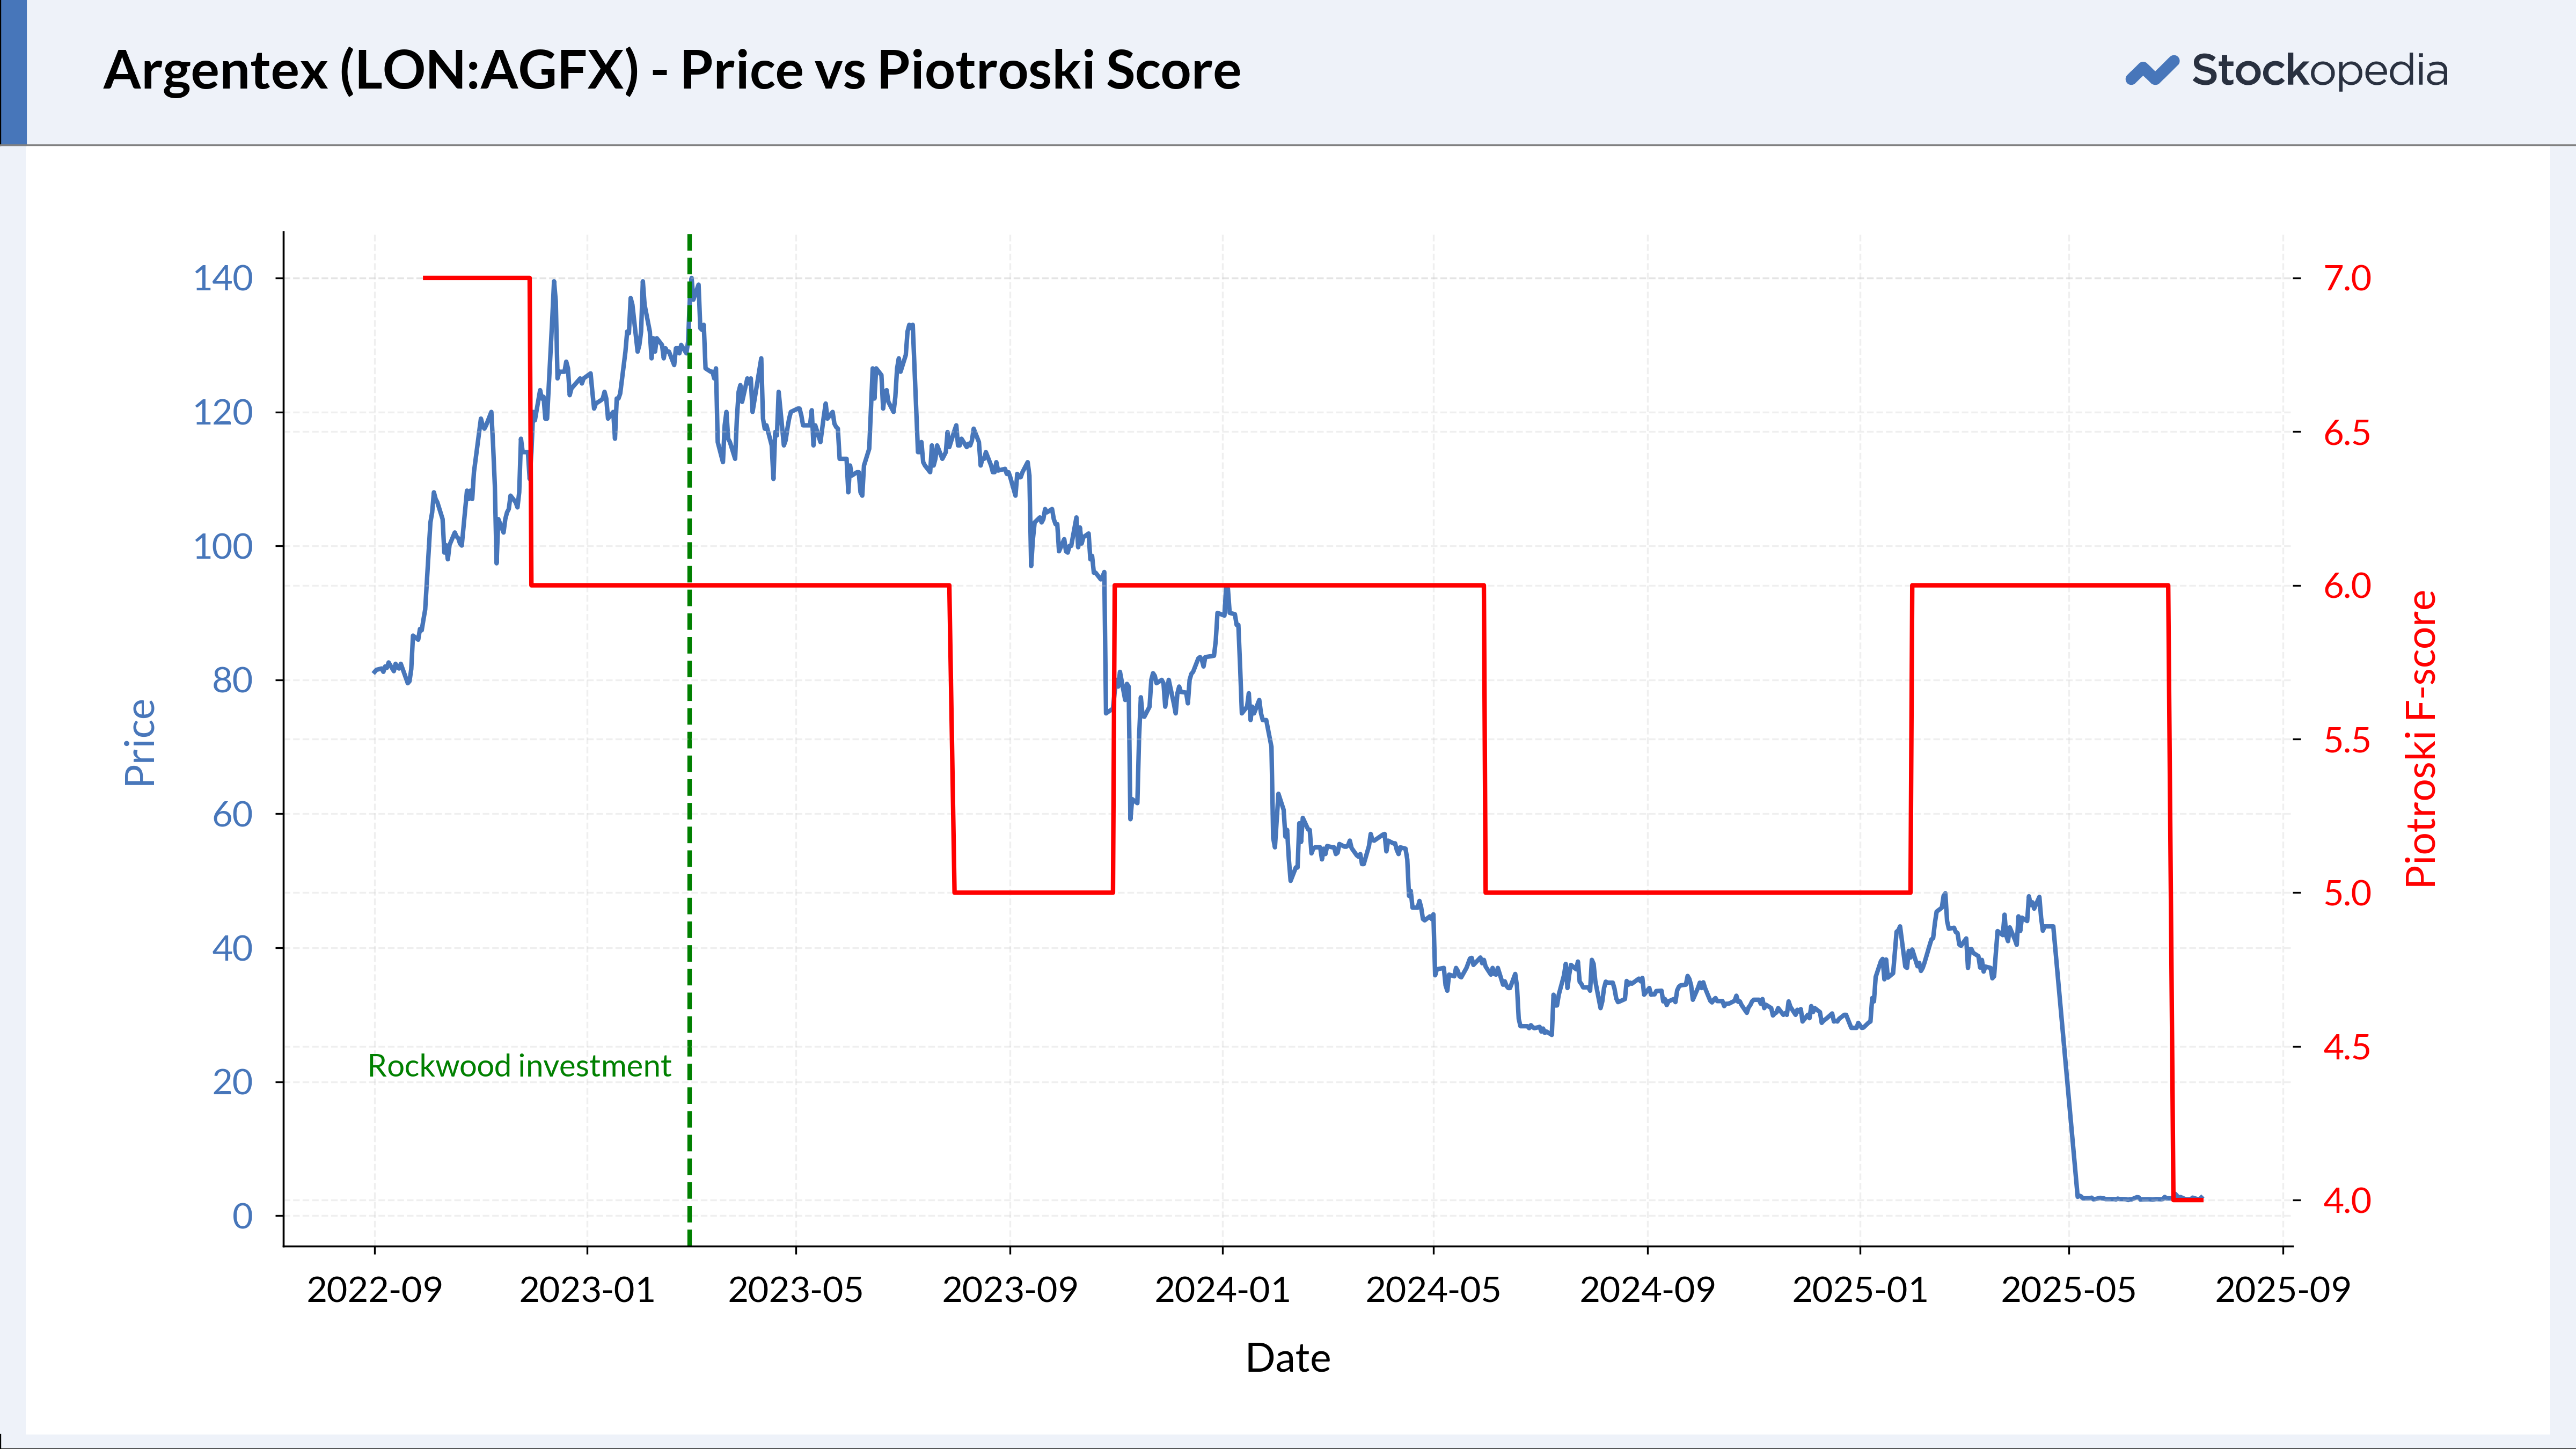
But it doesn’t always work. For example, Rockwood made an investment in Argentex just before March 2023. By 2025, they stated Argentex ‘has been a total write-off.’ The company is now delisted. We can see that the Piotroski F-Score deteriorated steadily, from 7 in 2022 to 4 in 2025. The fundamentals never turned around. They got worse!
A Qualitative Ingredient
The criteria discussed so far are quantitative, but Rockwood also considers qualitative factors. There must be a compelling story explaining why they believe a company will improve. Let’s look at examples from their financial statements.
M&C Saatchi — the operational turnaround story
Rockwood believed Saatchi could undergo a genuine operational change with a stronger management team in place. Their March 2025 report painted a detailed picture:
The business has been making considerable operating savings, disposing of loss-making operations and streamlining the business, including the move to shared services. Results demonstrated the turnaround is well underway unveiling a growing, high margin, low capital intensive, highly cash generative, international business… We believe the company is now in a position to undertake share buybacks and should be actively seeking to release and demonstrate, value for shareholders.
Filtronic — the catalyst-driven story
In a similar vein, Rockwood’s interim report from 2024 discussed Filtronic’s management changes and transformative new business:
In April their [Filtronic’s] trading update significantly upgraded 2024 and 2025 market expectations. This coincided with the SpaceX strategic agreement which resulted in material new orders for the group from the Starlink satellite network… Clearly a strong position for the new CEO to arrive to.
Quantitative screens can identify candidates, but the qualitative story, management changes, strategic shifts, operational improvements, determines whether the turnaround thesis is credible.
Wrapping It Together
The strategy we outline above -that follows Rockwood’s buys- is built around three key elements.
- Start with value. Look for companies trading below their historic valuations, not arbitrary thresholds, but cheap relative to their own history.
- Time entry using smart money. Smart-money purchases can act as early buy signals, giving insight into institutional judgement before the crowd catches on.
- Follow the fundamentals — and the story. Track improvements using metrics like the Piotroski F-Score, but also consider the narrative behind the company. Management changes, strategic shifts, and operational improvements provide the qualitative context that explains why the numbers should improve.
The Next Step
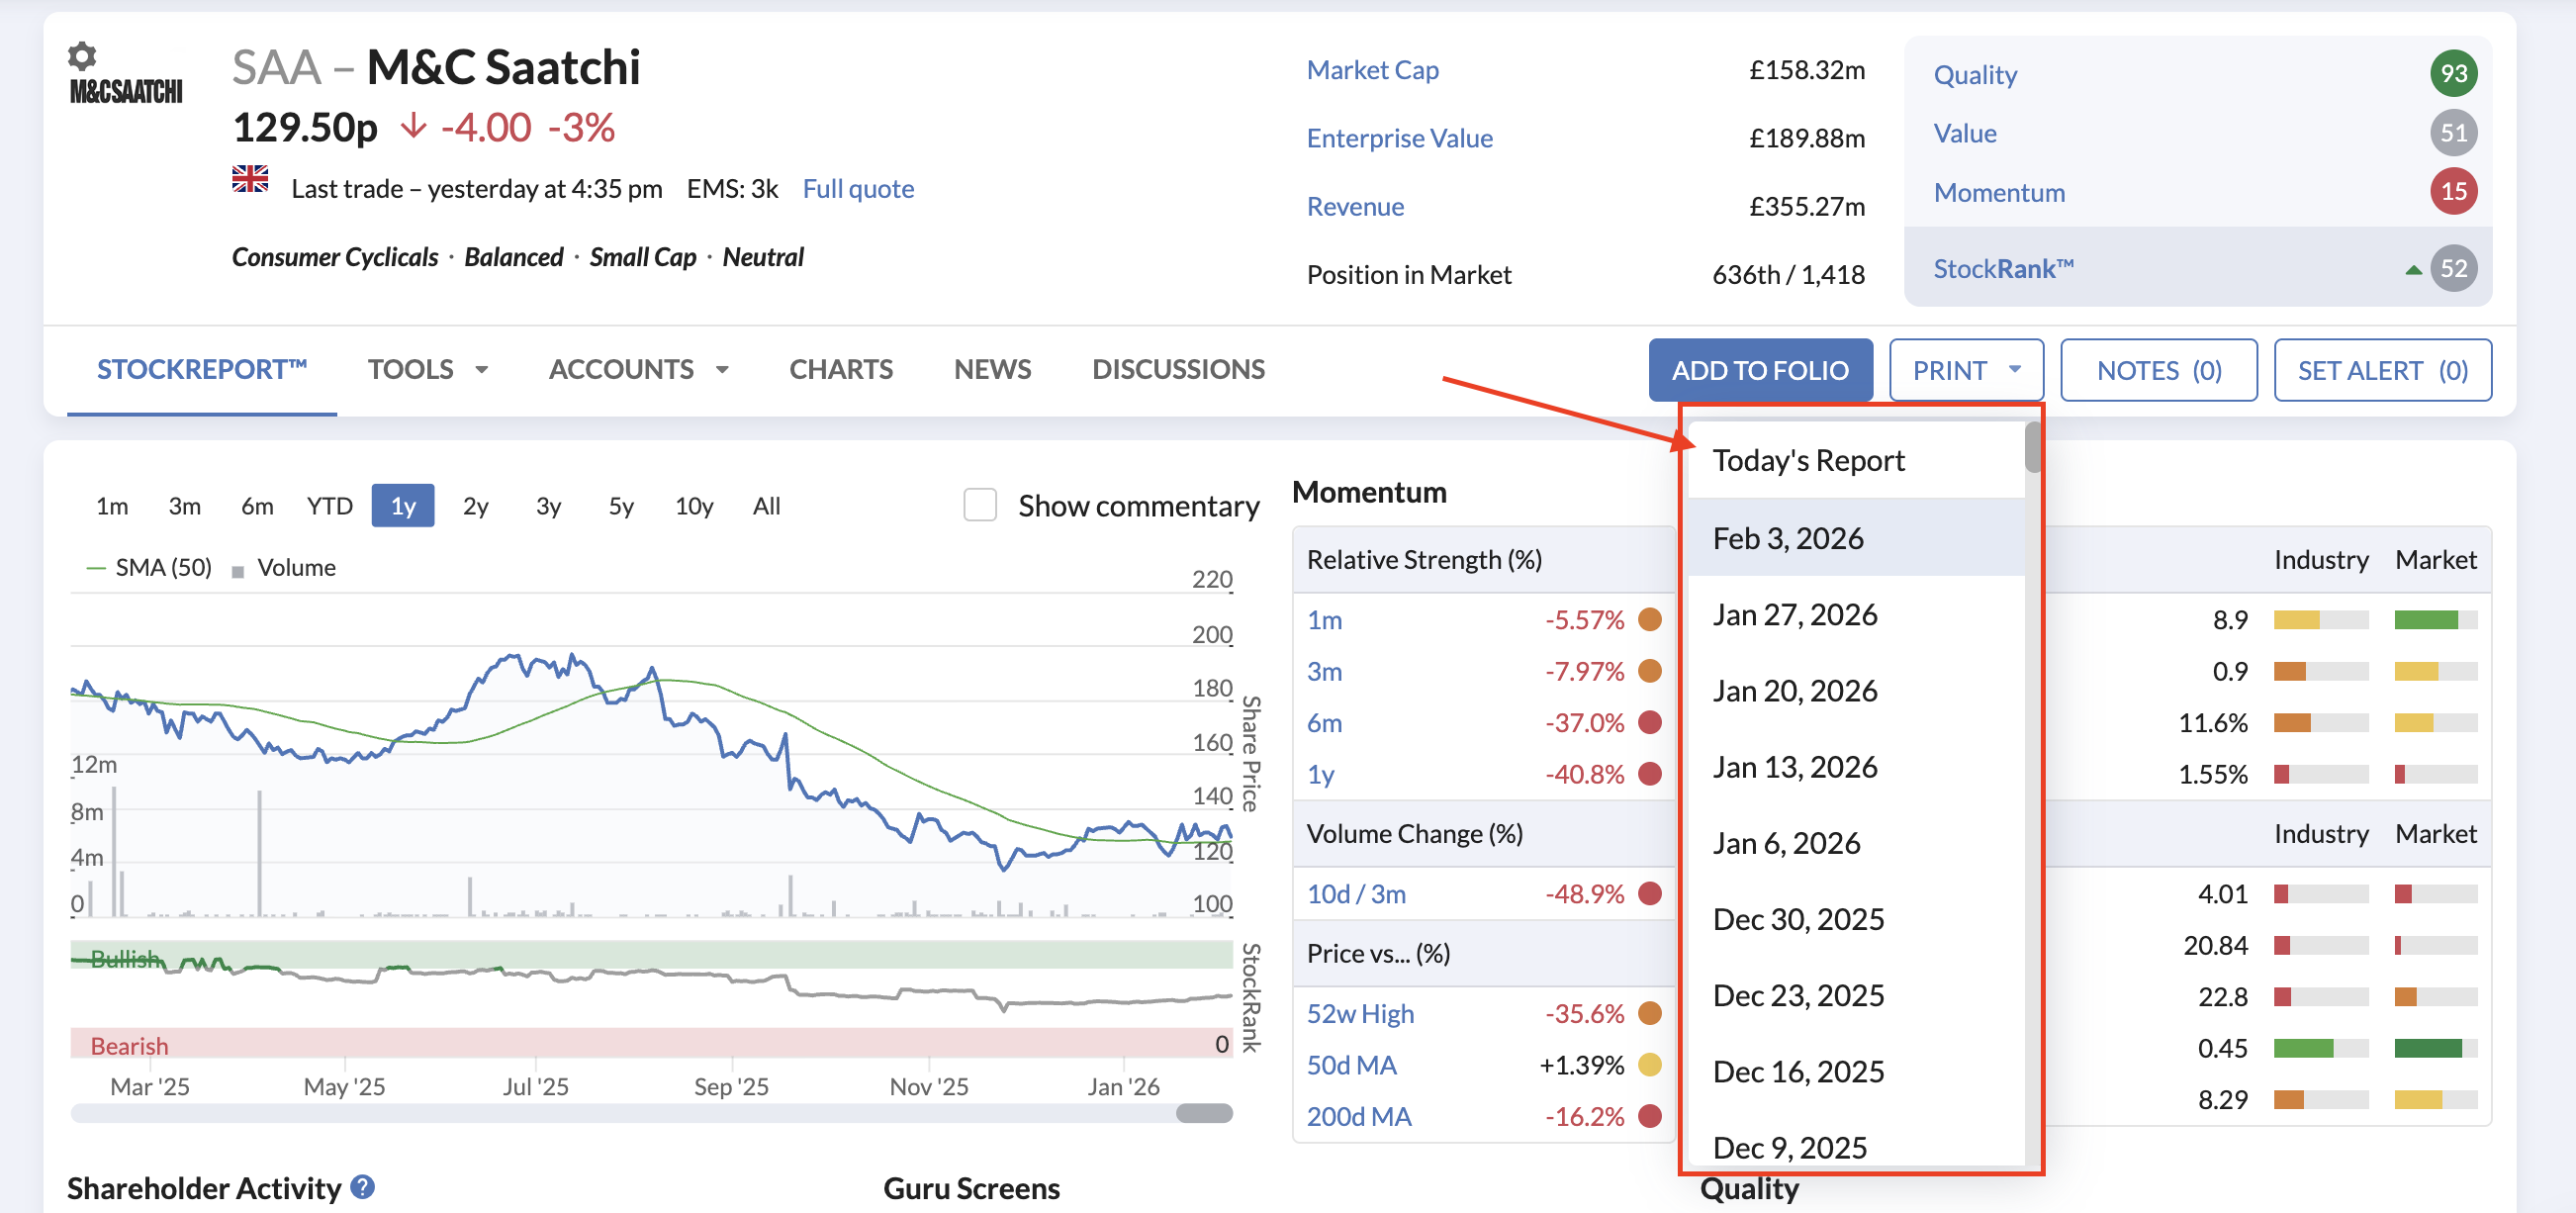
Feel free to review our StockReport, where we show whether institutions are buying or selling. Look out for green (positive) numbers in the “Change” column — these signal institutional accumulation and in some cases can serve as the timing trigger discussed above.
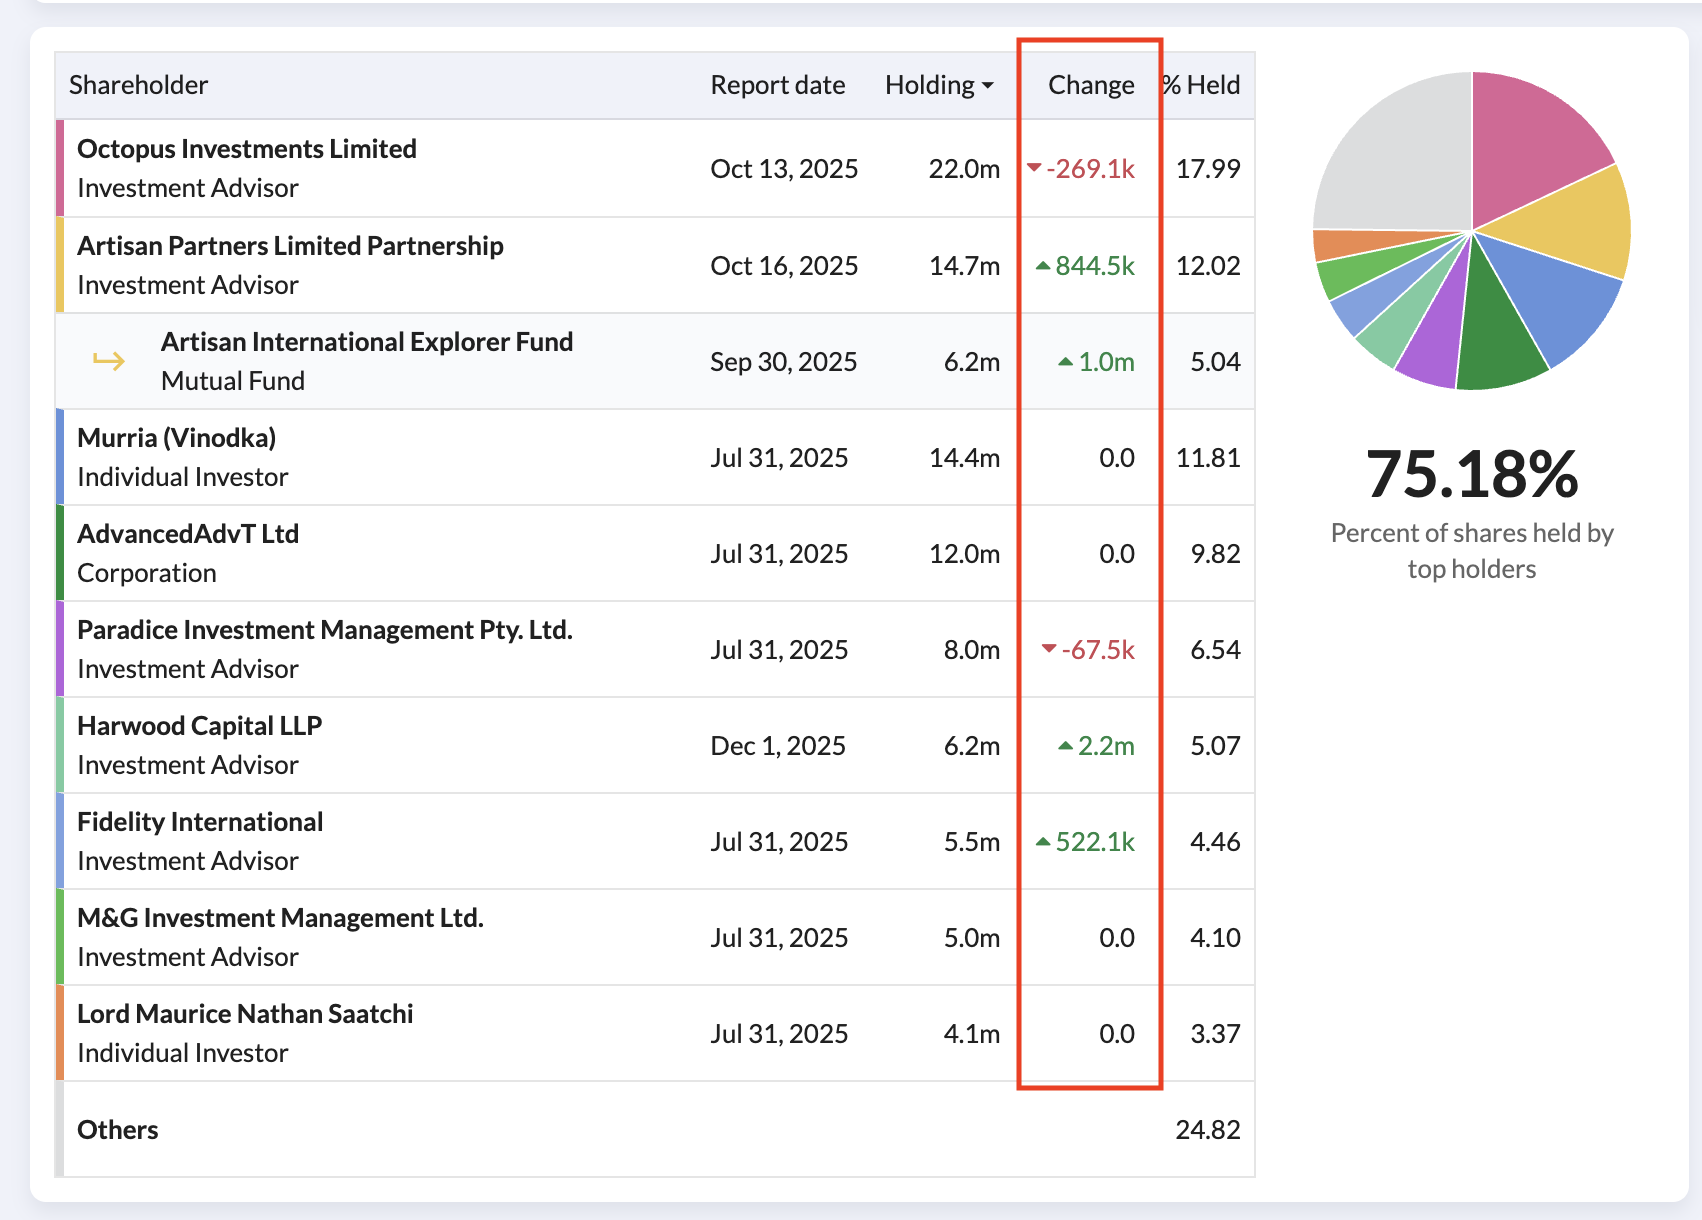
Furthermore, feel free to view the historical StockReports, in order to see how the Piotroski-F Score and other ratios evolved over time.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
Alex, useful piece. Many thanks. May I ask how you generate a chart of Price vs the Piotroski F Score in Stockopedia
Hi, Thanks for this. We keep the historical StockReport figures in a database. I cleaned the historical data and presented it in the charts/analysis. There is a longer-term aspiration to make charts like this available in the product.
Bang on timarr. If the author had taken the trouble to listen to any of the many available podcasts with Richard Staveley the Fund Manager it would be abundantly clear that they are sum-of-parts value investors where there is a potential catalyst to out value and I can be confident that Rockwood does not use the Piotroski system.
M&C Saatchi (LON:SAA) yet shares are down around 35% in the last 6 months.
The estimated average price change chart is impressive.
But if you only include (undisclosed number) of top holdings and exclude anything not 'top' then it's not a case of the data may be subject to survivorship bias. --instead it's the definition of survivor bias. Everyone's portfolio goes up and right if we just look at the top returns - so I find the chart very seductive but ultimately misleading and useless..
Rockwood have good results and excellent PR but keep very quiet about their bottom quartile.
Rockwood Strategic (LON:RKW) has performed well but the other Harwood funds have not fair well. A lot of comments apply to all of them.
So is the fund manager the main difference?
Vin Murria tried buying M&C Saatchi (LON:SAA) a few years ago via her investment vehicle AdvancedAdvT (LON:ADVT), together they hold over 21% of the shares. Pretty smart cookie. She also bought a number of software businesses fromCapita (LON:CPI) of which Harwood has a stake in
Rockwood don't target turnarounds, they create them.
Their playbook is to find companies they believe have been badly managed, replace the management and recapitalise the business. They're activists - you can't screen for this, many of the companies they help turnaround have been struggling for years.
timarr
Very informative. The key issue is how current is the information. The CEO of CNS bought 130k shares in the last few days and Rathbones increased their holding in FAB hence its SP rx. Neither off these are in the data....yet. Things can move fast!
The CEO buy was in News at 8.30am yesterday
Thank you Rudy. They are in the data. It was just me locating them and I continue to learn how to access all the data available.