S4 takes a tumble as AI capex eats into marketing budgets

Analyst’s view:
Q4 revenue numbers must be shaping up very poorly, given the new revenue guidance, with the company potentially entering 2027 from a position of weakness. We were neutral on this in August when Roland took a prudently cautious stance at a market cap of about £260m, and I'm inclined to leave us on neutral today. Based on the latest share price, I believe the PE ratio is currently 7.3x. I view this as a fair multiple - maybe even a generous one - for a business that is still carrying some debt (£50-80m at year end targeted), is in a state of revenue decline, and has a poor track record of profitability.
Down 17% at 44.5p (£298m) - Third Quarter Trading Update
The market reacted strongly to this update, focusing more on the negative revenue guidance rather than EPS guidance.
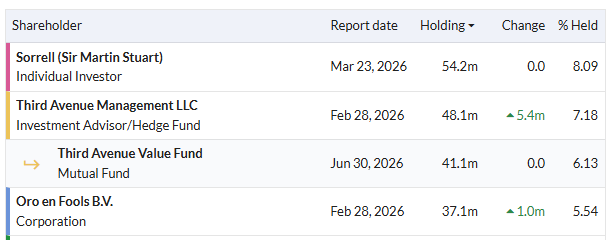
S4 is Sir Martin Sorrell's advertising business, founded in 2018 after he left WPP (LON:WPP). He remains the largest shareholder:
Today's Q3 update from S4 doesn't read so badly to me, given that the market was already expecting a hefty revenue decline this year. Key points:
Q3 net revenue down 6.4% (down 7.3% like-for-like)
Year-to-date net revenue down 6.2% (down 5.6% like-for-like)
Net debt is £76m, a big reduction year-on-year and "significantly better than anticipated". It is a higher debt load than the company reported for June (£66m).
The guidance is where the disappointment lies:
2026 full year like-for-like net revenue now estimated to be marginally below previous guidance down high-single digits, with operational EBITDA remaining at current analyst consensus level of £85 million and operational EBITDA margin now estimated to increase by at least 160 basis points to 13.7%
Adjusted basic earnings per share is expected to be in excess of current analyst consensus of 6.1p per share
Previous guidance, given in the interim results, was for like-for-like net revenue down "mid-single digits".
Thinking in numbers: we are probably now heading for a 7-9% LfL revenue decline.
This doesn't bode well for Q4 given that year-to-date LfL revenue is down by only 5.6%, up to and including Q3.
Comment from the Executive Chairman:
"Throughout the third quarter, our trading continued to reflect increasingly volatile global macroeconomic conditions, heightened by rising geopolitical risks. Clients remained cautious amid this uncertainty, with hyperscalers and other technology clients continuing to prioritise capital expenditure on expanding AI capacity over operating expenditure.
AI is touching everything - and its heavy capex requirements are even coming at the expense of marketing budgets.
But the news on profits and margins is not so bad. Sir Martin Sorrell also says that the company expects "operational EBITDA remaining at current analyst consensus level of £85 million and operational EBITDA margin now expected to increase by at least 160 basis points to 13.7%."
This is unchanged guidance from the interim results: even a little better than the interim results, when the EBITDA margin was seen increasing by only 140 basis points.
Graham's view
I'm always sympathetic to companies missing on revenues but hitting their earnings targets. The way I see it, companies sometimes have more control over their costs than they have over their revenues, especially in the short-term when macro conditions are unfavourable.
And given that EPS forecasts are technically intact, at least for 2026, I do not even categorise today's update as a profit warning.
But it's also true that the Q4 revenue numbers must be shaping up very poorly, given the new guidance, with the company potentially entering 2027 from a position of weakness.
As for our stance, we were neutral on this in August when Roland took a prudently cautious stance at a market cap of about £260m.
With a market cap of about £300m today, I'm inclined to leave us on neutral today.
Based on the latest share price, I believe the PE ratio is currently 7.3x. Looking ahead to 2027, I'll be curious to see if 2027 forecasts get cut on the back of today's update. The existing EPS forecast suggests that the 2027 PE multiple falls to 6.6x.
As Roland did, I view this as a fair multiple - maybe even a generous one - for a business that is still carrying some debt (£50-80m at year end targeted), is in a state of revenue decline, and has a poor track record of profitability.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on WPP (6)
Comments here are also visible in the Daily Stock Market Report
S4 Capital (LON:SFOR) (Ouch!!) (I hold). I asssume with improved EPS but a marginal drop in like for like net revenue, that this is an overreaction. I was anticipating a pull back as the price had crossed 50p but 14% down seems a lot.
S4 Capital (LON:SFOR)
I asssume with improved EPS but a marginal drop in like for like net revenue, that this is an overreaction
is it a overeaction though ?- what we dont know is what brokers will do with regard to next year stimates - will they look at revenue wobble and make chop to next years expected numbers ? if they do how much wil that chop be. So to me what is key is knowing what the detail is ref next year rather than this.
Note on face value you are right that the revenue miss seems to not matter alot they have advised they are ahead of prior expectations ref eps and debt so overall it all seesm pretty tidy - as ever thugh what is most important is whether next year will take a chop - its over to brokers to find that out though.
Havent looked at this share in detail recently but for thoise happy enough to ignore thne glory days it does seem to be regaining some of its former mojo - they certainly need decent period of proper clean profit generation though to put the past woes behind them.
Thanks excellent insights - I concede I have this in my portfolio based on Stocko's VM ranks for a second time now. I'm floating around even today but may see more losses.
Ouch indeed - look at the trading volume - already almost three times daily average.
Hunting (LON:HTG) another over reaction maybe as current situation WW has been known for months - so why so steep today - twice trading volume so far today!
time to spend more, good upside
The price had been coming back up a bit, I think there had been hopes that growth elsewhere would mitigate the Gulf problems. I think that is still true, but it takes time for these effects to work through. I hold.