Sector spotlight: new rules could bring new opportunities

Where are the cheapest stocks in the market today? For investors seeking dividends and value, I think it’s impossible to ignore the UK market’s large financial sector.
A quick look at Stockopedia’s sector listings tells us that in aggregate, the UK’s listed financial businesses are currently trading on what appears to be a value rating:
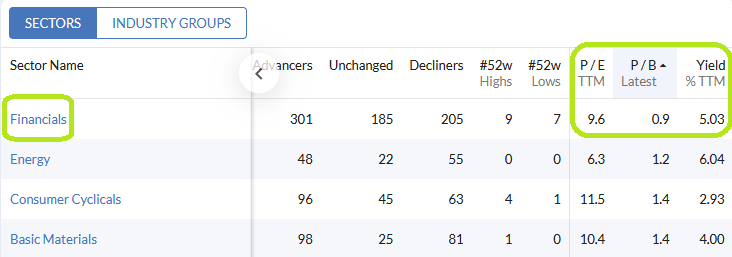
Indeed, the financial sector is currently the only part of the UK market that’s trading below its book value. The average yield of 5% is also the highest in the market, bar the Energy sector (which I plan to revisit in the coming weeks).
Arguably, book value isn’t as relevant to modern businesses as it once was. In an age where intellectual property and other intangibles often dwarf a company’s physical assets, book value isn’t always a reliable indicator of valuation.
Even so, when I see stocks trading below their book value, I often find it worthwhile to take a closer look.
A sector of many parts
According to Stockopedia, the UK’s financial sector contains 691 listed securities – nearly 40% of all the securities listed on the London market. For our purposes here, we can quickly exclude many of these. For example: preference shares, overseas stocks, and equity investment trusts.
To further narrow my focus, I’m only going to consider three industry groups within the financial sector:
Industry group | Latest P/B | TTM P/E | TTM div. yield | Median EPS growth forecast |
Banking services | 0.8 | 6.5 | 3.8% | 9.4% |
Insurance | 1.2 | 12.2 | 5.9% | 23.1% |
Residential & Commercial REITS | 0.7 | 7.2 | 4.5% | -38.1% |
These valuation metrics look pretty undemanding to me, especially given the positive outlook for earnings growth at banks and insurers.
However, it’s worth remembering that averages can mask a wide range of underlying values. Clearly, we need to have some understanding of the factors that are likely to influence profitability and valuations in these sectors.
Why I’m interested
There’s no way we can consider this sector of the market without mentioning interest rates.
Last year’s rapid series of rate rises (the UK Bank Rate went from 0.1% to 3.5%) were triggered by surging inflation. But some degree of normalisation was due anyway, in order to help unwind 13 years of central bank easing.

Source: Bank of England
Rates are still fairly low by historical standards, but they’re higher than they’ve been for a long time. For a whole generation of investors – including many professionals – the rules of the game have changed.
All else being equal, higher borrowing costs should make it possible to earn improved income returns from relatively safe assets. For the big banks, this could support a return to double-digit returns on equity – something we’ve not really seen since the financial crisis.
Right now, high inflation means that real (inflation-adjusted) returns may still be negative. However, it’s worth remembering that historically, this wasn’t the norm.
This chart from Schroders shows that for much of the last 70 years, the UK Bank Rate (green line) has been higher than CPI inflation (blue line). During these periods, investors should theoretically have been able to generate positive real returns from risk-free assets such as government bonds:

Source: Schroders
The Bank of England’s latest Monetary Policy report suggests to me that these conditions could soon be seen again.
The report suggests that inflation could fall to a mid-single digit level by the end of this year, before dropping to 2% by the end of next year. This is paired with a fairly bearish view on unemployment and GDP growth by the Bank.
External forecasters are slightly more optimistic, but the overall implication is the same – serious inflation is not expected to persist much beyond this year:

Source: Bank of England Monetary Policy Report Nov 22
In contrast, interest rates are expected to stabilise close to their current levels. This raises the possibility that by the end of next year, investors might be able to generate positive real returns from risk-free assets. That’s not been true for a long time.

Source: Bank of England Monetary Policy Report Nov 22
Of course, economists are said to have correctly predicted nine of the last five recessions… We can’t be sure what will happen (or when), so I’ll consider some of the risks below.
However, if these forecasts are broadly correct, the implication – as Oaktree Capital founder Howard Marks recently argued in the FT (paywall) – is that “lenders and bargain hunters face much better prospects” than they did between 2009 and 2021.
Strengths & opportunities
I expect the impact of higher funding costs to ripple across the whole market, over time. In my view, some of the early beneficiaries may be financials – most obviously banks, and then perhaps insurers.
I think Property REITs may also offer opportunities, albeit for slightly different reasons.
Banks: Higher interest rates are allowing UK banks to rebuild their net interest margins (NIM) by increasing lending rates more quickly than rates on deposits. This increases a bank’s net interest income.
There isn’t a hard-and-fast link between NIM and interest rates, as this piece from accountants Deloitte explains. But for now at least, that seems to be the direction of travel:
Bank | Net interest income 9M 22 | Net interest income 9M 21 |
Lloyds Banking (LON:LLOY) | £9,539m (+15%) | £8,270m |
Natwest (LON:NWG) | £6,974m (+24%) | £5,613m |
HSBC Holdings (LON:HSBA) | $23,032m (+17%) | $19,708m |
Insurers: Insurance firms are big investors in government debt and property. Over the last year, revaluation losses and claims inflation (for non-life insurers) have put some pressure on profits and surplus capital coverage. Last week’s profit warning from Direct Line Insurance (LON:DLG) suggests this process may still be playing out.
However, on a medium-term view, higher interest rates should theoretically allow insurers to increase their investment returns from high-quality assets. Assuming inflation eases, I expect the insurance sector to benefit from higher rates.
Interestingly, the StockRanks don’t yet share my optimism. The Insurance industry group has an average StockRank of just 53.

Only six UK-listed firms have StockRanks of 70 or more. Perhaps it’s a little too soon?

Commercial property REITs: Property investors must balance property prices, borrowing costs, and rental rates in order to make a profit.
If one of these factors changes suddenly, then there has to be a corresponding change elsewhere. So far, prices have fallen and transaction volumes have slumped, as potential buyers wait to see how the market will settle.
In my view the main opportunities will be buying the best quality property at reasonable discounts – or finding special situations at deep discounts. I’ll explain why below.
Risks
As an investor, my main worry is that the combination of high inflation and higher interest rates will lead to a much deeper recession than the market is pricing in.
If this happened, then banks would likely suffer a sharp increase in bad debt levels and new lending would likely slow. This would probably offset any benefit from higher interest income. Last year’s rate rises might also be reversed.
A more nuanced scenario might be that banks find that they have to pass on more interest to savers, while keeping their mortgage rates competitive. That could limit much further expansion of net interest margins.
Banks and insurers seem to have fairly healthy balance sheets, so I don’t expect a repeat of the near-death experiences seen in 2009.
In the property sector, landlords could face pressure from near-term refinancing costs. However, most seem to have anticipated rising rates and be reasonably well positioned. I think a more interesting factor for commercial property (mainly offices) may be the impact of new rules on environmental rating.
From April 2023, office buildings will have to meet a minimum EPC rating of E in order to be let. From April 2030, this requirement will be increased to an EPC rating of B.
Tenants signing 10-year leases today need to know their offices will still be compliant in 2033. My guess is that some non-compliant property will be upgraded relatively easily, while some will be prohibitively expensive to improve.
Identifying REITs with property that can be uprated cost effectively might present an opportunity for investors.
More prudently, I think it may make sense to focus on the top end of the commercial property market. Demand has remained robust so far, but valuations currently look relatively reasonable to me.
Conclusions
I’m quite bullish about the value on offer in financials. Both my own portfolio and the SIF folio are quite heavily weighted towards this sector.
In my article next week, I’ll take an in-depth look at one financial stock to explain in more detail why I’m interested.
In the meantime, I’d welcome your thoughts below on the current appeal (or otherwise!) of this important sector.
Disclosure: At the time of publication, Roland owned shares of NatWest Group and Direct Line Insurance.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Sometime ago,
somewhere else,
in a series discussing investor bias a possible conclusion was that humans were not wired for investor success. A contrarian contributor supported his tale of riches with the anecdote that a wise sage had told him young to invest in financials whatever the macro scenario and he had followed the advice. I did too. I worked in the field which gave me confidence but in fact insiders do not have all the facts nor the macro view necessary to judge ups and downs. Furthermore the permanent parts of my portfolio of banks, insurance and real estate companies do not show a spectacular increase over 30 years or so. It is recognizing when to increase or reduce holdings that makes the difference, hence the importance of Roland's article.
I would argue that it is too late for quick profits in the banking sector which is now overbought. Look at any chart. Long term they are down from all time highs before 2009 but since October 2022 the slope UP is steep.
Stockopedia distanced itself from bank analysis early one, realizing that it does not have suitable algos.
Not so insurance and I remember an exchange about the Combined Ratio where Stocko expressed ignorance of the measure.
So here is how to interpret it:
Combined Ratio - analysis of premiums versus claims
(Claim-related Losses + Expenses) / Earned Premium)
A measure of insurance underwriting profitability where if the ratio is more than 100% then the underwriting is unprofitable.
Sometimes it is mentioned when trading updates are discussed in investment media.
Trade journals would help but they are prohibitively expensive and need either a corporate subscription or a higher net worth than most of us here.
So if nobody in the crowd knows how to judge insurance companies, surely that opens the field to the daring ?
Not so because the crowd is buying and selling and will force the price up or down according to sentiment towards the sector.
Stocko's pessimism led me to another data base which gives different and confusing results. I also invested in the North American insurance market with a much larger number of unfamiliar names.
On the whole, by following the mantra noted above, results have been good because I always am invested somewhere in the sector. In fact it is many sectors among which I would point to property and casualty, reinsurance and life which react differently to events. The general principle is that premiums paid up front create a free investment pool to play with. Property and Casualty has to deal with huge claims from natural disasters but an efficient company will have re-insured the risk. Re-insurance companies depend on the skill of their underwriters. Life has more to do with demographics and selling into growing markets such as Asia.
Interest rate changes affect the return of reserves Insurers have to keep to meet their liabilities. Not so obvious as banks and real estate because of the model.
In all cases nimble operators will deal with the macro environment as it develops but there is no question that public perceptions will determine our profits and losses in this area.
Dear Roland
Thank you for the article, as you always manage this is insightful and well written.
Whilst not bullish I am at least positive about a number of stocks within the banking, insurance and REIT sectors.
Partly as one of the funds I am responsible for is well and truly in income mode (Mum's Pension held in ISA - she is 80 years young after all), this has been up and down and in and out this last year (my limited capabilities) but over the last month I have been rebuilding after agreeing the updated strategy and plan. So there are risks within these sectors, as you note the impacts of the cancellation of the final dividend for Direct Line Insurance (LON:DLG) had a read across to Aviva (LON:AV.) and Legal & General (LON:LGEN) and how competitive is the banking sector overall to what is achieved for shareholders versus the race for new/more customers.
I think there are two parts here, which as an individual my holdings are of a size that in all but the worst day I can sell and cut losses (lesson learnt from Covid), so I can buy in and sell out on any given day, should something change. So profit warning = sell for me personally. But at the same time I am not 100% invested so I am using retractions to increase the holding size where I believe it is just that an opportunity rather than a change. I am also spread over a wider number of holdings now (plan 50-60 for mum), so the maximum holding size is 5% whereas it was previously 10%, this is partly a sleep at night factor, but also means that the impact of a profit warning for one company, change in sentiment, Mx Market sell off is lower on the overall capital position. I am also looking at the overall holdings within a sector to ensure that whilst different companies there is not too much within one pot, so if there is a new run on banks for example, again it is reasonably contained.
There is also the emotional part within this and acknowledging that, so whilst I hold Natwest (LON:NWG) and I am very grateful and happy for the recent rise, I also am nervous so I am prepared to take profit and sit on the sidelines for a few days, weeks or months which I did selling Secure Trust Bank (LON:STB) following the rise. Yes I may miss out on a further rise, but I am trying to learn to be ok with that.
Ok time for another Teams call.
Thank you and keep up the good work!
Cheers
Tommy (and family)
ps. I hold Aviva (LON:AV.) Legal & General (LON:LGEN) Natwest (LON:NWG) Lloyds Banking (LON:LLOY) Phoenix group (LON:PHNX)
Your optimism and that of the Bank of England on future levels of inflation is not shared by the likes of Ruffer who see inflation as 'higher for longer', even over the next 10 years. There seem to be some very divergent views from a whole host of commentators on the likely outturn for inflation over the medium term.
Hi ACounsell,
I agree, there's definitely a wide range of forecasts out there. What will actually happen is anyone's guess. We can only invest based on known facts and our interpretation of them.
DYOR is always essential -- I'm certainly not predicting any specific outcome.
As Yogi Berra said, "It's tough to make predictions, especially about the future"!
Roland
Investment ,is a tough one so many variables ,constantly changing.If you put a finger on one the other variable moves and destroys everything.Interest rates are up you would think the profit margin should be higher.The more you know the more careful you become.
Roland, what about Legal & General (LON:LGEN) that has a SR of 84? For some reason missed from your list. B.P. Marsh & Partners (LON:BPM) probably should be under insurance as well.
Quite a few insurers have already seen considerable share price rises in the last few months. Some are paying decent dividends, such as Phoenix group (LON:PHNX).
Hi Rusty2,
Personally I'm a big fan of both Legal & General (LON:LGEN) (I hold) and Phoenix group (LON:PHNX) (no position). L&G didn't get a mention because it's listed in the Investment Banking & Investment Services industry group rather than under insurance.
Sector classifications can sometimes be a bit of a blunt instrument - in L&G's case, clearly it operates across both insurance and asset management.
Regards,
Roland
Banks are still earning a very low return on capital. I guess they are cheap for a reason.
Historically, and I mean 30/40 years plus, they have always earned very low ROC - its the nature of the beast....
Hi Epitychia,
I tend to focus on return on equity as a measure of profitability for banks and insurers. ROE reflects the profits earned on the difference between lending (assets) and deposits (liabilities) - a bank's equity.Return on capital employed includes all the assets (loans) but excludes most of the liabilities (deposits), so I don't think it provides a meaningful view on profitability for banks.
Of course, banks have also earned very low returns on equity since 2008. This has been due to low interest rates, as well as problems like legal settlements (PPI etc).
Profitability now seems to be improving at UK high street banks, although of course we don't yet know whether this improvement will continue.
However, based on the scenario I've outlined, I think we could see bank ROEs continue to improve (moderately). That could lead to attractive shareholder returns, assuming economic headwinds don't offset the benefit of higher rates.
Regards,
Roland