Seeing Machines - Short-term financing fog obscures the long term story
Analyst’s view:
Although quarter-on-quarter declines in DMS/OMS production volumes may be a little concerning, the positive impact of the EU regulation change keeps the year-on-year growth impressive. There may also be seasonal impacts from lower automotive volumes over teh summer to consider.
However, the most concerning news is that there remains no refinancing of the Magna convertible that is now topping $60m, including accrued interest. With only three weeks to go until the CLN is due, the scope for alternative financing (which the company has already flagged as unattractive) looks slim. The deadline for publishing audited accounts to avoid suspension will preclude any further short-term extension of the current maturity.
I consider the most likely outcome is that Magna agrees to a long-term extension of the CLN, but with a much more favourable conversion price, perhaps even below the current share price. It's certainly what I would be going for if I found myself dealt their current strong hand in any negotiations.
With the outcome here apparently ranging from a CLN refinancing on much less favourable terms to a highly dilutive equity raise, or worse, I think we have to reinstate our negative view until the refinancing is out of the way and the terms of any deal are known.
Down 20% to 3.0p - Q1 FY2027 Quarterly KPIs
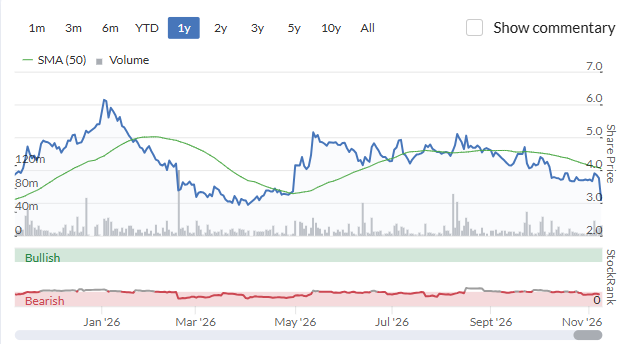
We've been worried about Seeing Machines for a while on the DSMR. At the start of the year, we were concerned that this was a loss-making company on an expensive rating with a looming debt refinancing, making the risk-reward unattractive. The business also announced that a customer had made an accelerated lump-sum royalty payment of $14.1m, which had previously been expected over the next four years. Roland wondered if this was a bailout in disguise.
By midyear, we started to wonder whether things had turned a corner. The European General Safety Regulation, which mandates DMS fitment across new vehicles from July 2026, was about to come into force, and it was driving accelerating sales.
However, the market's reaction to today's 27Q1 trading update. taking the share price back down to recent lows suggests we were too premature:
The headlines:
Seeing Machines’ Driver & Occupant Monitoring System (DMS/OMS) technology receives royalties on every vehicle with the technology, so it is automotive production volumes that are a key KPI here. The year-on-year growth is impressive, at +285%. However, this figure compares against a quarter before the EU safety mandate took effect, so it says little. A fairer comparison is Q4, which showed the first fall since the mandate drove volumes up.
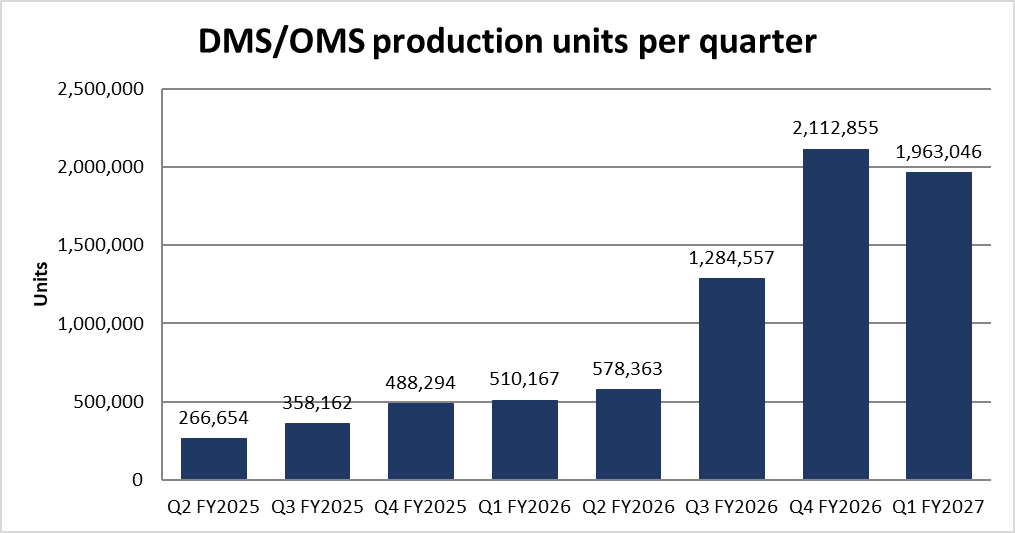
Some of this is likely the usual European summer slowdown, but any reduction in a supposedly highly in-demand product should be considered carefully. There is a big difference between a company that will grow licensing strongly over the medium to long term compared to one that sees a one-off jump to a higher but flat plateau. This quarter's figures suggest that the jury is still out on which one this is.
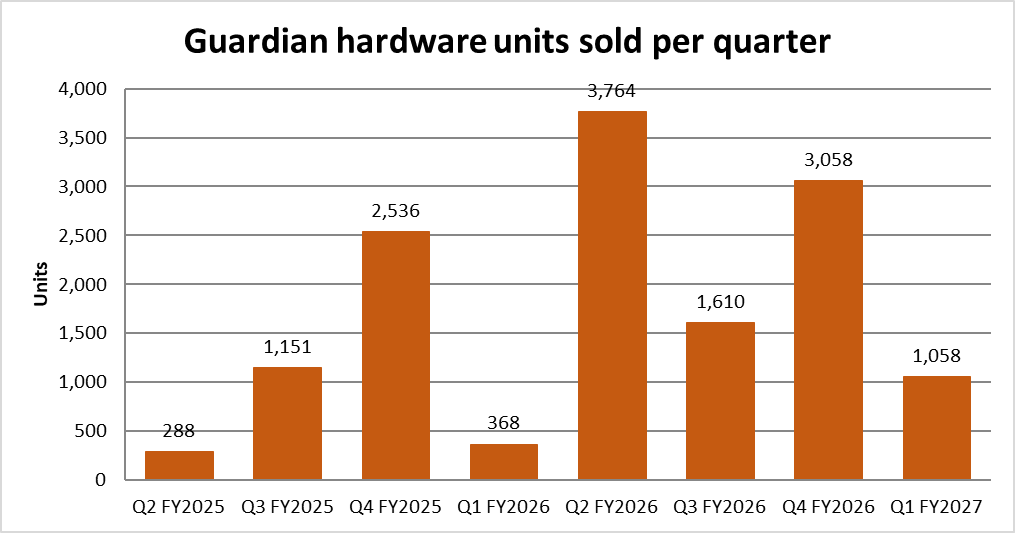
It was also a relatively weak quarter for their Guardian after-market solution, although the figures here are lumpy:
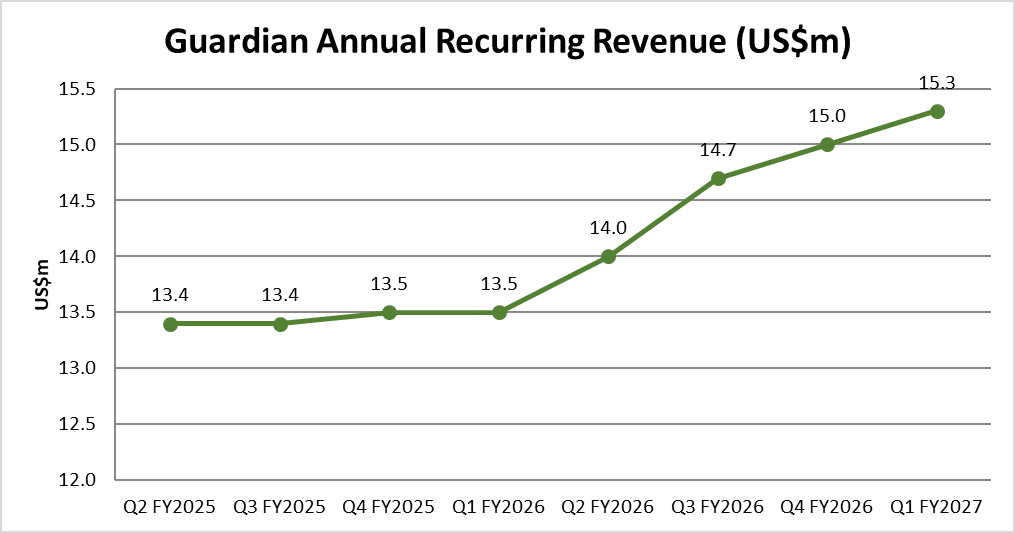
Better news is that the ARR component from installed Guardian units continues to grow:
The elephant in the room:
Although Q1 DMS/OMS numbers are clearly disappointing, it is the financing news that is the most troubling.
The Magna convertible note was originally due on 4 October 2026. Back in July, the company said
We are in advanced discussions with several lenders and have received multiple term sheets. Due to good interest from lenders and our focus on securing the most attractive terms for the Company, the process will go beyond the end of FY2026. We continue to make good progress and continue to expect to complete the refinancing well ahead of the October maturity date.
This didn’t happen. In September, the company instead agreed an interim extension moving the maturity date from 4 October to 30 November 2026, to allow negotiations on a longer-term extension. The CEO said he
...believe[d] the interim extension of the existing convertible loan notes is in the best interests of Seeing Machines and its shareholders when compared to the presently proposed refinance debt package.
With only three weeks to go, today, the company says they are:
...continuing work on a longer-term extension and refinancing options.
However, with accrued interest, the note will be up to around $63m at 30 November; there’s no agreed extension, no refinancing terms, no alternative lender named, and no reassurance about current cash levels. Cash at 31 December 2025 was $3.4m, and they received the accelerated lump-sum royalty payment of $14.1m. Cash at 30 th June was said to be $4.3m, suggesting a level of ongoing cash burn, although offset by increased customer royalties being paid on higher production. Presumably, in any refinancing, the company will want to rebuild cash levels to avoid any similar crunch in the future, making the total cash requirements from equity or debt above the figure of the current CLN.
We haven't had the Final Results to 30th June released yet. The FY2025 results and annual report came out on 25 September 2025. This year we’re six weeks past that date. Presumably, this is because they wouldn't be able to publish them on a going concern basis while the refinancing is not agreed. AIM rules require audited accounts within six months of year-end, so they aren’t late yet. However, the scope for them to extend the convertible maturity date again starts to put them up against the deadline to avoid suspension of their listing.
If talks with Magna stall, the fallback could be expensive debt or an equity raise. If I were Magna, knowing the company has said alternative lending options were not attractive, and pushing up against a deadline for the company's listing to be suspended, I would demand some pretty onerous terms regarding the conversion price. After all, their previous 11p conversion level proved to be far too optimistic.
There’s also a more positive reading. Magna has agreed to extend the loan rather than insist on repayment, and its commercial relationship with Seeing Machines gives it a reason to keep the company stable. As the main creditor, it may be in a strong position to buy the technology from the administrator if it called the debt and the company couldn't repay. However, it would also create significant uncertainty. Magna would presumably prefer to take their pound of flesh in the refinancing and keep a similar arrangement. A sensible long-term extension would remove most of today’s worry about the company's solvency.
Broker change:
Adding to the mystery, we also get a line saying:
Seeing Machines also announces that Stifel Nicolaus Europe Limited is now its sole broker with immediate effect. Stifel continues to act as the Company’s Nominated Adviser.
With individual investors unable to access Stifel's coverage, we're largely in the dark about any financial impact of today's trading update.
Whether Singer jumped or was pushed, I have no idea. However, the timing ahead of a possible refinancing or an equity raise asks more questions than it answers.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Seeing Machines (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?