Serica Energy: Triton delay cuts 2026 output to just below 40,000 boepd

Analyst’s view:
The unoperated Triton hub is once again causing the company problems with a delay in restarting production following summer maintenance. However, strong UK energy prices help soften the blow, even though production guidance is moderated. The market has been relatively sanguine about this, seeing it as production delayed rather than lost. Something I agree with. Zooming out, the company has re-rated over the last year or so, and no longer looks the obvious bargain it once did, at least relative to the O&G sector. However, it remains a Super Stock and with a Stock Rank of 92, I am in no rush to moderate our mostly postive view.
Down 3% at 273p (£1.10bn) - Trading and Operations Update
The weakness in Q3 reported today is immediately obvious:
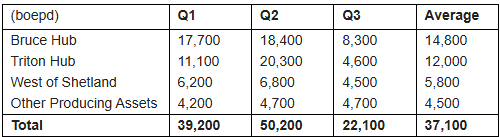
This summer period is when North Sea maintenance is scheduled, so a drop in production here isn't necessarily unexpected. After all, these are ageing assets where proper maintenance is increasingly important.
Bruce appears to have gone well:
The Bruce Hub resumed production after its scheduled annual maintenance period on 12 September, with the Hub's very largely gas production currently around rates of 20,000 boepd net to Serica
However, in a revelation that will perhaps not surprise long-term Serica watchers, Triton has some issues:
Annual maintenance at the Triton FPSO began on 27 July, with an operator expectation that it would last approximately two months. However, during the final preparation steps and safety checks for planned restart, the need for an engine change out in one of the power generation units was identified. This has resulted in the operator revising its forecast for resuming production to around the end of November.
Guidance Impact:
This is a big chunk of downtime, and therefore impacts overall production guidance:
Following the extension of the annual maintenance at Triton, Serica now expects production for 2026 to average just below 40,000 boepd
Which is down from where they were guiding in the H1 results in Early August (which itself was cut due to delayed completion of an acquistion):
The acquisition of assets from Spirit Energy is now set to complete on 1 October 2026, resulting in revised production guidance for 2026 of above 40,000 boepd (previously: significantly above 40,000 boepd)
The overall impact appears to be slight, and this is just production delayed rather than lost:
Reflecting the benefits of our enlarged portfolio, prior to the resumption of production from the Triton FPSO, production net to Serica is currently over 40,000 boepd, bolstered by the addition of around 12,000 boepd from the Southern North Sea gas portfolio recently acquired from Spirit Energy. Serica therefore maintains the expectation of reaching production rates of around 65,000 boepd once production resumes from the Triton FPSO.
All other guidance remains the same, and while missed production will impact year-end cash balances, the company has benefited significantly from higher energy prices.
The market seems to have taken a long-term view today, with shares dropping only a couple of per cent in response.
Valuation Multiples:
This means the company retains its Super Stock Status:
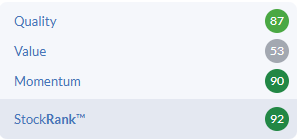
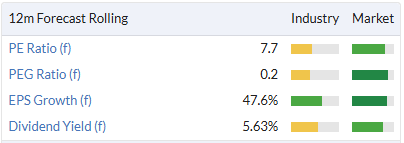
However, the Value Rank is now down to 53, and the forward P/E is around 8 on FY27 numbers, which assume a full return to production for Triton and the current forward energy curves. This looks like good value versus the wider UK market but not necessarily against other oil & gas producers:
I think the company's broad exposure to UK energy prices may also provide a natural hedge for many of us who are exposed to oil and gas as consumers.
M&A:
The company has scope to expand production further:
Serica continues to screen multiple M&A opportunities, both in the UK North Sea and overseas, while progressing the numerous organic growth options in the existing portfolio.
They tried to buy Pharos Energy over the Summer but were outbid. I see it as a positive that they didn't get into a bidding war for what appears to me to be rather mediocre assets in the sector.
However, I also think that invetsors sometimes get carried away with how good some of the Serica deals look. In an environment of rising energy prices, any historical deal looks good.
Also, many of the deals offer significant short-term production and cash flow but carry big unknown liabilities. Serica clearly thinks they can get more out of these than current operators, and they may well be right. However, they are not the only buyer in town. If my neighbour offered to sell me his house for half the market value, he wouldn't be just doing it to be nice. If I took the deal, I'm probably buying some significant risks as well as the assets! I expect the same with Serica's NS purchases. So far, Serica management has been very savvy dealmakers, but we shouldn't automatically expect that in the future, especially if energy prices start to decline.
Mark's View
While it is clearly disappointing that the unoperated Triton is again causing the company problems with production targets, this is a delay rather than lost production. I agree with the market's view today that this doesn't have a big impact on the Serica's overall valuation.
That said, the company appears to have re-rated over the last year of so, and at a forward P/E of around 8 and a dividend yield of around 6% it no longer looks the bargain it once did in absolute terms or relative to the wider oil and gas sector.
However, as a Super Stock with a Stock Rank of 92, I am in no rush to adapt our previously mostly-positive view of AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Serica Energy (8)
Comments here are also visible in the Daily Stock Market Report
After a day thinking about the bigger picture with Serica, I am tempted to see this RNS as confirmation that the diversified portfolio does not need Triton in order to cover the Opex, Capex and the Divi.
Institutions will be scrumming to build their positions...
To me, Serica Energy (LON:SQZ) looks like a cash cow of the highest order.
Serica Energy (LON:SQZ) Hmmmm
Making more money on less production, with more production to come..
LSE main listing in a week and the news is timed beautifully for institutions to pick up your shares on a RNS that i) Reports increased production from the spirit assets (was 10,000 now 12,000)
ii) Says Bruce is back to 20,000 (was 18,400)
iii) Shows the benefits of the enlarged portfolio, with hints at the widened scope of activity, particularly at SGP and Ithaca's existing infill drilling program
Could be an opportunity to pick up some shares from investors who get scared at any mention of 'Triton'
As for me, I'm holding.
I agree Pool Watcher.
The market appears to be treating: “full‑year average cut” as “year‑end target cut”
These are not the same thing.
The RNS explicitly confirms:
exit rate unchanged
cashflow unchanged
guidance unchanged
drilling unchanged
liquidity strong
balance sheet strong
This is a surely a misread?
After a day thinking about the bigger picture with Serica, I am tempted to see this RNS as confirmation that the diversified portfolio does not need Triton in order to cover the Opex, Capex and the Divi.
Institutions will be scrumming to build their positions...
To me, Serica Energy (LON:SQZ) looks like a cash cow of the highest order.
Hi I am a holder and indeed very much a Serica Energy (LON:SQZ) watcher. I regard the management team very highly and to me they are always transaparent, warts and all. Yet again we have Triton issues. One wonders if this is again operator issues and how long before Chris Cox is all over them for the serial failure to maintain equipment and thus output. There does always seem to be another Triton excuse coming...
Spirit looking good so far and I am not sure the latest Triton issue has anything other than it fairly now standard intake of breath in the hope that for the next period there will be some kind of normalcy.
Not sure if the market cap makes this likely to be included in the next indicies rejig but if it is then trackers will need to buy in
If Triton can not get maintenance done in summer what chance in autumn storms
It seems maintenance was going to plan until they discovered an engine change out was needed --text from RNS
Annual maintenance at the Triton FPSO began on 27 July, with an operator expectation that it would last approximately two months. However, during the final preparation steps and safety checks for planned restart, the need for an engine change out in one of the power generation units was identified. This has resulted in the operator revising its forecast for resuming production to around the end of November
Arguably this could happen whenever but with Triton issues seem to arise far too frequently......
I've added to my Serica Energy (LON:SQZ) this morning as I can't see my holding of Sequoia Economic Infrastructure Income Fund (LON:SEQI) going anywhere much so switched away.
I agree. Overall, I still think that the numbers are moving in the right direction, so no cause for alarm, just yet. If only they could get the Triton field to be a bit more reliable, but they're working with an aging asset, that as we all no, the older they get, the more attention and maintenance is required. Like you, I'm a shareholder and am not looking to sell anytime soon.