Daily Stock Market Report (Mon 19th Oct 2026) - BKS, MUL, SQZ, VLX, CLIG

The French were revolting this weekend as “largely peaceful” protests involving hundreds of thousands of demonstrators later degenerated into violence and looting.
According to the BBC, 1,500 shops and businesses were looted and destroyed, one thousand police officers were injured, and there were 2,400 arrests.
It comes at a precarious time for the French economy. As noted by James in his excellent Week Ahead article on Friday, the French 10-year yield is at the highest level since 2002 and has exceeded 5%.
On a brighter note, I carried out some important financial research at a gaming convention this weekend with my first ever Warhammer battle. My squadron of imperial bodyguards defeated the Adeptus Mechanicus (also known as the “tech-priests of Mars”). But the passion of the fanbase was what impressed me the most - and I still don’t fully understand how Games Workshop (LON:GAW) did that.
Overnight market movements:
The FTSE is down 0.1% at 10,865
S&P 500 is up 0.8% at 7,720
Brent crude (December) is down 2% at $107.65/bbl
Gold is up 0.5% at $4,185/oz
Bitcoin is up 2.3% at $82,700
Mark Simpson joins me today.
The Agenda is under construction. Spreadsheet accompanying this report: link.
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
GSK (LON:GSK) (£75.3bn | SR80) | First global data for Ris-Rez in extensive-stage small cell lung cancer. 61% overall response rate in phase Ib trial. | ||
South32 (LON:S32) (£10.8bn | SR70) | FY27 production guidance remains unchanged across all operations. Net cash increased to $297m. | ||
Londonmetric Property (LON:LMP) (£4.39bn | SR37) | H1: net rental income increased by more than 8% to c.£240m, helped by last year’s acquisition of Urban Logistics REIT. Average uplift from rent reviews was 17%. Like-for-like annualised income growth 5.8%. | ||
Volex (LON:VLX) (£1.16bn | SR86) | “Excellent” trading. H1 revenue at least $710m. Organic revenue up 21%. Growth rates have started to normalise as the Data Centre programmes that ramped up in the prior year annualise. H2 revenues to be broadly similar to H1. FY2027 underlying operating profit to be towards the upper end of current market expectations. | AMBER/GREEN= (Graham) | |
Serica Energy (LON:SQZ) (£1.1bn | SR92) | Q3 production of 22,000 boepd was “broadly in line”. Due to extended maintenance at Triton, now expects production for 2026 to average just below 40,000 boepd (previous guidance was over 40,000 boepd). Guidance of $450-475 million of post-tax CFFO for the year remains unchanged. | AMBER/GREEN = (Mark) | |
Gamma Communications (LON:GAMA) (£984m | SR88) | The Board thinks that c. 50% of the company is held by merger arbitrage funds that need more time to organise votes for their shares, so they adjourn the meetings to be held tomorrow until 2nd Nov. The 1,120 price is the final offer and the Board is not in discussions with anyone else in respect of a potential competing offer. | TAKEOVER | |
ITM Power (LON:ITM) (£636m | SR8) | Revenue £43.6m (up 68%) is ahead of upgraded guidance. Adjusted EBITDA loss £20.0m. Cash £215.6m is at top end of guidance. FY27 guidance: Revenue £50-60m, adjusted EBITDA loss £17-20m. | ||
City of London Investment (LON:CLIG) (£264m | SR96) | Quarterly net outflows $667m. Funds under Management falls from $12.3bn to $11.5bn. | AMBER/GREEN = (Mark) | |
Kistos Holdings (LON:KIST) (£260m | SR95) | YTD Pro-forma production 20.0k boepd (26H1: 20.8k boepd). Q3 production 18.5k boepd reflecting the planned turnaround of the Jotun FPSO. | ||
Tristel (LON:TSTL) (£207m | SR79) | Revenue +10% to £51.1m, Adj. PBT +15% to £11.7m, Ad. EPS +6% to 18.2p. Cash £16m (FY25:£12.8m). “The Board remains confident that the Group’s differentiated technology, predominantly consumables based revenue model and significant geographic opportunity provide a strong platform for sustained profitable growth.” | ||
Mulberry (LON:MUL) (£162m | SR52) | H1 Revenue +18%, in line with the Board’s expectations. | AMBER = (Graham) | |
Savannah Resources (LON:SAV) (£159m | SR27) | Portugal’s environmental regulator, has issued a positive conditional Declaration of Environmental Impact decision on the proposed Boticas bypass road. | ||
Beeks Financial Cloud (LON:BKS) (£120m | SR25) | Revenue +11% to £40.0m, u/l EBITDA +18% to £16.1m, u/l PBT +15% to £6.3m, u/L EPS flat at 7.62p. Net Cash £0.6m (30 Jun: £7.0m). Canaccord had £41m revenue and 8.9p EPS forecast). Anticipates FY27 revenue will be in the range of £43m - £48m, representing growth of between 7.5% and 20%; with an underlying EBITDA margin of between 38% and 42%. $4m of Exchange Cloud extensions in Q1. | PROFIT WARNING (AMBER/RED =) (Mark) | |
Invinity Energy Systems (LON:IES) (£101m | SR14) | Gross proceeds of £20m raised at 10p per share, a 45% discount to last close. |
| |
Cora Gold (LON:CORA) (£84.2m | SR30) | Selin Drilling Highlights include 12-23m at c.1.5g/t from 100-200m. | ||
Intercede (LON:IGP) (£79.9m | SR43) | Order valued at c.£1.04 million for professional services, including development work, in support of a large deployment in a US Federal agency. | ||
Gemfields (LON:GEM) (£58.9m | SR40) | Auction revenue $52m, 90 out 99 lots sold (92,153 carats) at $565/carat. | ||
80 Mile (LON:80M) (£58.2m | SR13) | Entered into a non-binding heads of terms to sell the Company’s Finnish licence package to Badlands Resources for CAD1.0m. | ||
Kodal Minerals (LON:KOD) (£57m | SR22) | Entered into a binding agreement with GH Geo-Consult Limited in relation to the Asamankese Lithium Project in Ghana. Kodal has the right to earn up to an 80% interest in the Project through a staged earn-in structure comprising cash payments, exploration expenditure commitments and technical project development milestones over five years. | ||
Hemogenyx Pharmaceuticals (LON:HEMO) (£45.4m | SR0) | Entered into a Feasibility Study Agreement with Nitto Denko to evaluate whether Nitto’s cell-targeted lipid nanoparticle drug delivery technology can deliver Hemogenyx’s messenger RNA encoding its FLT3-targeting chimeric antigen receptor to human T cells. | ||
Gelion (LON:GELN) (£30.4m | SR3) | Independent testing of its Nano-Encapsulated Sulfur Cathode Active Material confirms reproducibility of Gelion's technology, with cells maintaining 92% of their reference capacity despite a 20-fold increase in cycling rate, supporting progression towards commercial qualification in defence, aerospace and drone applications. | ||
Petro Matad (LON:MATD) (£16.3m | SR5) | MoU for cooperation on a renewable energy export initiative from Mongolia into China targeting a capacity of 4.5GW as a first phase, supported by 500MWh of battery storage. | ||
Diales (LON:DIAL) (£16.1m | SR96) | Revenue cont. Ops +6.8% to £44.0m, U/L Op Profit not less than £1.8m, ahead of market guidance. Cash £3.3m (31 Mar: £3.9m) +£1.0m received shortly after year end. | ||
Energypathways (LON:EPP) (£14.9m | SR2) | Has entered into a number of technical agreements giving it access to a suite of geotechnical data and analytical services to support the development concept for the salt caverns at its MESH project in the East Irish Sea and at Barrow-in-Furness, Cumbria. | ||
Sunda Energy (LON:SNDA) (£12.2m | SR8) | Received an extension of 12 months to the current phase of Production Sharing Contract. | ||
RC365 Holding (LON:RCGH) (£12.1m | SR20) | Secured an additional development contract worth $250k with an existing client of its Wealth Management System in Hong Kong. | ||
Clean Power Hydrogen (LON:CPH2) (£11.2m | SR2) | The work completed to date has identified a number of unrelated factors which are likely to have contributed to the incident. No single definitive ignition source has been identified. |
Mark's Section
Beeks Financial Cloud (LON:BKS)
Up 3% at 180p (£120m) - Final Results - Mark - BLACK/AMBER/RED =
The results headlines here look reasonable, with revenue up 11% to £40.0m, and some modest operational gearing leading to underlying PBT up 15% to £6.3m.
These are in line with, or slightly better than, the FY26 Trading Update released in July, which said:
FY26 Revenue is expected to increase by 11% to approximately £40.0m (FY25: £35.9m), with underlying EBITDA growth of 18% to approximately £16.0m (FY25: £13.6m) and underlying profit before tax growth of 13% to approximately £6.2m (FY25: £5.5m).
At the time, we pointed out that this was a profits warning as revenue came in below Canaccord's £41m estimate and PBT significantly below the broker's £7.0m estimate.
Paid-for research provider Progressive were more conservative with £39.5m and £6.4m for revenue and PBT, hence the miss versus consensus was not as severe as if one had only looked at the house broker.
However, things started to get a little confusing. Progressive trimmed their PBT estimate, whereas Canaccord didn't appear to update their forecasts, despite confirmation from the company that they had not delivered their expectations.
Things get even weirder when we look at EPS. Progressive cut their forecast very slightly from 8.2p to 8.1p on the July profits warning, but the lack of an update to forecasts at Canaccord means they still had 8.9p pencilled in. Here's the actual figure from the company:
Underlying diluted EPS 7.62p (2025: 7.60p)
Progressive agree with the company's adjusted figure of 7.6p which is a 6% miss.
Canaccord make their own adjustments and seem to come up with £6.7m PBT which looking at the difference between their EBIT and PBT figures appears to adjust out the tax paid by the company, despite there being cash taxes paid.
While this gets rather confusing, the net result is that I'm calling these results a miss (though a relatively minor one), at least in what shareholders actually care about: the bottom line.
Adjustments:
With a big gap between adjusted and statutory profits, it always bears a careful look at the details of the adjustments:
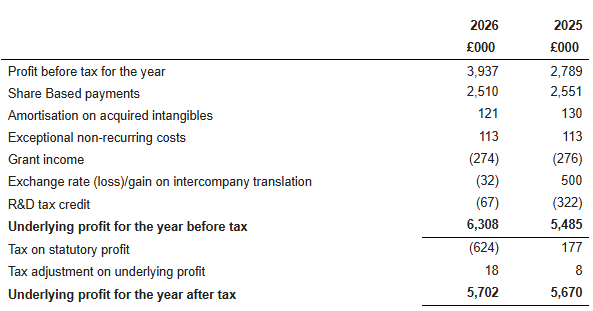
While exceptional non-recurring costs seem to be un-exceptional and recurring, the figure here is relatively small.
The big difference is share-based payments, which are a regular feature of this company.
Given that executive management are keen to sell these shares (perhaps understandably at the current valuation), then it is tempting to treat these like any other form of remuneration:
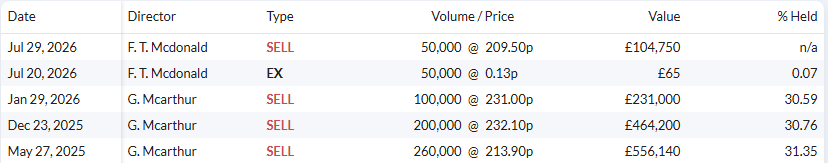
However, at least the company quotes fully diluted EPS figures, which recognise the significant dilution these options create.
Cash Flow:
The other thing that investors care about is cash flow, and here there are some worrying trends with net cash falling to just £0.6m from £7.0m the year before. They point out that:
This reflects upfront hardware investment for a number of contracts deployed in Q4, which are billed over their terms, with £17.7m of contracted billings to be collected.
However, this does nothing to reassure me about the business's capital intensity, which has always been one of my major concerns here. It can be easy to generate revenue growth by agreeing to meet lots of upfront customer costs, such as hardware acquistion.
The maths suggests they spent £7.8m on equipment and £2.4m on software development to increase revenue by £4.1m. Even if we assume some lag and use the previous year's capex figures, it was £5.1m on equipment and £2.4m on development.
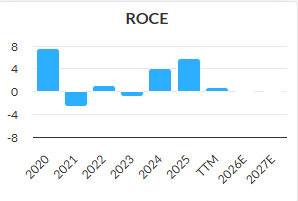
This isn't necessarily a terrible deal if they generate high-margin recurring revenue from this capex. However, there is always a big risk that strong growth in a company with low single-digit ROCE destroys shareholder value, not enhances it:
Part of this cash outflow is due to the increase in receivables. Current receivables go up from £7.7m to £9.6m, which is fairly normal for a growing company.
However, it is worth noting that curent contract assets have increased by about £0.9m to £4.5m. These represent unbilled receivables. They may be contracts where the company hasn't yet reached billable milestones with a customer, but these are, by nature, less reliable than revenue that has been invoiced.
Non-current receivables, where a company has booked revenue but expects to be paid for the work more than a year in the future, have jumped from £8m to £13.2m. Assuming that is largely unbilled, revenue booked but not invoiced jumped by £6.1m in the year, versus an increase in booked revenue of £4.1m, meaning earnings quality has declined this year.
Customer dispute:
Although overall credit quality seems high based on the company metrics, with these dynamics around receivables quality, this is a worrying development:
During the year the Group recognised a £0.5m (2025: £0.1m) impairment of a contract asset following a dispute over the remaining contract period with a Proximity Cloud® customer.
This appears to relate to a customer cancelling a contract and disputing how much of the contract term remained. This seems a rather basic detail not to be nailed down in contract terms.
Outlook:
They helpfully give some specific guidance for the upcoming year:
The Board anticipates FY27 revenue will be in the range of £43m - £48m, representing growth of between 7.5% and 20%, with an underlying EBITDA margin of between 38% and 42%
The top end of that range would represent a very good growth rate. Canaccord have £46m of revenue pencilled in for this year, saying:
ACMRR already covers around 3/4 of our updated FY27 forecast, leaving just shy of £11m to be delivered in upfront revenues, slightly below last year's £11.4m.
They forecast 10.5p EPS. Progressive remain more conservative, forecasting £44.5m, with 10p EPS.
However, as this year has shown, Canaccord have tended to be too optimistic on revenue, and the company has tended to miss EPS forecasts from both.
Q1 Trading:
In an attempt to back this trading position, the company released a separate Q1 trading update:
Beeks secured c.$4m of Exchange Cloud® contract extensions in Q1 FY27, reflecting growing demand from existing customers and continued delivery of its land and expand strategy. This is in addition to the previously announced Stock Exchange of Thailand win in Q1 FY27, bringing the total number of Exchange Cloud® customers to eight.
They don't appear to have issued a separate Q1 trading update before, and the cynic in me wonders if they feared the market might not have reacted well to the Final Results on their own.
As it stands, I'm not sure I find this trading statement that reassuring. The quoted sales numbers are contract extensions rather than new wins, and the company doesn't mention any specific revenue or cash figures, which we'd relaly want to know from a quarterly update.
Mark’s view
While the initial headlines look OK, the more I dig into the details, the more questions they raise. The company appears to be developing a habit of missing expectations, although it is still growing sales and PBT, if not EPS. However, if they really are on track to meet their FY27 guidance, this will represent a step change in growth going forward.
My concern here has never been their ability to generate sales growth. It is how capital-intensive that growth is. Today's results are not particularly reassuring on that front. Earnings quality also appears to have declined with an increasing reliance on unbilled revenue.
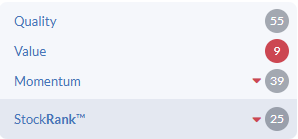
If the company were trading at a modest multiple, I'd be more inclined to overlook these foibles. However, with a Value Rank of just 9 and a declining StockRank of 25, I keep our mostly negative view.
Serica Energy (LON:SQZ)
Down 3% at 273p (£1.10bn) - Trading and Operations Update - Mark - AMBER/GREEN
The weakness in Q3 reported today is immediately obvious:
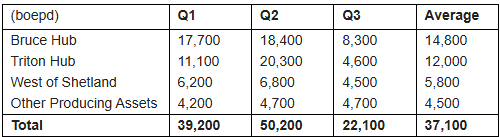
This summer period is when North Sea maintenance is scheduled, so a drop in production here isn't necessarily unexpected. After all, these are ageing assets where proper maintenance is increasingly important.
Bruce appears to have gone well:
The Bruce Hub resumed production after its scheduled annual maintenance period on 12 September, with the Hub's very largely gas production currently around rates of 20,000 boepd net to Serica
However, in a revelation that will perhaps not surprise long-term Serica watchers, Triton has some issues:
Annual maintenance at the Triton FPSO began on 27 July, with an operator expectation that it would last approximately two months. However, during the final preparation steps and safety checks for planned restart, the need for an engine change out in one of the power generation units was identified. This has resulted in the operator revising its forecast for resuming production to around the end of November.
Guidance Impact:
This is a big chunk of downtime, and therefore impacts overall production guidance:
Following the extension of the annual maintenance at Triton, Serica now expects production for 2026 to average just below 40,000 boepd
Which is down from where they were guiding in the H1 results in Early August (which itself was cut due to delayed completion of an acquistion):
The acquisition of assets from Spirit Energy is now set to complete on 1 October 2026, resulting in revised production guidance for 2026 of above 40,000 boepd (previously: significantly above 40,000 boepd)
The overall impact appears to be slight, and this is just production delayed rather than lost:
Reflecting the benefits of our enlarged portfolio, prior to the resumption of production from the Triton FPSO, production net to Serica is currently over 40,000 boepd, bolstered by the addition of around 12,000 boepd from the Southern North Sea gas portfolio recently acquired from Spirit Energy. Serica therefore maintains the expectation of reaching production rates of around 65,000 boepd once production resumes from the Triton FPSO.
All other guidance remains the same, and while missed production will impact year-end cash balances, the company has benefited significantly from higher energy prices.
The market seems to have taken a long-term view today, with shares dropping only a couple of per cent in response.
Valuation Multiples:
This means the company retains its Super Stock Status:
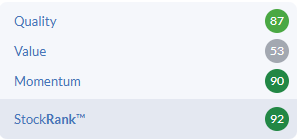
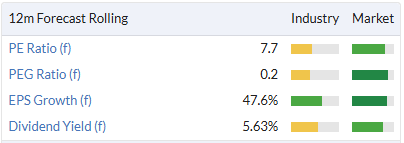
However, the Value Rank is now down to 53, and the forward P/E is around 8 on FY27 numbers, which assume a full return to production for Triton and the current forward energy curves. This looks like good value versus the wider UK market but not necessarily against other oil & gas producers:
I think the company's broad exposure to UK energy prices may also provide a natural hedge for many of us who are exposed to oil and gas as consumers.
M&A:
The company has scope to expand production further:
Serica continues to screen multiple M&A opportunities, both in the UK North Sea and overseas, while progressing the numerous organic growth options in the existing portfolio.
They tried to buy Pharos Energy over the Summer but were outbid. I see it as a positive that they didn't get into a bidding war for what appears to me to be rather mediocre assets in the sector.
However, I also think that invetsors sometimes get carried away with how good some of the Serica deals look. In an environment of rising energy prices, any historical deal looks good.
Also, many of the deals offer significant short-term production and cash flow but carry big unknown liabilities. Serica clearly thinks they can get more out of these than current operators, and they may well be right. However, they are not the only buyer in town. If my neighbour offered to sell me his house for half the market value, he wouldn't be just doing it to be nice. If I took the deal, I'm probably buying some significant risks as well as the assets! I expect the same with Serica's NS purchases. So far, Serica management has been very savvy dealmakers, but we shouldn't automatically expect that in the future, especially if energy prices start to decline.
Mark's View
While it is clearly disappointing that the unoperated Triton is again causing the company problems with production targets, this is a delay rather than lost production. I agree with the market's view today that this doesn't have a big impact on the Serica's overall valuation.
That said, the company appears to have re-rated over the last year of so, and at a forward P/E of around 8 and a dividend yield of around 6% it no longer looks the bargain it once did in absolute terms or relative to the wider oil and gas sector.
However, as a Super Stock with a Stock Rank of 92, I am in no rush to adapt our previously mostly-positive view of AMBER/GREEN.
City of London Investment (LON:CLIG)
Down 11% to 465p - Trading Update for the Quarter Ended 30/09/26 - Mark - AMBER/GREEN =
The market hasn't liked the update from this Emerging Markets and Fixed Income asset manager:
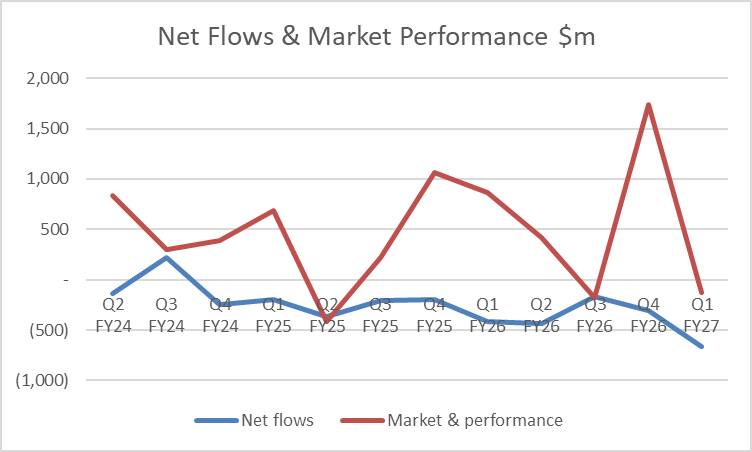
During the quarter, the Group recorded gross inflows of $87 million and outflows of $754 million, resulting in net outflows of $667 million. Market and investment performance reduced FuM by a further $127 million, reflecting volatile market conditions during the period.
While in isolation this doesn't look disastrous, the combination of weak inflows, large outflows, and negative performance stands out.
This is a company that has seen AuM growing recently:
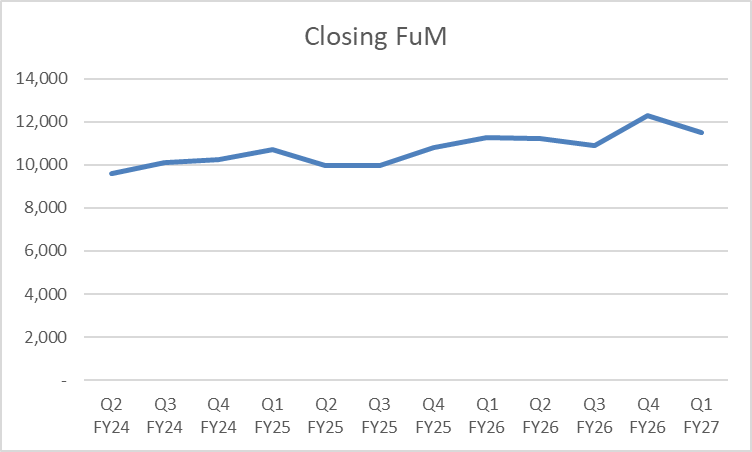
However, it seems too soon to conclude that the trend is broken, and the company has seen AuM decline in some previous quarters. However, what appears to be accelerating outflows may be worrying:
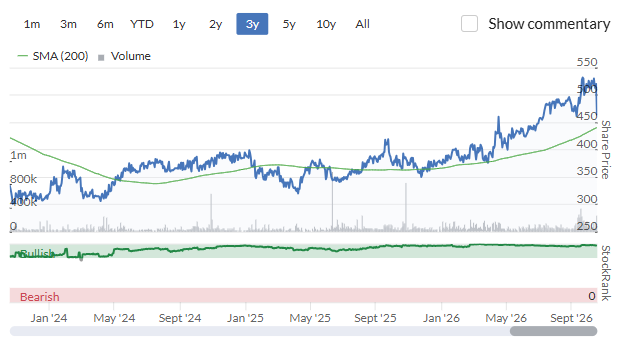
One difference is that the share price has been strong recently:
Part of the share price strength is due to the recent upgrades in broker forecasts:
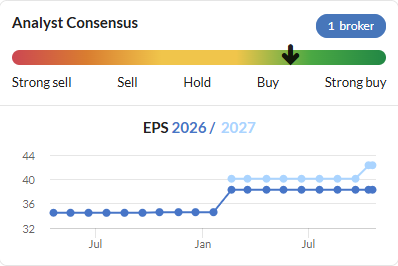
I can't see any updated coverage today, but Zeus based its numbers on a $12.3bn closing AUM for the year, which now looks challenging to achieve.
This is an institutional manager, so it tends to see outflows when it has a period of strong performance, as investors rebalance their allocations:
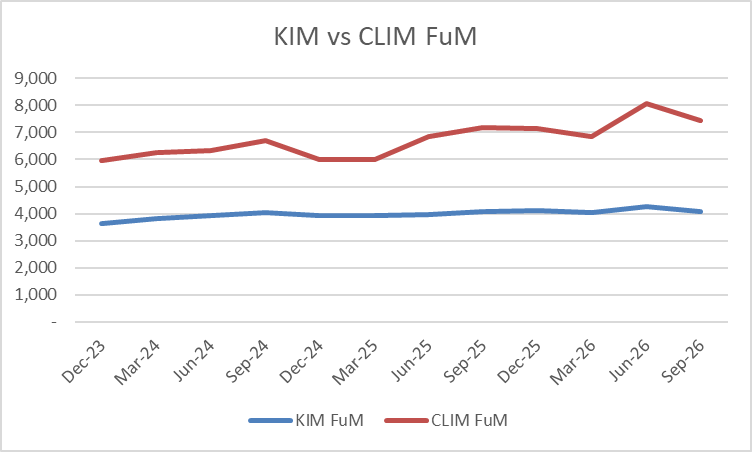
Sentiment for our asset classes was muted for the quarter; however, investment performance remained strong over the long term. Net outflows were primarily driven by client rebalancing and portfolio allocation decisions across the City of London Investment Management (CLIM) business following periods of strong relative and absolute investment performance. These withdrawals were concentrated in Emerging Markets, International Equity and Other.
The breakdown between CLIM and KIM backs this narrative up:
However, looking at the breakdown between inflows and outflows, it is the lack of sales that stands out as well as the rebalancing outflows:
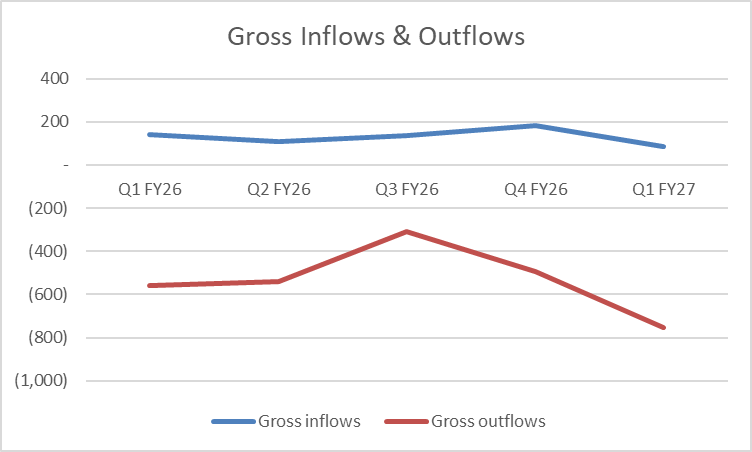
One minor aspect that also stands out is that the "Other" category in CLIM, which they say includes Frontier and alternatives, has gone to zero FuM in this quarter. Presumably this was a specific redemption, or they chose to close this strategy.
Mark's view
A bad quarter is par for the course for asset managers at the moment, so it is probably best not to over-react. However, today's strong share price response suggests many investors expected this to go the other way following recent broker upgrades. This was reflected in the strong Stock Rank:
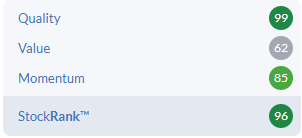
The Quality Rank has always been high here, as it has for many asset-light businesses, so Momentum has done the heavy lifting recently.
The recent decline in Value Rank suggests this Momentum hasn't been fully backed by fundamentals, making it susceptible to a rapid reversal. Could today's share price decline portend that? Without updated broker coverage, it is hard to be certain. The FUM number for year-end in the latest Zeus number now looks challenging, but it would be a bit embarrassing for them to downgrade the outlook so soon after their recent upgrade.
This leaves me in a bit of a quandary about our view. On balance, I think the roughly 7% dividend yield probably tips it in favour of keeping our AMBER/GREEN stance. However, another weak quarter or a broker EPS downgrade would make me more neutral.
Graham's Section
Mulberry (LON:MUL)
Up 7% at 245.5p (£173m) - Half Year Trading Update - Graham - AMBER =
This is an in line update from the "lifestyle brand" that is most well known for its luxury handbags.
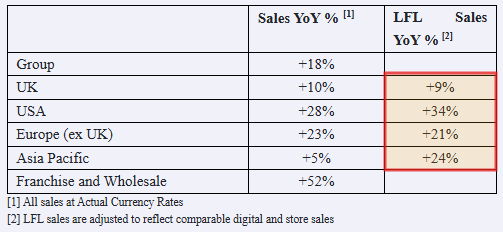
The right-hand column is more meaningful to me: "adjusted to reflect comparable digital and store sales".
These are some pretty impressive growth rates, even in the UK which was the weakest region.
Overview:
Performance in H1 was supported by strong customer demand across both seasonal and core collections. New product introductions, including Raffia, Crochet, Stevie and Darley Camera Bag performed particularly well, alongside continued demand for icons such as the Bayswater and Lily. Recent performance has also benefited from heightened brand visibility following the Mulberry by Christopher Kane runway show at London Fashion Week.
Christopher Kane is Mulberry's new creative director; he brings a big reputation in the industry with him. The Guardian offers more coverage of his work at London Fashion Week here.
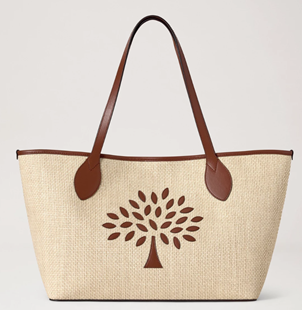
Of if you're simply curious to see what a Raffia bag looks like, here you go. The price is £595:
Medium-term financial targets:
The Group remains focused on continuing to rebuild gross margin and on restoring profitability, targeting annual revenue of more than £200m and a 15% adjusted EBIT margin over the medium term.
Context: in FY March 2026, revenues were £125.5m and the company generated an underlying pre-tax loss of £8m.
CEO comment:
“We are very pleased with the progress made during H1... The growth in full-price sales is particularly encouraging, demonstrating that our collections are resonating with customers across our key markets....
There remains much more to achieve as part of our strategic plan, and we are operating in a challenging trading environment. However, we enter the second half with a strong product pipeline, increased brand desirability and a clear focus on delivering our strategy.”
Graham's view
The company - for sound commercial reasons, I suppose - doesn't provide a complete breakdown full-price sales, promotional sales, and markdown sales.
But gross margin does have to be disclosed, and it grew last year from 67% to 72%.
And for H1 FY27, we are told that promotional sales have become a lower proportion of total sales, "supporting gross margin performance", so hopefully we'll see yet more progression on that front this year.
But I think the bigger picture is the Mulberry does need to grow significantly, if it's going to generate consistent profitability.
Its gross margins are already very high (several percentage points higher than Burberry (LON:BRBY), in which I have a long position). And its underlying operating expenses haven't been growing very fast (only up 2% in FY26). What it needs is a significantly bigger revenue base so that operational leverage can start to kick in for it again.
Note that it had some strong years earlier this decade, when revenues were over £150m. If revenues can get to £150-200m, hopefully we'll start to see results like this again:
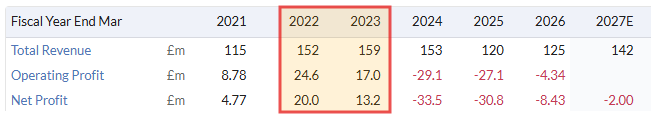
Because at its recent scale, profits are going to be slim at best. In July, I noted that H2 FY26 was breakeven after H1 was loss-making.
So my view here is unchanged. I think Mulberry should probably seek a buyer for the whole business who can run it more efficiently, as part of a larger organisation.
As for our stance: the last time, I covered Mulberry, I upgraded our view to neutral. The shares have surged by over 70% since then, but I don't think market expectations have moved:
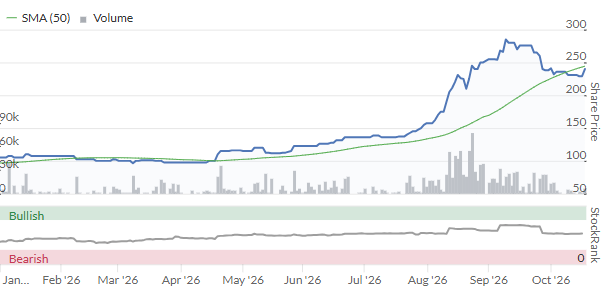
So I'm going to stay neutral on it again today. I still have worries about its ability to grow its way into consistent profitability, and its less obviously a bargain to a trade buyer at the current, higher share price. But the business is moving in the right direction, and if it does approach £200m of revenues then it has a real chance to succeed as a standalone entity.
Volex (LON:VLX)
Down 6% at 597p (£1.08bn) - Half Year Trading Update - Graham - AMBER/GREEN =
Volex plc (LSE: VLX), the specialist integrated manufacturer of critical power and data transmission products, today issues a trading update for the six months ended 30 September 2026.
As noted in the comments today, Volex has seen a surprisingly negative share price reaction given the headline: FY2027 profit expected to be towards the upper end of current market expectations.
Key points:
H1 revenue of at least $710m with $11m of that from Kepler SignalTek, acquired in July.
Organic, constant-currency revenue growth at least 21%.
This key paragraph explains that year-on-year growth is less meaningful than half-on-half growth:
As indicated in the Group's AGM statement in August, headline year-on-year growth rates have started to normalise from the 28% reported for the first four months of the year, as the Data Centre programmes that ramped up in the prior year annualise. Sequential trading remains the better guide, with first half revenue expected to be approximately 7% higher than in the second half of FY2026 on an organic constant currency basis.
This is perfectly logical: the Data Centre boom last year was extraordinary, and growth rates now have to return to something sustainable. So 7% half-on-half growth is what we should be focusing on, rather than 21% year-on-year growth.
There are a few other reasons to expect growth to moderate, mentioned in today's update.
Within the "Complex Indistrial Technology" segment, $10m of orders have been pulled forward into H1 that would otherwise have appeared in H2.
Also within this segment, Data Centre-specific revenues have fallen in H1 FY27 compared to H2 FY26. The prior period saw Volex "meeting customers' near-term capacity needs at a time when other suppliers were unable to do so". Supply conditions have since normalised.
In addition to the potential for revenue growth to calm down, I'd also have to wonder about the sustainability of profits given that last year saw such extreme market conditions. Volex says that their "view of the medium and long term growth opportunity is unchanged" - often something that companies say when the short-term has been a little more complicated than anticipated.
Leverage is thought to be no more than 1.2x, and a £20m buyback is ongoing.
Outlook:
Second half revenues are expected to be broadly similar to the first half, after allowing for the revenue brought forward ahead of the US site consolidation, with current trading conditions expected to continue across most end-markets. The Board expects FY2027 underlying operating profit to be towards the upper end of current market expectations.
Market expectations are helpfully provided: underlying operating profit of $150.4 million, with a range of $145.9 million to $153.3 million.
Graham's view
As noted in reader comments today, it seems that markets were already expecting a profit result towards the upper end of the range. Indeed, if I was being really pedantic, I'd point out that the consensus figure ($150.4m) is itself towards the upper end of the $145.9-153.3m range. So if Volex merely hits that consensus estimate, they will be towards the upper end of the range!
And it seems that regardless of the precise figure they achieve, they are on track to exceed by a wide margin the $138.3m estimate which was in place as recently as the August AGM.
Checking forecasts from Zeus, published earlier this month, I see that Adj. EBIT (which should be identical to underlying profit) is seen rising to $161.8m next year (FY March 2028) and then $174.5m the year after that.
Revenue growth is seen at 10% this year, 6.5% next year (FY27) and then 7% in FY28.
All of which sounds very reasonable to me for a stock that is not trading at extreme valuation numbers:
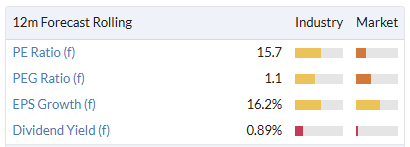
Roland normally covers this stock, not I. In August, he was moderately positive. It seems to me that little has changed today. There may be some disappointment among investors that extraordinary growth is coming to an end, but that was already baked into forecasts. Unless there has been some behind-the-scenes downgrade that I've missed, I think it makes sense to leave our moderately positive stance unchanged for now.
Update: thanks to readers for pointing out that the latest Zeus note has hit Research Tree, and it shows slight increases to forecasts. The new Adj. EBIT forecast for FY27 is $153.8m, up 2.4%, and outer years are also upgraded by 2.4% (FY28: $165.7, FY28: $179.7m). Revenue forecasts are upgraded for every year by c. 2%.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
Why has Shearwater dropped off today's list of RNSs?
Just announced a new government contract renewal.
this is yesterdays thread not todays :)
Sorry I missed this yesterday, Colin.
Excellent articles as always. Graham do you mean "Imperial Guard" by any chance? ;) Games Workshop (LON:GAW) Warhammer is rather addictive when you get into it! Effectively it's just more sophisticated gambling with dice...
Thanks, the latest Zeus note on VLX had not yet been published when I started writing the article. I've added an update to the report to reflect this.
Hi Graham
Zeus have modestly increased their forecasts for Volex (LON:VLX) for years FY27 to FY29
Their brokers note is available on Research Tree.
I thought the results for Tristel (LON:TSTL) (I hold) today had a very different, more formal tone than prior results, with many of the KPIs, that were previously included missing. I guess this is why the price has dropped today. However, the investor presentation https://investors.tristel.com/ in my view, suggests a company at an inflection point that is driven by new geographic territories, not only the US, and significant new products: Unifoam in particular. The presentation is worth a listen for insights not fully covered by the slide deck, for those who are interested.
Tristel (LON:TSTL) I thought CEO came across well on positive IMC presentation. We still have 1 place on SIGnet visit to the company on 25th November - text me on 07770 921 303 if you are interested
MelloMonday is back tonight... MM 19th Oct from 5pm
Paul Jourdan of Amati kicks off the show then Tharisa (LON:THS) & SRT Marine Systems (LON:SRT) present. Tom Burnet, Chair of Baillie Gifford Us Growth Trust (LON:USA), talks us through the importance of AGM/EGM voting. Hope to see you on zoom later...
David
Beeks Financial Cloud (LON:BKS) taking a very cautious approach to setting expectations for the next Jun27 FY!
[Revenues] between 7.5% and 20%; with an underlying EBITDA margin of between 38% and 42%
When you flow through the various permutations above, that is a very wide range of possible EBITDAs and EPS...
Surprising for a business that prides itself on having a base of recurring revenues, and where sales/deployment cycles are rather long rather than "last minute impulse purchases". We're already 3.5 months into the new FY, and new contract revenues should be fairly known for the next 3-6 months already.... leaving maybe just 2.5 months visibility uncertainty.
Maybe its because of all the new product launches and uncertainty of revenues they might provide?
The cynic in me defaults to... "they are still very dependent on one-off revenues, have little control and visibility over the new contracts pipeline, and take-up of Exchange services by end customers still not showing predictable strong growth rates yet"
Volex (LON:VLX)
Surprisingly muted reaction to what is a good trading update. Perhaps there was an expectation of more and/or the fear that the AI spending spree has run its course.
The latter is only part of the equation insofar as Volex (LON:VLX) is concerned. With operating margins heading towards 12% on increased revenue now is not the time to sell in my opinion, more likely it is a time to add.
The view of Graham and his colleagues would be welcome, time permitting.
I hold.
I agree Jonno, strange response to what seemed like a positive update. any thoughts from the team gratefully received, although I have added to my position already ;-)
I also agree Jonnp re Volex (LON:VLX)
And presumably the EV side of the business will be getting a boost from the move to electric vehicles in the face off the current very high fuel costs
Volex (LON:VLX)
Surprisingly muted reaction to what is a good trading update
i think its the drop in growth rate ref sales here that is teh issue - yes they are towards the top end of expectations now - so that perhaps an uptick of $1 to $2 mill ref profits. however the current estimated figure quoted is already closer to the top end than the bottom anyway ref range expectations so its kinda odd that were are already there ish in some respects - presumbably its a laggard ot two near then bottom creating that situation.
I think the normalisation of growth rates that is perhaps what might put a semi downer on things - sometimes you can be a victim of your own success when things are going well that if you have purple patch with the benefit of hinsight the later period kinda looks not as rosy when lfl's are concerned. Seems like they have flagged it up reasonably previoously though - but if they say sequential trading "is the best guide" and are also saying h2 revenues are likely to be flat is that them conceding there is nil growth now H2?
they seem positive ref trend in margins though so perhaps profits can go up faster than revenues.
I would be interested to see if there are any changes to 2028 expectations - as ever the behind the scenes nod and wink is often more important what they actually tell shareholders
per todays update.
As indicated in the Group's AGM statement in August, headline year-on-year growth rates have started to normalise from the 28% reported for the first four months of the year, as the Data Centre programmes that ramped up in the prior year annualise. Sequential trading remains the better guide, with first half revenue expected to be approximately 7% higher than in the second half of FY2026 on an organic constant currency basis.
Second half revenues are expected to be broadly similar to the first half, after allowing for the revenue brought forward ahead of the US site consolidation, with current trading conditions expected to continue across most end-markets.
First half underlying operating profit1 margin is expected to show progress towards the Group's medium term target of 12%, reflecting an improving revenue mix, including the higher-margin contribution from KST, and further operational efficiencies. Operating expenses continue to be managed closely, with investment in capacity and capabilities focused on supporting the Group's medium term strategic plan.
If they achieve forecasts on Stocko, they are sitting on a PE of 12.1 for this year and 10.6 for next year. That's cheap in my view .
Volex (LON:VLX)
If they achieve forecasts on Stocko, they are sitting on a PE of 12.1 for this year and 10.6 for next year. That's cheap in my view .
is the pe that cheap ? i know stocky this morning had pe of 15.7 - shareprice has dropped a bit today but then we have dollar and cents figures - are you 100% sure that your calcs are correct ?
Your right - I'm wrong - thank you for pointing it out so politely!
Need to multiply by the exchange rate (currently 1.33). So PEs of 15.7 and 13.8. So maybe "good value" rather than "cheap"!
Volex (LON:VLX)
So maybe "good value" rather than "cheap"!
Yes indeedy thanks for clarification - note bearing in mind the modest upgrades for next year and year after i would say overall thats a really solid update today.
Its a pattern we see again and again though that often when on a roll these companies perhaps end up with a bit of fluff when they are "in purple patch" - and as soon as the purple patch is gone prior p/e are restored - Volex hasnt always traded at any sort of premium - so the possibility it could go back to p/e of ten is always real and present - note the net debt has climbed over the last few years - and they have the july acquisition to pay for so its not all organic growth here/no added debt - i would say debt is very under control and looks like it was falling ignoring their recent acquisition so they are well place. I would say though we dont know how quick a dropoff could be in some of their key areas - so although it seems a ok is there a danger they could have headwinds that they dont currently anticipate - to be fair to board here they have hardly put a foot wrong over the last 2-3 years seems a much better run company than it was back in the day - perhaps its easy though if your main market segments are booming.
Zeus have just published their research note, upgrading #VLX slightly and raising EPS estimates by 3.5% across each of the next three years. This year's EPS is equivalent to 40p - putting this on a p/e of less than 15 for a company with CAGRs that few UK listed companies can match.
Any chance of a comment on Primary Health Properties (LON:PHP) JV announcement today please
I'm sure I have recently seen a similar announcement involving GIC Singapore and another UK property company - or maybe it was Malaysia Blue Owl ?
Any reason Primary Health Properties (LON:PHP) are not included in the Summaries ?
On 24/06/26 you gave them an Amber/Green rating for saying they are in talks re JV.
On 30/07/27 results came out - no mention
Today details of the agreed JV come out & again, no mention
Serica Energy (LON:SQZ) Hmmmm
Making more money on less production, with more production to come..
LSE main listing in a week and the news is timed beautifully for institutions to pick up your shares on a RNS that i) Reports increased production from the spirit assets (was 10,000 now 12,000)
ii) Says Bruce is back to 20,000 (was 18,400)
iii) Shows the benefits of the enlarged portfolio, with hints at the widened scope of activity, particularly at SGP and Ithaca's existing infill drilling program
Could be an opportunity to pick up some shares from investors who get scared at any mention of 'Triton'
As for me, I'm holding.
I agree Pool Watcher.
The market appears to be treating: “full‑year average cut” as “year‑end target cut”
These are not the same thing.
The RNS explicitly confirms:
exit rate unchanged
cashflow unchanged
guidance unchanged
drilling unchanged
liquidity strong
balance sheet strong
This is a surely a misread?
After a day thinking about the bigger picture with Serica, I am tempted to see this RNS as confirmation that the diversified portfolio does not need Triton in order to cover the Opex, Capex and the Divi.
Institutions will be scrumming to build their positions...
To me, Serica Energy (LON:SQZ) looks like a cash cow of the highest order.
Hi I am a holder and indeed very much a Serica Energy (LON:SQZ) watcher. I regard the management team very highly and to me they are always transaparent, warts and all. Yet again we have Triton issues. One wonders if this is again operator issues and how long before Chris Cox is all over them for the serial failure to maintain equipment and thus output. There does always seem to be another Triton excuse coming...
Spirit looking good so far and I am not sure the latest Triton issue has anything other than it fairly now standard intake of breath in the hope that for the next period there will be some kind of normalcy.
Not sure if the market cap makes this likely to be included in the next indicies rejig but if it is then trackers will need to buy in
If Triton can not get maintenance done in summer what chance in autumn storms
It seems maintenance was going to plan until they discovered an engine change out was needed --text from RNS
Annual maintenance at the Triton FPSO began on 27 July, with an operator expectation that it would last approximately two months. However, during the final preparation steps and safety checks for planned restart, the need for an engine change out in one of the power generation units was identified. This has resulted in the operator revising its forecast for resuming production to around the end of November
Arguably this could happen whenever but with Triton issues seem to arise far too frequently......
I've added to my Serica Energy (LON:SQZ) this morning as I can't see my holding of Sequoia Economic Infrastructure Income Fund (LON:SEQI) going anywhere much so switched away.
I agree. Overall, I still think that the numbers are moving in the right direction, so no cause for alarm, just yet. If only they could get the Triton field to be a bit more reliable, but they're working with an aging asset, that as we all no, the older they get, the more attention and maintenance is required. Like you, I'm a shareholder and am not looking to sell anytime soon.
“The French were revolting this weekend”
Really gave me an early morning laugh today - very good !
Hard to disagree that Macron has mishandled this by trying to play nice and getting tough now makes him look pretty weak. One wonders how Le Pen would deal with this....
Always wondered why the French are always revolting?
They are very pleasant when i'm on holiday.
looking at the clips, you could argue the majority revolting aren't "French"