Mulberry: full-price sales lead an in-line first half under new creative director

Analyst’s view:
I still think Mulberry should seek a buyer for the whole business who can run it more efficiently, as part of a larger organisation. As for our stance on it: the last time I covered this stock, I upgraded our view to neutral. The shares have surged by over 70% since then, but I don't think market expectations have moved. So I'm going to stay neutral on it again today.
Up 7% at 245.5p (£173m) - Half Year Trading Update
This is an in line update from the "lifestyle brand" that is most well known for its luxury handbags.
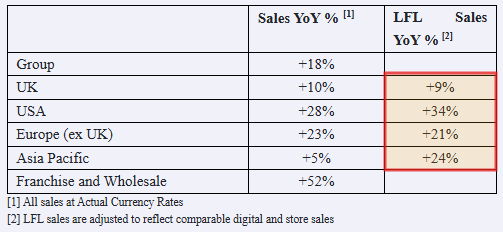
The right-hand column is more meaningful to me: "adjusted to reflect comparable digital and store sales".
These are some pretty impressive growth rates, even in the UK which was the weakest region.
Overview:
Performance in H1 was supported by strong customer demand across both seasonal and core collections. New product introductions, including Raffia, Crochet, Stevie and Darley Camera Bag performed particularly well, alongside continued demand for icons such as the Bayswater and Lily. Recent performance has also benefited from heightened brand visibility following the Mulberry by Christopher Kane runway show at London Fashion Week.
Christopher Kane is Mulberry's new creative director; he brings a big reputation in the industry with him. The Guardian offers more coverage of his work at London Fashion Week here.
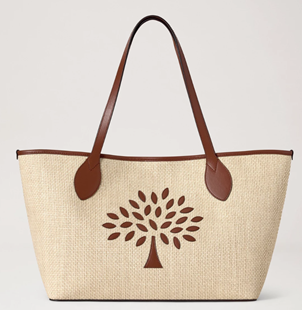
Of if you're simply curious to see what a Raffia bag looks like, here you go. The price is £595:
Medium-term financial targets:
The Group remains focused on continuing to rebuild gross margin and on restoring profitability, targeting annual revenue of more than £200m and a 15% adjusted EBIT margin over the medium term.
Context: in FY March 2026, revenues were £125.5m and the company generated an underlying pre-tax loss of £8m.
CEO comment:
“We are very pleased with the progress made during H1... The growth in full-price sales is particularly encouraging, demonstrating that our collections are resonating with customers across our key markets....
There remains much more to achieve as part of our strategic plan, and we are operating in a challenging trading environment. However, we enter the second half with a strong product pipeline, increased brand desirability and a clear focus on delivering our strategy.”
Graham's view
The company - for sound commercial reasons, I suppose - doesn't provide a complete breakdown full-price sales, promotional sales, and markdown sales.
But gross margin does have to be disclosed, and it grew last year from 67% to 72%.
And for H1 FY27, we are told that promotional sales have become a lower proportion of total sales, "supporting gross margin performance", so hopefully we'll see yet more progression on that front this year.
But I think the bigger picture is the Mulberry does need to grow significantly, if it's going to generate consistent profitability.
Its gross margins are already very high (several percentage points higher than Burberry (LON:BRBY), in which I have a long position). And its underlying operating expenses haven't been growing very fast (only up 2% in FY26). What it needs is a significantly bigger revenue base so that operational leverage can start to kick in for it again.
Note that it had some strong years earlier this decade, when revenues were over £150m. If revenues can get to £150-200m, hopefully we'll start to see results like this again:
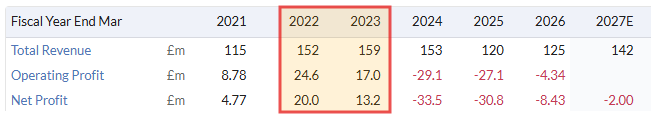
Because at its recent scale, profits are going to be slim at best. In July, I noted that H2 FY26 was breakeven after H1 was loss-making.
So my view here is unchanged. I think Mulberry should probably seek a buyer for the whole business who can run it more efficiently, as part of a larger organisation.
As for our stance: the last time, I covered Mulberry, I upgraded our view to neutral. The shares have surged by over 70% since then, but I don't think market expectations have moved:
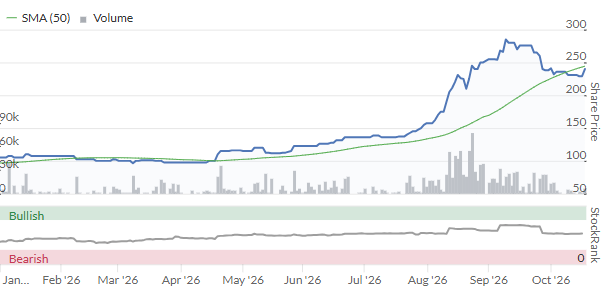
So I'm going to stay neutral on it again today. I still have worries about its ability to grow its way into consistent profitability, and its less obviously a bargain to a trade buyer at the current, higher share price. But the business is moving in the right direction, and if it does approach £200m of revenues then it has a real chance to succeed as a standalone entity.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Mulberry (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?