Volex: organic growth of 21% slows to a more normal pace, profit near top of range

Analyst’s view:
Roland normally covers this stock, not I. In August, he was moderately positive. It seems to me that little has changed today. There may be some disappointment among investors that extraordinary growth is coming to an end, but that was already baked into forecasts. Unless there has been some behind-the-scenes downgrade that I've missed, I think it makes sense to leave our moderately positive stance unchanged for now.
Down 6% at 597p (£1.08bn) - Half Year Trading Update
Volex plc (LSE: VLX), the specialist integrated manufacturer of critical power and data transmission products, today issues a trading update for the six months ended 30 September 2026.
As noted in the comments today, Volex has seen a surprisingly negative share price reaction given the headline: FY2027 profit expected to be towards the upper end of current market expectations.
Key points:
H1 revenue of at least $710m with $11m of that from Kepler SignalTek, acquired in July.
Organic, constant-currency revenue growth at least 21%.
This key paragraph explains that year-on-year growth is less meaningful than half-on-half growth:
As indicated in the Group's AGM statement in August, headline year-on-year growth rates have started to normalise from the 28% reported for the first four months of the year, as the Data Centre programmes that ramped up in the prior year annualise. Sequential trading remains the better guide, with first half revenue expected to be approximately 7% higher than in the second half of FY2026 on an organic constant currency basis.
This is perfectly logical: the Data Centre boom last year was extraordinary, and growth rates now have to return to something sustainable. So 7% half-on-half growth is what we should be focusing on, rather than 21% year-on-year growth.
There are a few other reasons to expect growth to moderate, mentioned in today's update.
Within the "Complex Indistrial Technology" segment, $10m of orders have been pulled forward into H1 that would otherwise have appeared in H2.
Also within this segment, Data Centre-specific revenues have fallen in H1 FY27 compared to H2 FY26. The prior period saw Volex "meeting customers' near-term capacity needs at a time when other suppliers were unable to do so". Supply conditions have since normalised.
In addition to the potential for revenue growth to calm down, I'd also have to wonder about the sustainability of profits given that last year saw such extreme market conditions. Volex says that their "view of the medium and long term growth opportunity is unchanged" - often something that companies say when the short-term has been a little more complicated than anticipated.
Leverage is thought to be no more than 1.2x, and a £20m buyback is ongoing.
Outlook:
Second half revenues are expected to be broadly similar to the first half, after allowing for the revenue brought forward ahead of the US site consolidation, with current trading conditions expected to continue across most end-markets. The Board expects FY2027 underlying operating profit to be towards the upper end of current market expectations.
Market expectations are helpfully provided: underlying operating profit of $150.4 million, with a range of $145.9 million to $153.3 million.
Graham's view
As noted in reader comments today, it seems that markets were already expecting a profit result towards the upper end of the range. Indeed, if I was being really pedantic, I'd point out that the consensus figure ($150.4m) is itself towards the upper end of the $145.9-153.3m range. So if Volex merely hits that consensus estimate, they will be towards the upper end of the range!
And it seems that regardless of the precise figure they achieve, they are on track to exceed by a wide margin the $138.3m estimate which was in place as recently as the August AGM.
Checking forecasts from Zeus, published earlier this month, I see that Adj. EBIT (which should be identical to underlying profit) is seen rising to $161.8m next year (FY March 2028) and then $174.5m the year after that.
Revenue growth is seen at 10% this year, 6.5% next year (FY27) and then 7% in FY28.
All of which sounds very reasonable to me for a stock that is not trading at extreme valuation numbers:
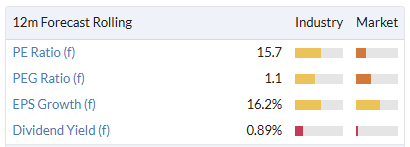
Roland normally covers this stock, not I. In August, he was moderately positive. It seems to me that little has changed today. There may be some disappointment among investors that extraordinary growth is coming to an end, but that was already baked into forecasts. Unless there has been some behind-the-scenes downgrade that I've missed, I think it makes sense to leave our moderately positive stance unchanged for now.
Update: thanks to readers for pointing out that the latest Zeus note has hit Research Tree, and it shows slight increases to forecasts. The new Adj. EBIT forecast for FY27 is $153.8m, up 2.4%, and outer years are also upgraded by 2.4% (FY28: $165.7, FY28: $179.7m). Revenue forecasts are upgraded for every year by c. 2%.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Volex (10)
Comments here are also visible in the Daily Stock Market Report
Volex (LON:VLX)
So maybe "good value" rather than "cheap"!
Yes indeedy thanks for clarification - note bearing in mind the modest upgrades for next year and year after i would say overall thats a really solid update today.
Its a pattern we see again and again though that often when on a roll these companies perhaps end up with a bit of fluff when they are "in purple patch" - and as soon as the purple patch is gone prior p/e are restored - Volex hasnt always traded at any sort of premium - so the possibility it could go back to p/e of ten is always real and present - note the net debt has climbed over the last few years - and they have the july acquisition to pay for so its not all organic growth here/no added debt - i would say debt is very under control and looks like it was falling ignoring their recent acquisition so they are well place. I would say though we dont know how quick a dropoff could be in some of their key areas - so although it seems a ok is there a danger they could have headwinds that they dont currently anticipate - to be fair to board here they have hardly put a foot wrong over the last 2-3 years seems a much better run company than it was back in the day - perhaps its easy though if your main market segments are booming.
Hi Graham
Zeus have modestly increased their forecasts for Volex (LON:VLX) for years FY27 to FY29
Their brokers note is available on Research Tree.
Volex (LON:VLX)
If they achieve forecasts on Stocko, they are sitting on a PE of 12.1 for this year and 10.6 for next year. That's cheap in my view .
is the pe that cheap ? i know stocky this morning had pe of 15.7 - shareprice has dropped a bit today but then we have dollar and cents figures - are you 100% sure that your calcs are correct ?
Your right - I'm wrong - thank you for pointing it out so politely!
Need to multiply by the exchange rate (currently 1.33). So PEs of 15.7 and 13.8. So maybe "good value" rather than "cheap"!
Volex (LON:VLX)
So maybe "good value" rather than "cheap"!
Yes indeedy thanks for clarification - note bearing in mind the modest upgrades for next year and year after i would say overall thats a really solid update today.
Its a pattern we see again and again though that often when on a roll these companies perhaps end up with a bit of fluff when they are "in purple patch" - and as soon as the purple patch is gone prior p/e are restored - Volex hasnt always traded at any sort of premium - so the possibility it could go back to p/e of ten is always real and present - note the net debt has climbed over the last few years - and they have the july acquisition to pay for so its not all organic growth here/no added debt - i would say debt is very under control and looks like it was falling ignoring their recent acquisition so they are well place. I would say though we dont know how quick a dropoff could be in some of their key areas - so although it seems a ok is there a danger they could have headwinds that they dont currently anticipate - to be fair to board here they have hardly put a foot wrong over the last 2-3 years seems a much better run company than it was back in the day - perhaps its easy though if your main market segments are booming.
Volex (LON:VLX)
Surprisingly muted reaction to what is a good trading update. Perhaps there was an expectation of more and/or the fear that the AI spending spree has run its course.
The latter is only part of the equation insofar as Volex (LON:VLX) is concerned. With operating margins heading towards 12% on increased revenue now is not the time to sell in my opinion, more likely it is a time to add.
The view of Graham and his colleagues would be welcome, time permitting.
I hold.
I agree Jonno, strange response to what seemed like a positive update. any thoughts from the team gratefully received, although I have added to my position already ;-)
I also agree Jonnp re Volex (LON:VLX)
And presumably the EV side of the business will be getting a boost from the move to electric vehicles in the face off the current very high fuel costs
Volex (LON:VLX)
Surprisingly muted reaction to what is a good trading update
i think its the drop in growth rate ref sales here that is teh issue - yes they are towards the top end of expectations now - so that perhaps an uptick of $1 to $2 mill ref profits. however the current estimated figure quoted is already closer to the top end than the bottom anyway ref range expectations so its kinda odd that were are already there ish in some respects - presumbably its a laggard ot two near then bottom creating that situation.
I think the normalisation of growth rates that is perhaps what might put a semi downer on things - sometimes you can be a victim of your own success when things are going well that if you have purple patch with the benefit of hinsight the later period kinda looks not as rosy when lfl's are concerned. Seems like they have flagged it up reasonably previoously though - but if they say sequential trading "is the best guide" and are also saying h2 revenues are likely to be flat is that them conceding there is nil growth now H2?
they seem positive ref trend in margins though so perhaps profits can go up faster than revenues.
I would be interested to see if there are any changes to 2028 expectations - as ever the behind the scenes nod and wink is often more important what they actually tell shareholders
per todays update.
As indicated in the Group's AGM statement in August, headline year-on-year growth rates have started to normalise from the 28% reported for the first four months of the year, as the Data Centre programmes that ramped up in the prior year annualise. Sequential trading remains the better guide, with first half revenue expected to be approximately 7% higher than in the second half of FY2026 on an organic constant currency basis.
Second half revenues are expected to be broadly similar to the first half, after allowing for the revenue brought forward ahead of the US site consolidation, with current trading conditions expected to continue across most end-markets.
First half underlying operating profit1 margin is expected to show progress towards the Group's medium term target of 12%, reflecting an improving revenue mix, including the higher-margin contribution from KST, and further operational efficiencies. Operating expenses continue to be managed closely, with investment in capacity and capabilities focused on supporting the Group's medium term strategic plan.
If they achieve forecasts on Stocko, they are sitting on a PE of 12.1 for this year and 10.6 for next year. That's cheap in my view .
Volex (LON:VLX)
If they achieve forecasts on Stocko, they are sitting on a PE of 12.1 for this year and 10.6 for next year. That's cheap in my view .
is the pe that cheap ? i know stocky this morning had pe of 15.7 - shareprice has dropped a bit today but then we have dollar and cents figures - are you 100% sure that your calcs are correct ?
Your right - I'm wrong - thank you for pointing it out so politely!
Need to multiply by the exchange rate (currently 1.33). So PEs of 15.7 and 13.8. So maybe "good value" rather than "cheap"!
Volex (LON:VLX)
So maybe "good value" rather than "cheap"!
Yes indeedy thanks for clarification - note bearing in mind the modest upgrades for next year and year after i would say overall thats a really solid update today.
Its a pattern we see again and again though that often when on a roll these companies perhaps end up with a bit of fluff when they are "in purple patch" - and as soon as the purple patch is gone prior p/e are restored - Volex hasnt always traded at any sort of premium - so the possibility it could go back to p/e of ten is always real and present - note the net debt has climbed over the last few years - and they have the july acquisition to pay for so its not all organic growth here/no added debt - i would say debt is very under control and looks like it was falling ignoring their recent acquisition so they are well place. I would say though we dont know how quick a dropoff could be in some of their key areas - so although it seems a ok is there a danger they could have headwinds that they dont currently anticipate - to be fair to board here they have hardly put a foot wrong over the last 2-3 years seems a much better run company than it was back in the day - perhaps its easy though if your main market segments are booming.
Zeus have just published their research note, upgrading #VLX slightly and raising EPS estimates by 3.5% across each of the next three years. This year's EPS is equivalent to 40p - putting this on a p/e of less than 15 for a company with CAGRs that few UK listed companies can match.